5 Steps to Secure First Time Buyer Mortgages with Bad Credit

Introduction
Many first-time buyers with bad credit find themselves at a crossroads, unsure of how to move forward in their quest for homeownership. This guide will empower you with five essential steps to secure a mortgage, even in the face of credit challenges. By following this roadmap, you can take control of your financial future.
However, with numerous options and potential pitfalls, understanding how to enhance your creditworthiness and identify the right mortgage solution is crucial.
Assess Your Credit Score and Financial Health
Navigating the complexities of selling your home can be daunting, especially when first time buyer mortgages bad credit might hold you back.
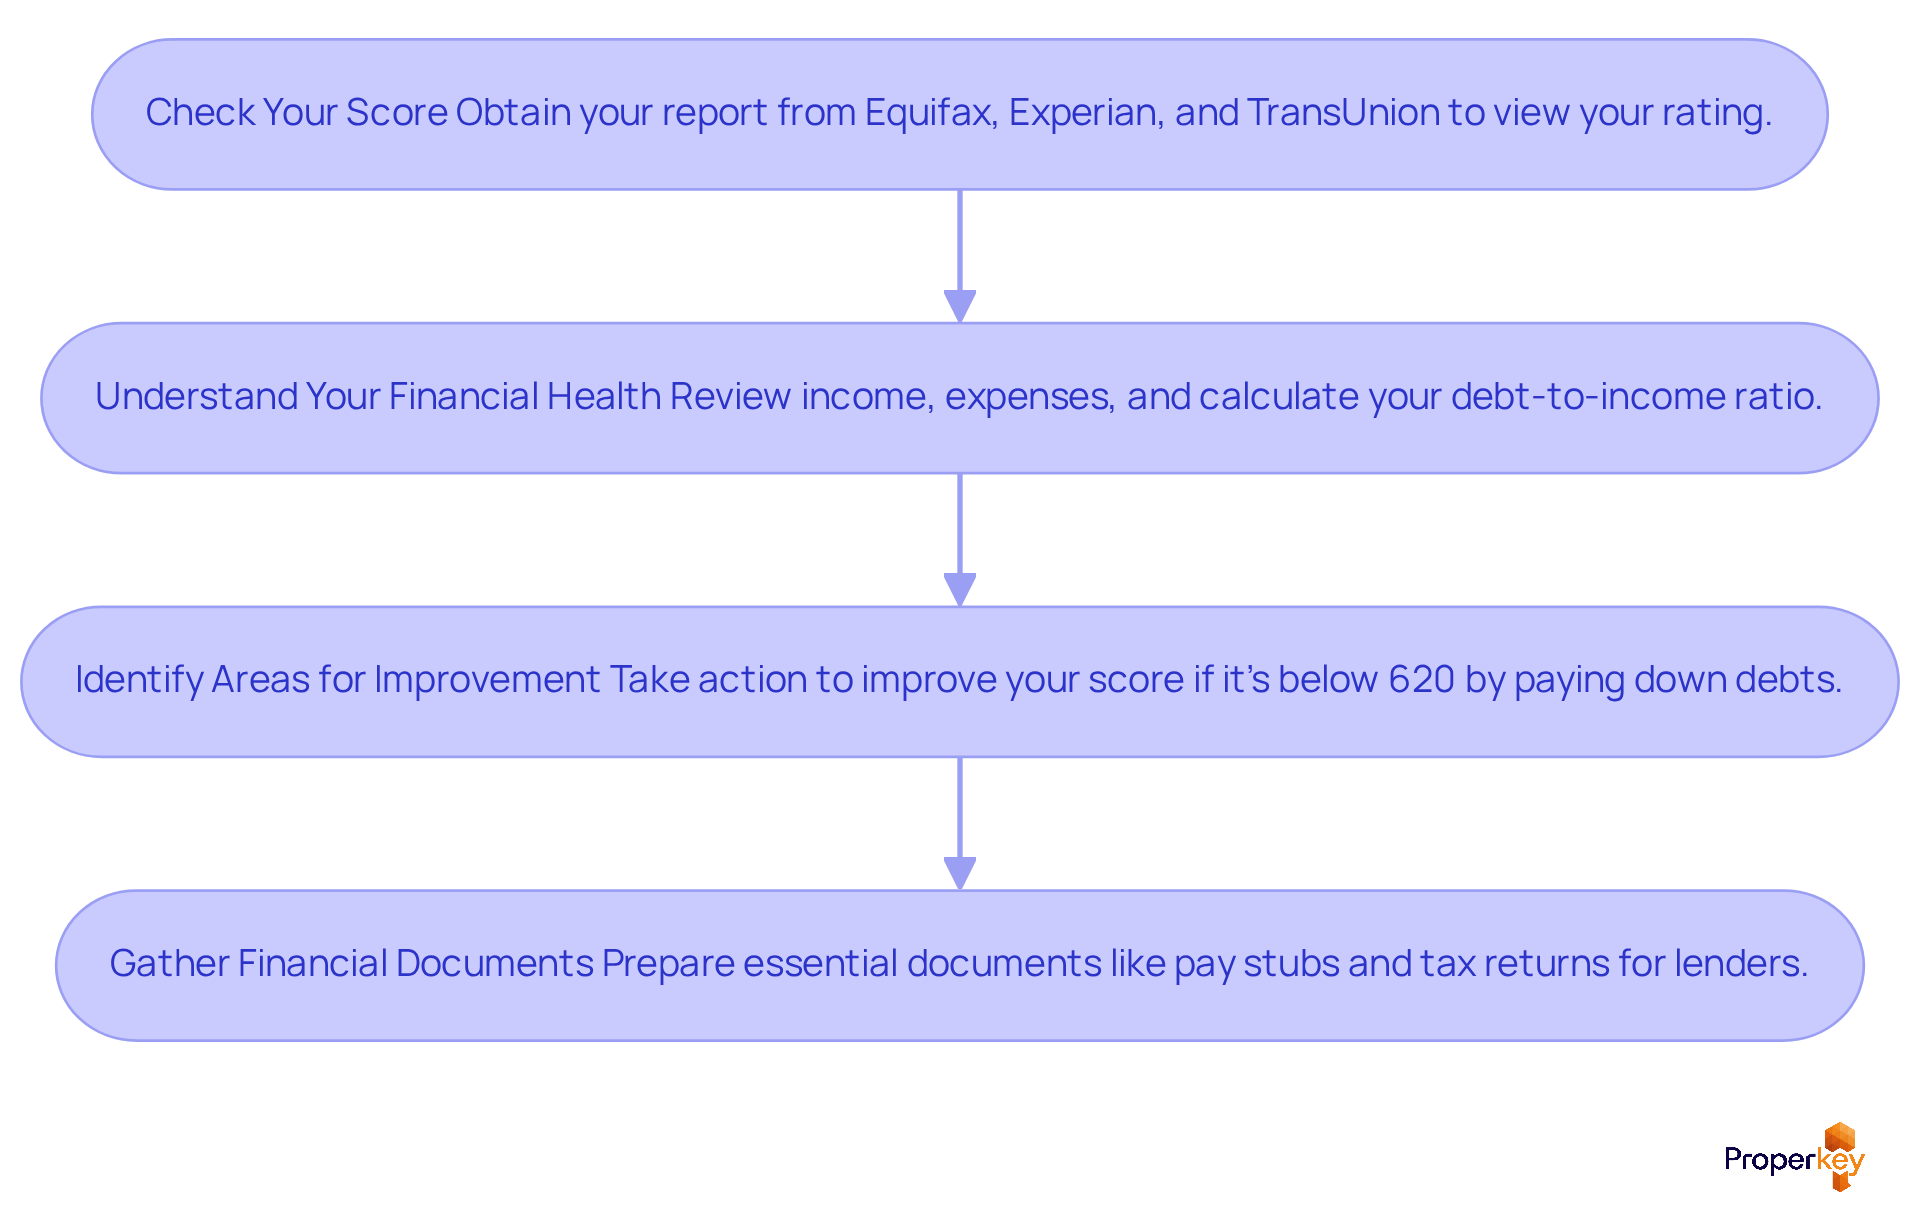
- Check Your Score: Start by obtaining your report from the major bureaus - Equifax, Experian, and TransUnion. This will provide you with a clear view of your current rating and assist you in recognizing any inconsistencies or mistakes that could adversely affect your rating. In California, the average rating is approximately 721, which is a favorable standard to strive for.
- Understand Your Financial Health: Take a close look at your income, expenses, and existing debts. Calculate your debt-to-income (DTI) ratio, which ideally should be below 36% to qualify for most mortgage options. This ratio is crucial as it reflects your ability to manage monthly payments alongside your other financial obligations. With Vana, you can quickly qualify and receive your Loan Qualification Letter in no time, making the process more accessible.
- Identify Areas for Improvement: If your score falls below 620, it’s time to take action and improve it. Focus on paying down existing debts and ensuring timely bill payments. For instance, maintaining a low credit utilization ratio and keeping older accounts active can significantly enhance your rating over time. These actions are especially significant as numerous financial institutions in California may demand a minimum score of 620 for first time buyer mortgages bad credit. Additionally, Vana offers a full Loan Approval Letter for FREE when qualified, giving you a stronger position when negotiating.
- Gather Financial Documents: Prepare essential financial documents such as pay stubs, tax returns, and bank statements. These documents give lenders a clear picture of your financial situation. This clarity is essential for securing a mortgage. With Vana's clear borrowing guidelines and resources, including Fannie Mae and Freddie Mac standards, you can ensure that you meet all necessary criteria.
Taking these steps not only positions you for a successful sale but also empowers you to secure the best financing options available.
Explore Mortgage Options for Bad Credit
Navigating the complexities of financing options can be daunting for home sellers, especially in a competitive market like California.
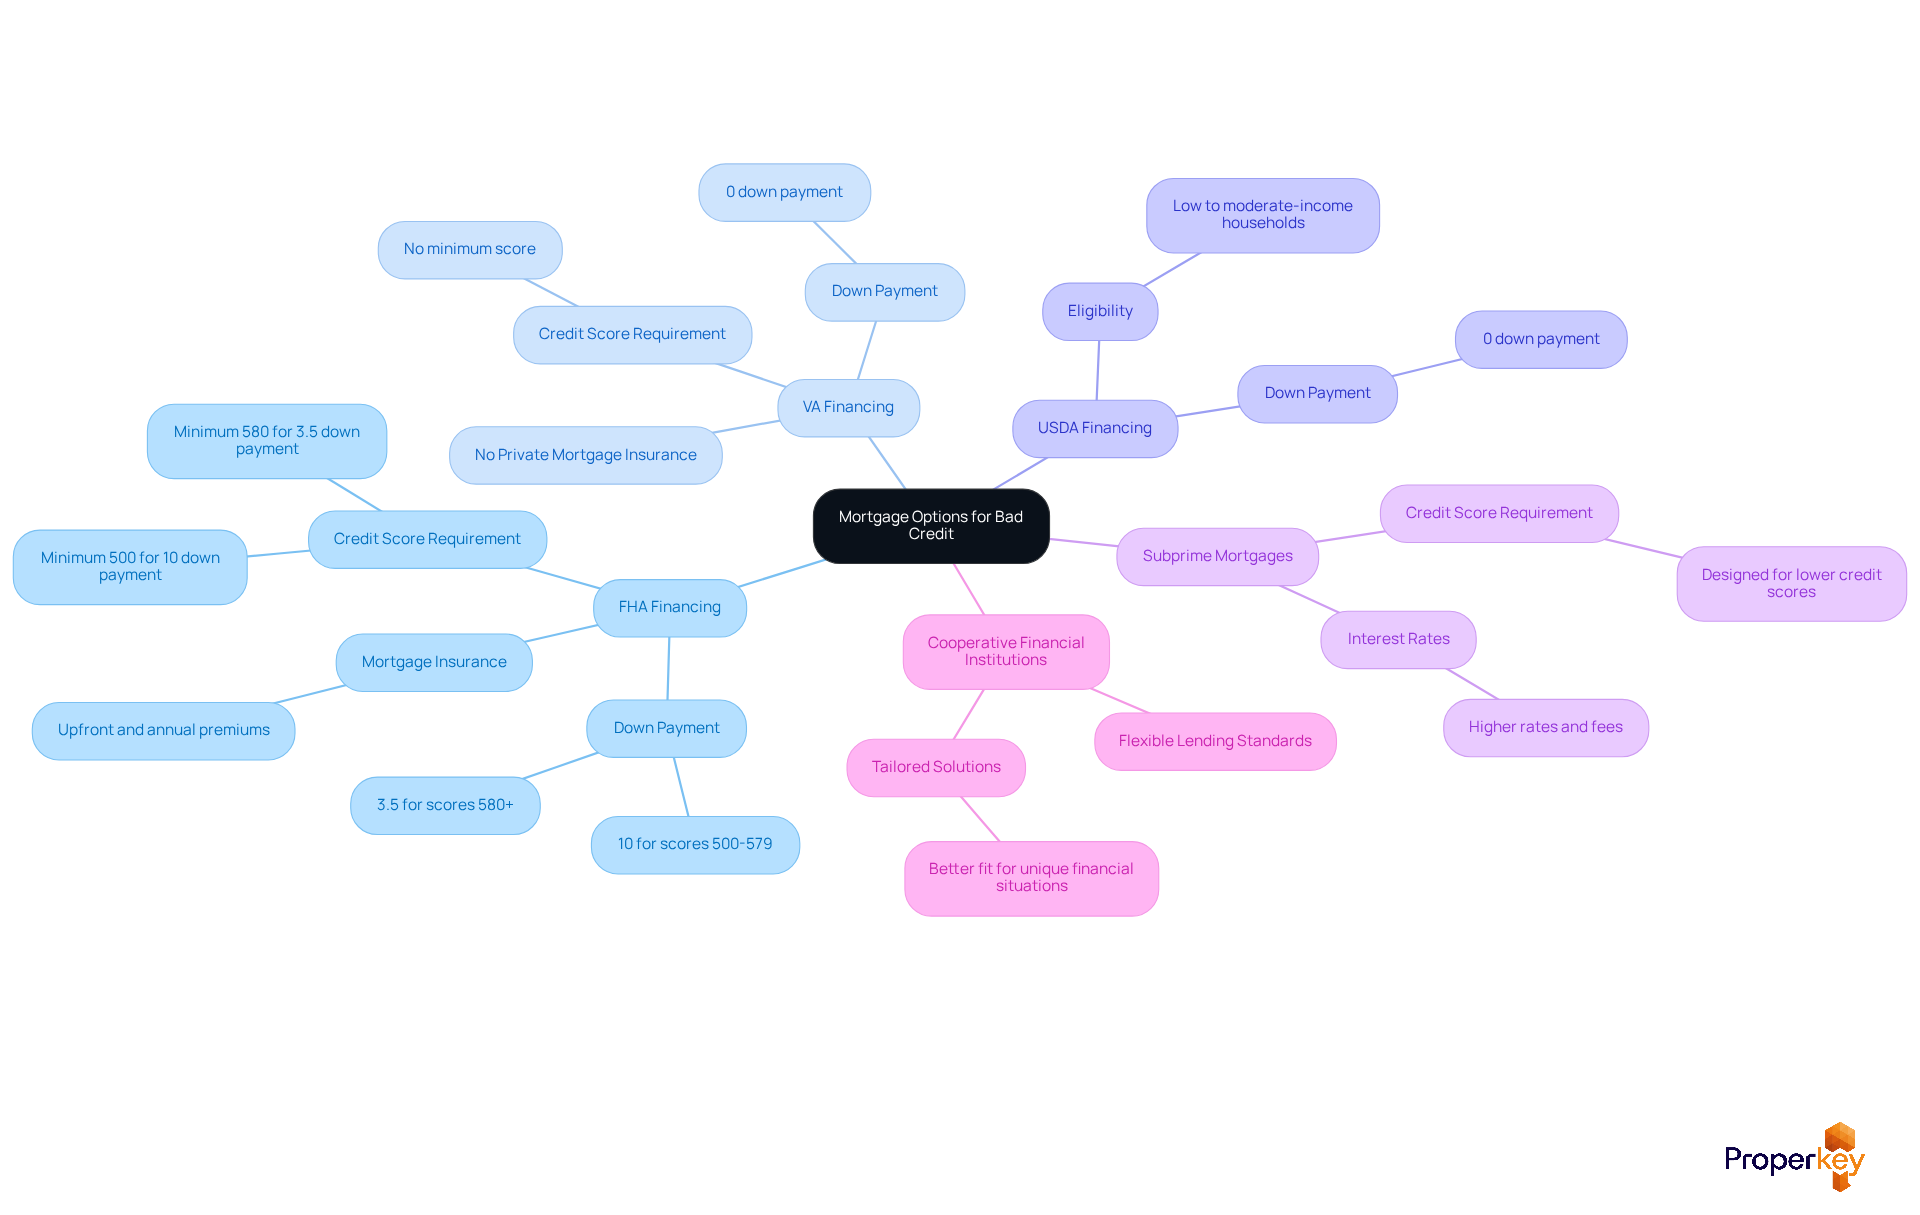
- FHA financing, supported by the Federal Housing Administration, offers first time buyer mortgages bad credit options to borrowers with ratings as low as 500, provided they make a 10% down payment. If your rating is 580 or higher, you only need a 3.5% down payment, which is great news for first-time buyers in California.
- VA Financing: Veterans and active-duty service members can benefit from VA financing, which has no minimum score requirement. With no down payment and no private mortgage insurance, VA financing is a fantastic option for veterans and active-duty service members.
- USDA Financing: For those interested in rural properties, USDA financing serves low to moderate-income households and often includes flexible financial criteria. These options can be a viable choice for buyers looking to purchase homes outside urban areas in California.
- Subprime Mortgages: Some lenders provide subprime mortgages designed for those with lower credit scores, but be careful - these often come with higher interest rates and fees.
- Cooperative Financial Institutions and Community Borrowers: Working with cooperative financial institutions or community lenders can be beneficial, as they often have more flexible lending standards compared to larger banks. These institutions may offer tailored solutions that better fit the unique financial situations of borrowers with lower ratings, such as those seeking first time buyer mortgages bad credit.
By grasping these financing options, you can avoid costly mistakes and seize opportunities that align with your financial aspirations.
Obtain Pre-Approval for Your Mortgage
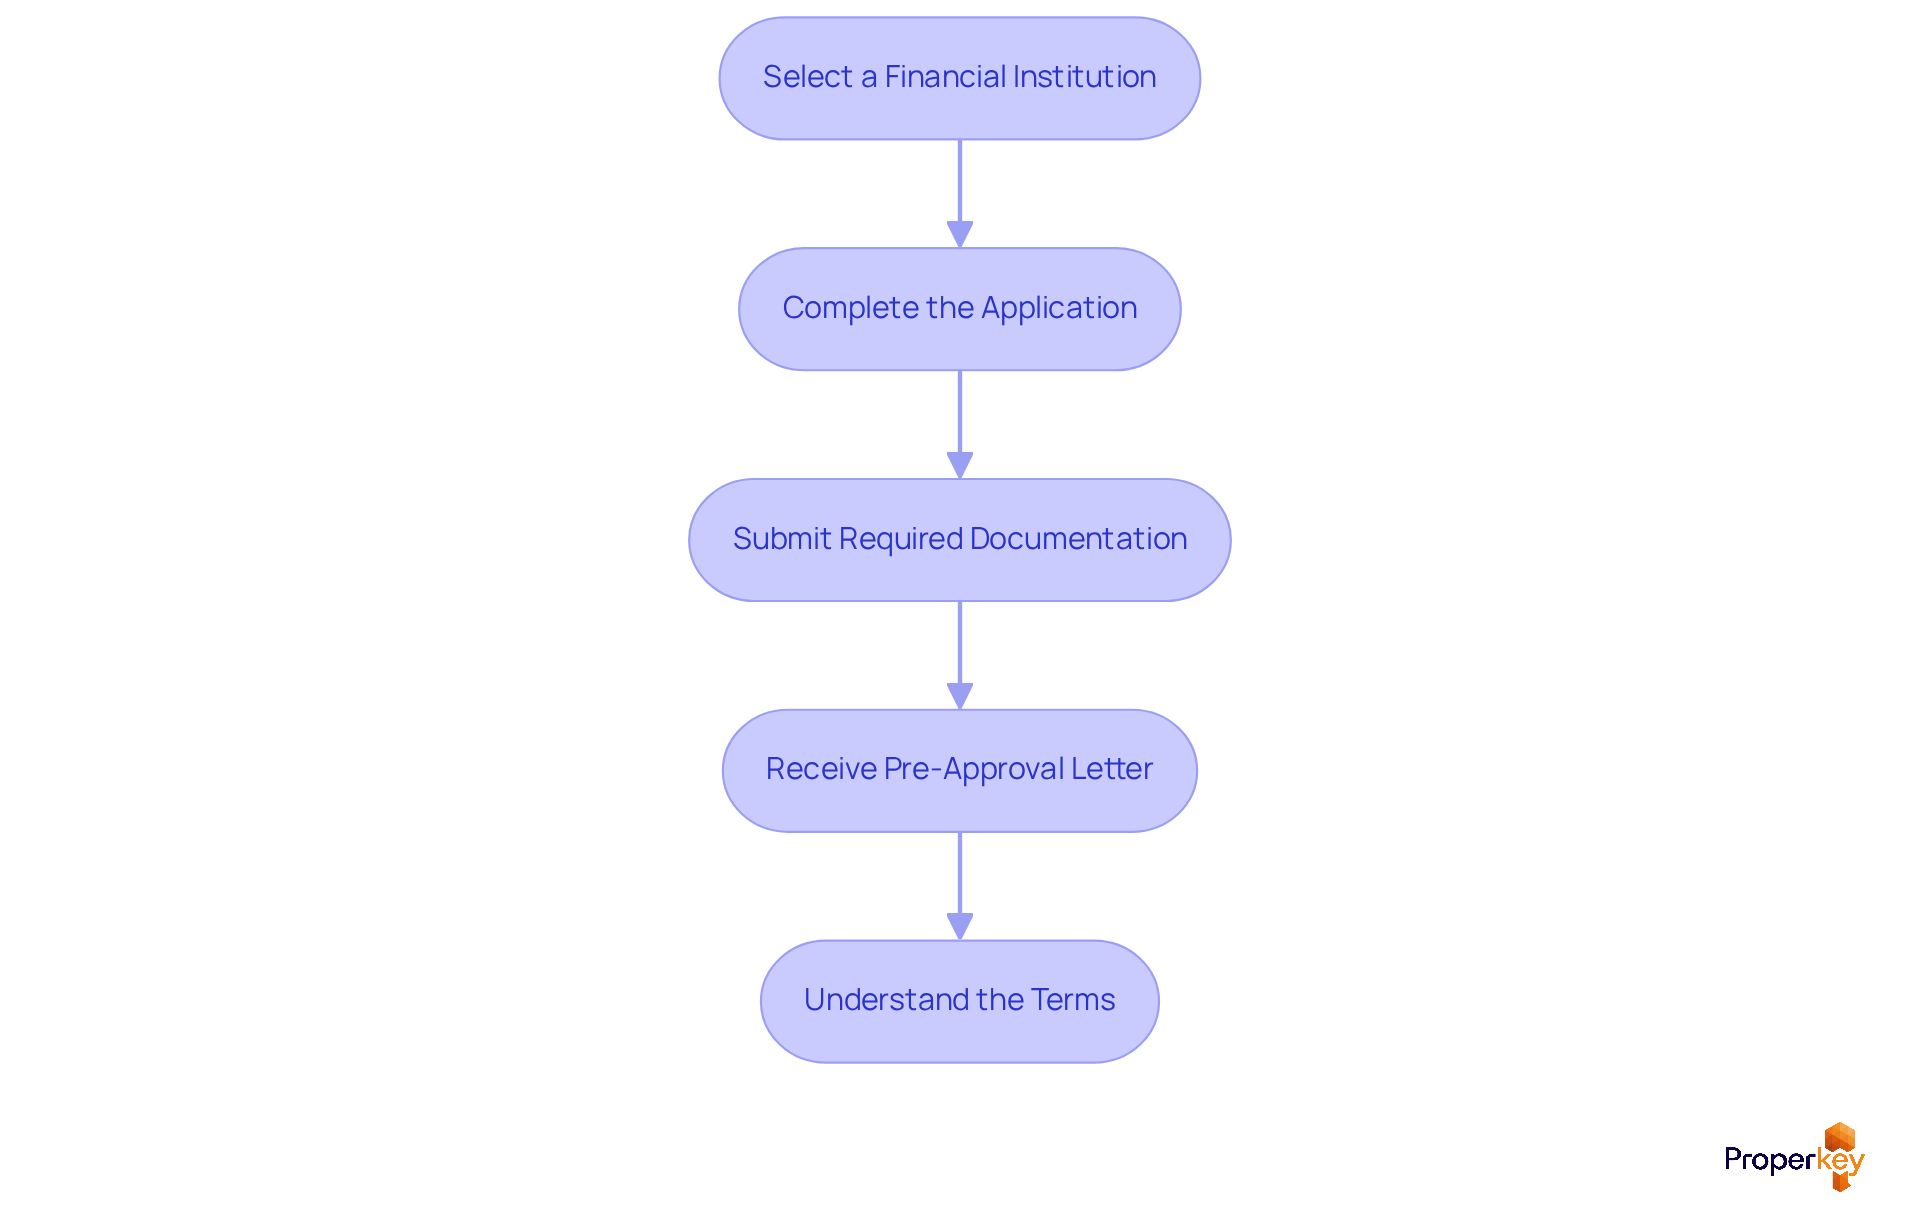
- Select a financial institution that offers first time buyer mortgages bad credit by investigating organizations that focus on this type of mortgage. Look for those with positive reviews and a track record of helping buyers in similar situations. In California, many financial institutions are increasingly accommodating, with approximately 28% of approved applications in 2023 being for first-time homebuyers, indicating a growing focus on accessibility. Utilize Properkey's Free Loan Analysis to uncover your refinancing options and maximize your savings on your mortgage.
- Complete the Application: Fill out the mortgage application thoroughly, detailing your financial situation, including income, debts, and assets. This transparency allows lenders to assess your eligibility with precision. If you're already in the process, show your written loan estimate (LE) to see if Properkey can beat it.
- Submit Required Documentation: Provide essential documents such as your credit report, proof of income, and bank statements. In California, you’ll need about 14 documents for your mortgage application. Plus, 53% of financial institutions now require extra documentation for gig workers. Being organized can significantly speed up the process.
- Receive Pre-Approval Letter: After your application is reviewed, the lender will issue a pre-approval letter, which outlines how much you can borrow. This letter is vital when making offers on homes, especially in competitive markets where sellers prioritize serious buyers. As Wesley Denison, a Senior Client Advisor, notes, "In California, sellers rarely consider offers that do not include a pre-approval letter." Properkey can provide your Loan Qualification Letter immediately, or even a full Loan Approval Letter for free when qualified.
- Understand the Terms: Carefully review the terms of your pre-approval, including the interest rate and amount of credit. Ensure you are comfortable with these terms before proceeding, as understanding your financial obligations is crucial for long-term success in homeownership. Furthermore, be mindful that a debt-to-income (DTI) ratio can greatly influence your approval rates, particularly for first time buyer mortgages bad credit. Utilize Loanvana's financing tool, which allows you to apply once and compare hundreds of loan options side-by-side from multiple lenders, ensuring you find the best rates available. Understanding your financial obligations is not just about securing a loan; it’s about paving the way for a successful future in homeownership.
Improve Your Credit Score Before Applying
Many home sellers face the daunting challenge of navigating their credit scores, which can significantly impact their selling experience. Here are some essential steps to enhance your creditworthiness:
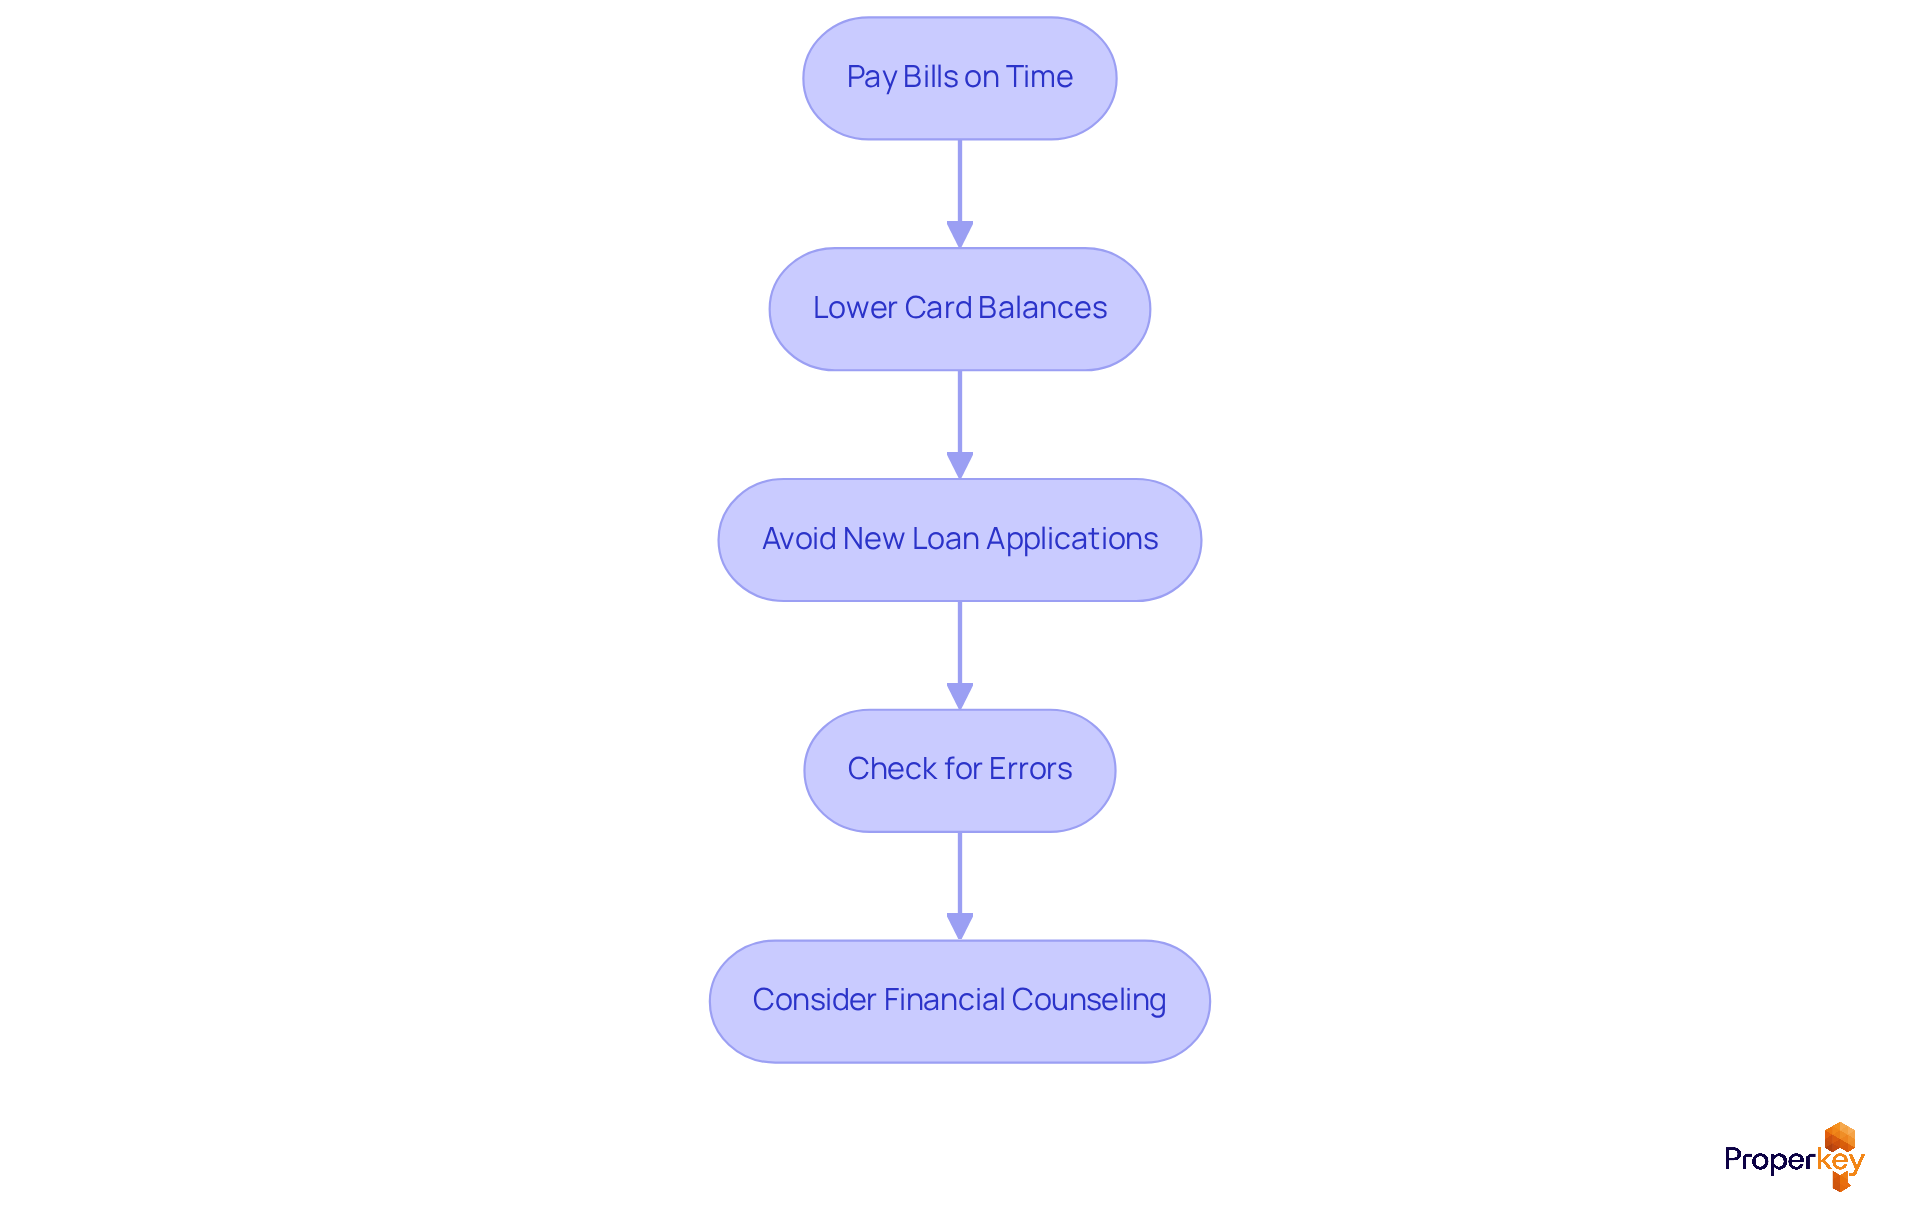
- Pay Bills on Time: Did you know that prompt bill payments are crucial? They account for 35% of your financial rating. Setting up automatic payments can help ensure you never miss a due date, protecting your score from the negative effects of late payments.
- Lower Card Balances: Keeping your credit utilization below 30% is vital for a strong credit score. Aim to reduce existing balances; for example, lowering a balance from $8,000 to $3,000 can greatly enhance your financial profile, making you more attractive to lenders.
- Avoid New Loan Applications: Before applying for a mortgage, it's wise to refrain from opening new accounts. Each new application can lead to hard inquiries that temporarily lower your score, which can be particularly harmful when you're seeking mortgage approval.
- Check for Errors: Make it a habit to check your financial report for errors - it's a simple yet powerful way to boost your creditworthiness. You can obtain a free report from each of the three major agencies at AnnualCreditReport.com. Disputing inaccuracies can lead to improvements in your score, and even minor corrections can make a significant difference.
- Consider Financial Counseling: If you're struggling to boost your score on your own, consider reaching out to a certified financial counselor who can offer personalized guidance. These professionals can provide tailored strategies to help you manage debt, create budgets, and negotiate with creditors effectively.
Taking proactive steps to enhance your credit score can open doors to better options for first time buyer mortgages bad credit and ultimately lead to a more successful sale.
Budget for Additional Home Buying Costs
Selling your home in California? Understanding the hidden costs is crucial to maximizing your profit.
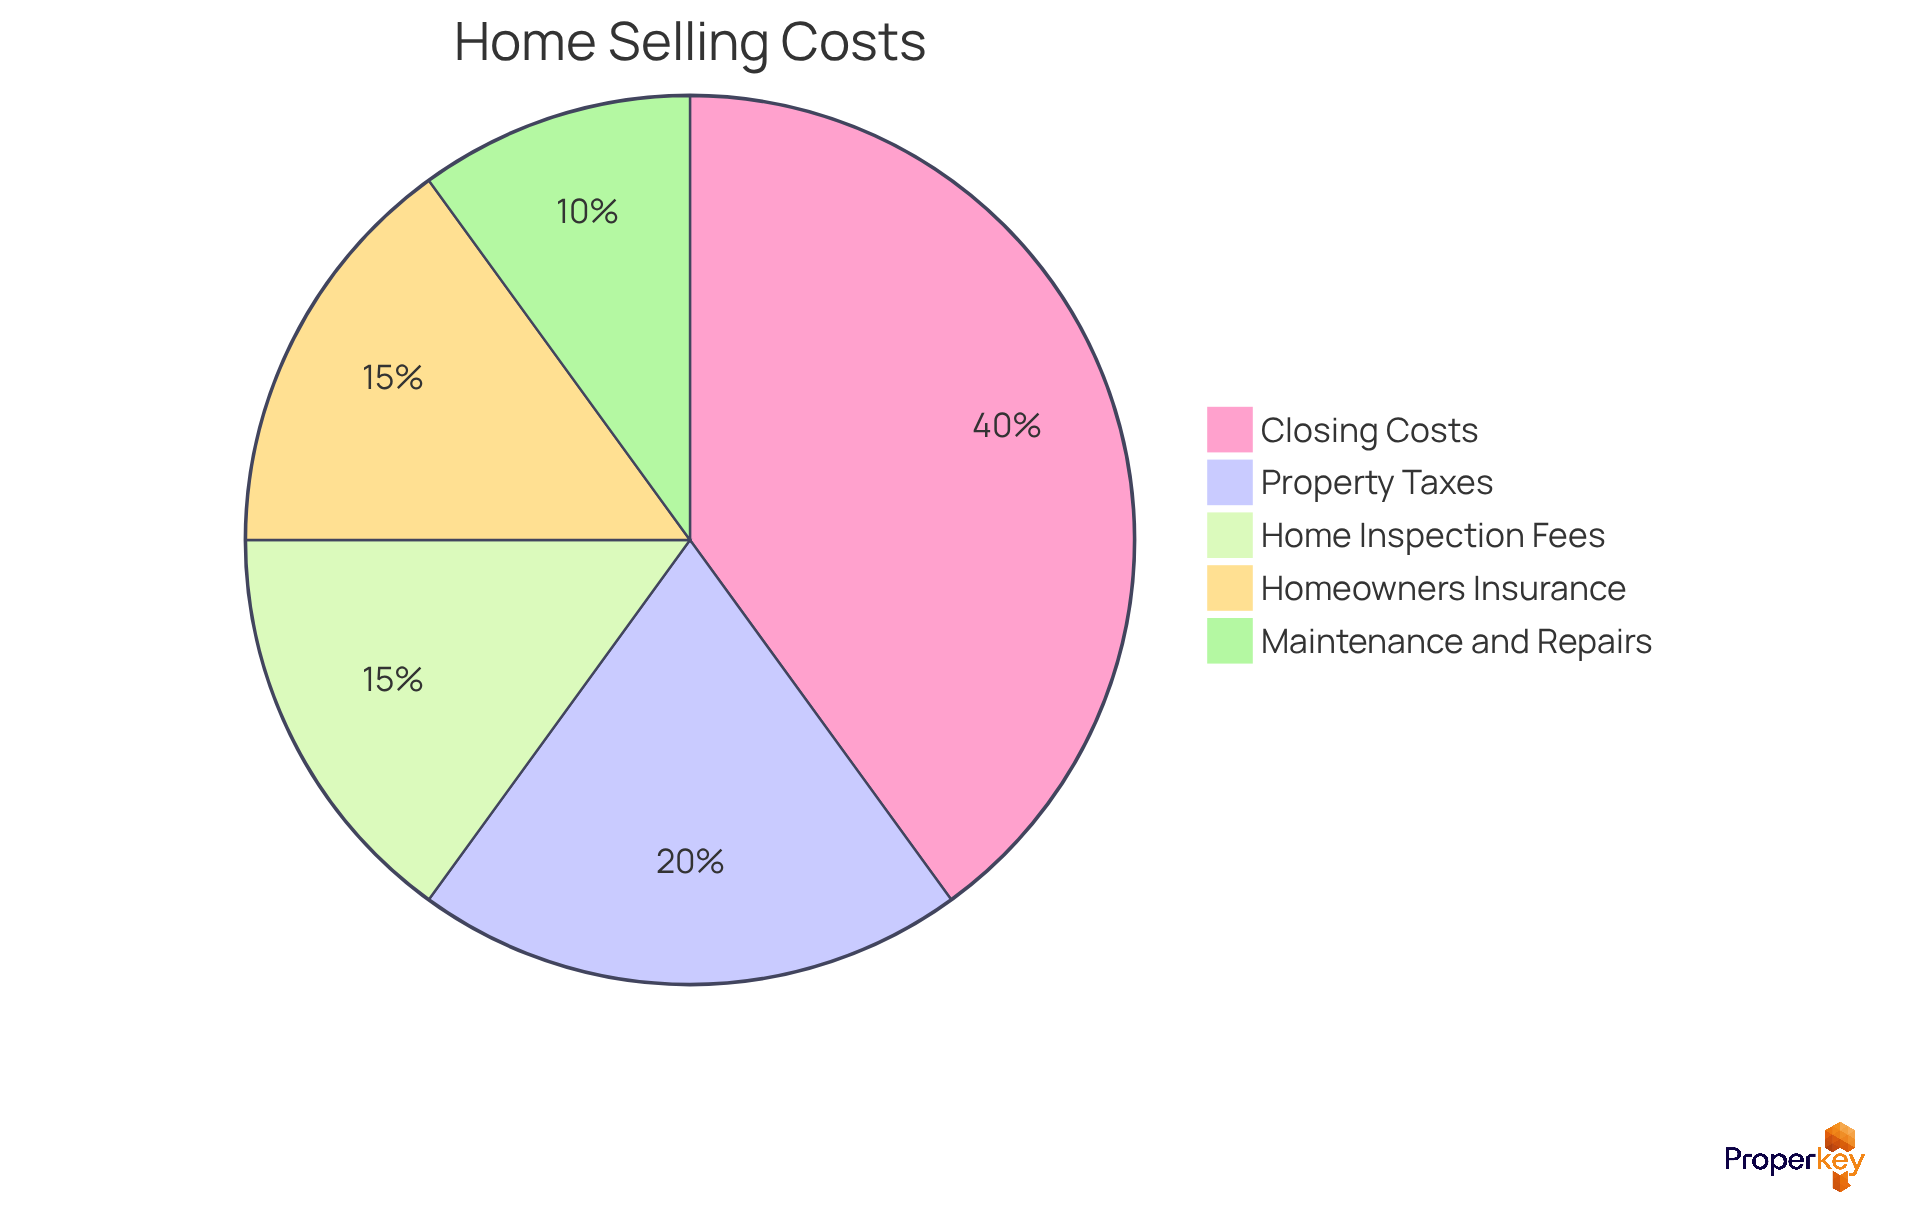
- Closing Costs: In California, closing costs typically range from 2% to 5% of the home's purchase price. These essential fees encompass title insurance, appraisal costs, and attorney services, all of which can add up quickly. For instance, on a $400,000 home, buyers can expect to pay between $8,000 and $20,000 in closing costs, which can be partially offset by seller concessions in a buyer-friendly market.
- Home Inspection Fees: You’ll want to set aside some funds for a home inspection, which typically costs between $300 and $500. This inspection helps identify potential issues with the property, allowing buyers to negotiate repairs or price adjustments. Approximately 20-30% of inspections uncover significant defects that could affect the sale terms.
- Property Taxes: Understanding local property tax rates is essential, as they can significantly impact your monthly payments and overall budget. In California, property taxes typically hover around 1.5% of the assessed value, but buyers should be prepared for supplemental property tax bills after closing due to reassessment under Proposition 13.
- Homeowners Insurance: Getting multiple quotes for homeowners insurance is a smart move, as lenders often require it and costs can vary widely. Insurance costs can range from $1,000 to $3,000 annually for a $400,000 home. It’s advisable to compare multiple quotes to find the best coverage at a competitive rate.
- Maintenance and Repairs: It’s wise to budget for ongoing maintenance and unexpected repairs, as experts recommend setting aside 1% to 4% of your home’s value annually. This proactive approach can help mitigate the financial impact of unforeseen issues, ensuring a smoother homeownership experience.
By preparing for these costs, you position yourself for a successful sale and a smoother transition into your next chapter.
Conclusion
Many first-time buyers feel overwhelmed by the thought of their credit history holding them back, but it doesn't have to be this way. Securing a mortgage as a first-time buyer with bad credit is entirely achievable with the right approach and knowledge. Get to know your credit score, check out different mortgage options, obtain pre-approval, improve your creditworthiness, and budget for additional costs. With these steps, you can navigate the home-buying process with confidence.
Key insights from this guide emphasize the importance of assessing your financial health and taking proactive steps to enhance your credit score. Options such as FHA, VA, and USDA financing provide accessible pathways for those with lower credit ratings. Plus, pre-approval letters can significantly strengthen your position in a competitive market. Being aware of hidden costs associated with home buying ensures that you are fully prepared for the financial commitment ahead.
By taking proactive steps, you can transform your financial situation and open doors to homeownership. The journey to homeownership is not just about securing a mortgage; it’s about laying a solid foundation for your financial future. Embrace the process, seek guidance when needed, and remember that with determination and the right resources, a successful home purchase is within reach.
Frequently Asked Questions
How can I assess my credit score and financial health before selling my home?
Start by obtaining your credit report from major bureaus like Equifax, Experian, and TransUnion to understand your current rating. Review your income, expenses, and debts, and calculate your debt-to-income (DTI) ratio, which should ideally be below 36% for most mortgage options.
What is the average credit score in California?
The average credit score in California is approximately 721, which is considered a favorable standard to aim for.
What should I do if my credit score is below 620?
If your score is below 620, focus on improving it by paying down existing debts and ensuring timely bill payments. Maintaining a low credit utilization ratio and keeping older accounts active can also help enhance your rating.
What financial documents should I gather when preparing to sell my home?
You should prepare essential financial documents such as pay stubs, tax returns, and bank statements to provide lenders with a clear picture of your financial situation.
What mortgage options are available for individuals with bad credit?
FHA financing is available for borrowers with scores as low as 500 with a 10% down payment, or 3.5% if the score is 580 or higher. VA financing has no minimum score requirement and offers no down payment for veterans and active-duty service members. USDA financing is available for low to moderate-income households in rural areas, and subprime mortgages are offered by some lenders for those with lower credit scores, though they may come with higher interest rates.
How can cooperative financial institutions help borrowers with bad credit?
Cooperative financial institutions and community lenders often have more flexible lending standards compared to larger banks, providing tailored solutions that better fit the unique financial situations of borrowers with lower credit ratings.
List of Sources
- Assess Your Credit Score and Financial Health
- Average Credit Score Statistics 2026 (https://wallethub.com/edu/cs/average-credit-scores/25578)
- California Mortgage Rates Reach 7% | Mbanc (https://mbanc.com/california-mortgage-rates-7-percent)
- California First-Time Homebuyer Guide 2026 | New American Funding (https://newamericanfunding.com/learning-center/guides/california-first-time-homebuyer-guide)
- What Is the Average Credit Score in the US? (https://experian.com/blogs/ask-experian/what-is-the-average-credit-score-in-the-u-s)
- Want to buy a house before the end of 2026? Follow these crucial steps. (https://finance.yahoo.com/personal-finance/mortgages/article/want-to-buy-a-house-in-2026-162052866.html)
- Explore Mortgage Options for Bad Credit
- Best mortgage lenders for bad credit in September 2026 (https://cnbc.com/select/best-mortgage-lenders-bad-credit-score)
- California Mortgage Lender | Fast Approvals & Competitive Rates (https://trussfinancialgroup.com/california-mortgage-lender)
- FHA Loan Requirements for 2026 (https://lower.com/mortgages/fha-loan/how-to-qualify-for-an-fha-loan)
- Best mortgage lenders for bad credit in September 2026 (https://finance.yahoo.com/personal-finance/mortgages/article/best-mortgage-lenders-for-bad-credit-215040123.html)
- FHA Loans in California: The Complete 2026 Guide for Buyers (https://amerisave.com/learn/fha-loans-in-california-the-complete-guide-for-buyers)
- Obtain Pre-Approval for Your Mortgage
- California ‘Dream For All’ 2026 Open Through March 16 for First-Time Home Buyers (https://themortgagereports.com/112152/california-first-time-home-buyers-dream-for-all-loan)
- How the Mortgage Process Works in California (2026) - JVM Lending (https://jvmlending.com/blog/how-does-the-mortgage-process-work-for-homebuyers-in-california)
- How to Get Approved for a Mortgage in CA - Potempa Team at CrossCountry Mortgage (https://potempateam.com/how-to-get-approved-for-a-mortgage-in-ca)
- Buying a House in 2026: 10 Steps First Time Buyers Need to Know < GoPrime Mortgage (https://goprime.com/blog/buying-a-house-in-2026-10-steps-first-time-buyers-need-to-know)
- Mortgage Approval Statistics 2026 (https://worldmetrics.org/mortgage-approval-statistics)
- Improve Your Credit Score Before Applying
- How To Improve Your Credit Score For A Mortgage | Bankrate (https://bankrate.com/mortgages/improve-credit-before-mortgage)
- On-time debt payments aren't a magic fix for your credit score, experts say. Here's why (https://nbcphiladelphia.com/news/business/money-report/on-time-debt-payments-arent-a-magic-fix-for-your-credit-score-experts-say-heres-why/4200747)
- 26 Tips to Improve Credit in 2026 (https://experian.com/blogs/ask-experian/ways-to-improve-credit)
- 5 Proven Ways to Improve Your Credit Score Before Applying for a Mortgage (2026 Guide) (https://flfcu.org/more/community/flfcu-blog/blog/2026/04/03/5-proven-ways-to-improve-your-credit-score-before-applying-for-a-mortgage-(2026-guide))
- How Payment History Impacts Your Credit Score | myFICO (https://myfico.com/credit-education/credit-scores/payment-history)
- Budget for Additional Home Buying Costs
- Closing Costs in California: Your 2026 Home Buyer's Guide to Fees, Taxes, and What You Actually Pay (https://amerisave.com/learn/closing-costs-in-california-your-home-buyers-guide-to-fees-taxes-and-what-you-actually-pay)
- How much are closing costs for a home buyer, and who usually? (https://fastexpert.com/advice/how-much-are-closing-costs-for-a-home-buyer-and-who-us-9950)
- How Much Does a Home Inspection Cost in 2026? Complete Pricing Guide (https://inspectordata.com/blog/home-inspection-cost.html)
- How Much Does a Home Inspection Cost? 2026 Average Is $344 (https://houwzer.com/blog/how-much-does-a-home-inspection-cost-everything-you-need-to-know)
- The complete cost of buying and selling a home in 2026: Fees most people don't expect (https://sacbee.com/news/business/article315234670.html)



