Calculate the Income Needed for a $1 Million Mortgage in 4 Steps
Introduction
Navigating the intricacies of securing a $1 million mortgage can feel overwhelming for many buyers. This guide will clarify the essential steps and considerations for determining the income required for a significant loan, focusing on critical metrics such as debt-to-income ratios and credit scores. With so many factors at play, how can you be sure you meet the criteria to qualify for your dream home?
Understand Mortgage Income Requirements
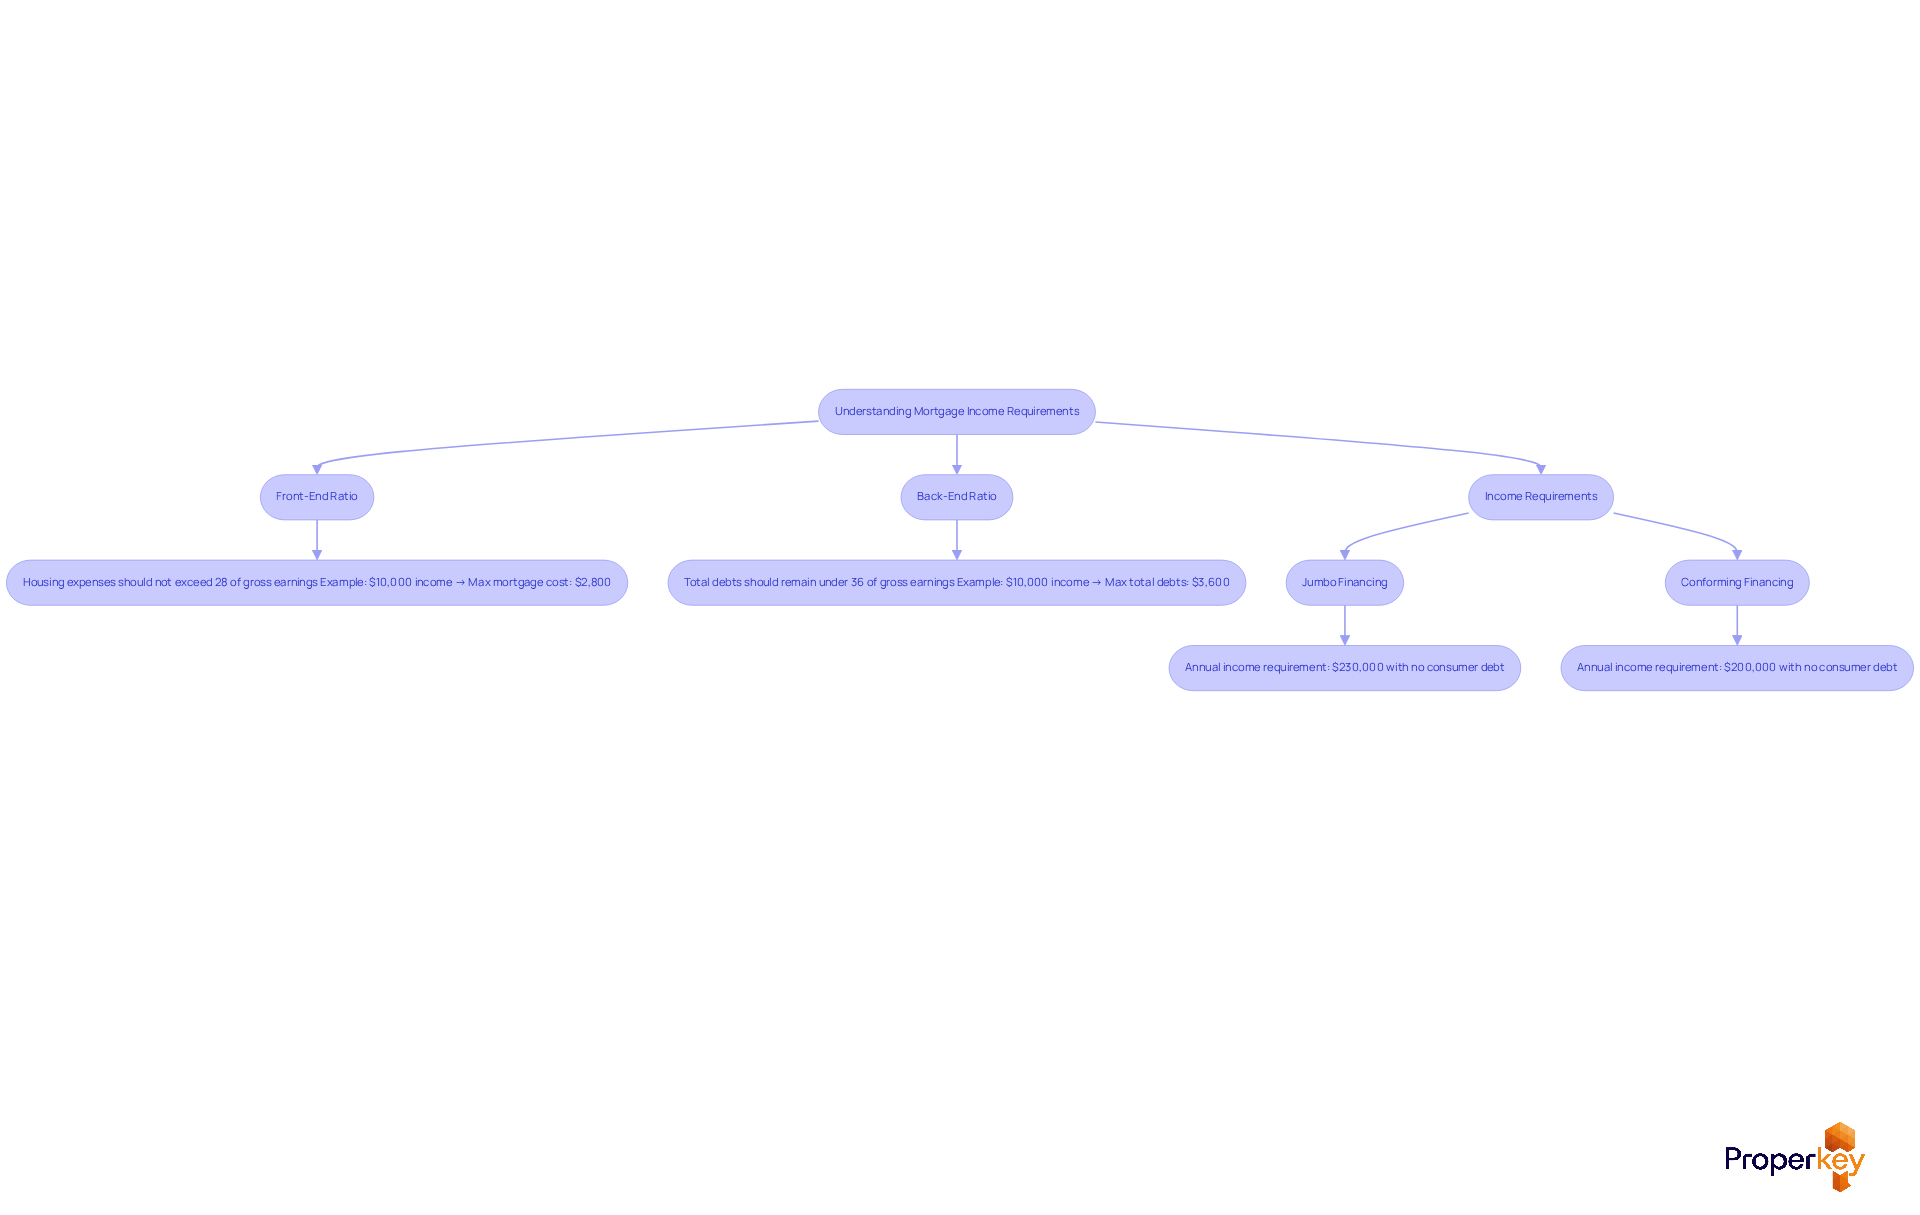
Navigating the financial landscape can be daunting for many home sellers, especially when it comes to understanding loan qualifications. To qualify for a $1 million loan, it's essential to understand the income needed for a 1 million mortgage as per the financial criteria set by lenders. They typically evaluate two key metrics: the front-end ratio and the back-end ratio. The front-end ratio indicates that your housing expenses - including loan installments, property taxes, and insurance - should not exceed 28% of your gross earnings. Conversely, the back-end ratio, which encompasses all recurring debts, should ideally remain under 36%.
For instance, if your gross earnings are $10,000, your maximum allowable mortgage cost would be $2,800 (28% of $10,000). Additionally, your total monthly debt obligations should not surpass $3,600 (36% of $10,000).
In 2026, the income needed for a 1 million mortgage will depend on the type of financing you choose. If you're seeking jumbo financing, your annual earnings should be around $230,000 with no consumer debt obligations. On the other hand, if you can secure conforming financing, the requirement drops to about $200,000. Factors such as down payment size, credit score, and location also significantly influence these requirements.
For example, a borrower needing jumbo financing for a $1 million home with a 10% down payment at a 6.5% interest rate would require an income needed for a 1 million mortgage of approximately $305,226, before considering other debts. Understanding these ratios and requirements is key to knowing the income needed for 1 million mortgage qualification in states like California, Idaho, or Nevada.
Additionally, Vana offers a Free Loan Analysis to help you explore your refinancing options. By providing a copy of your most recent loan statement, you can uncover potential savings. If you're already in the process of securing a loan, sharing your written loan estimate can lead to competitive offers. For those looking to purchase, Vana can qualify you in just a few minutes and provide your Loan Qualification Letter immediately, ensuring a streamlined process as you navigate the complexities of financing a high-value home.
Identify Key Factors Affecting Income Calculation
Navigating the complexities of securing a $1 million mortgage in California requires a clear understanding of several key factors:
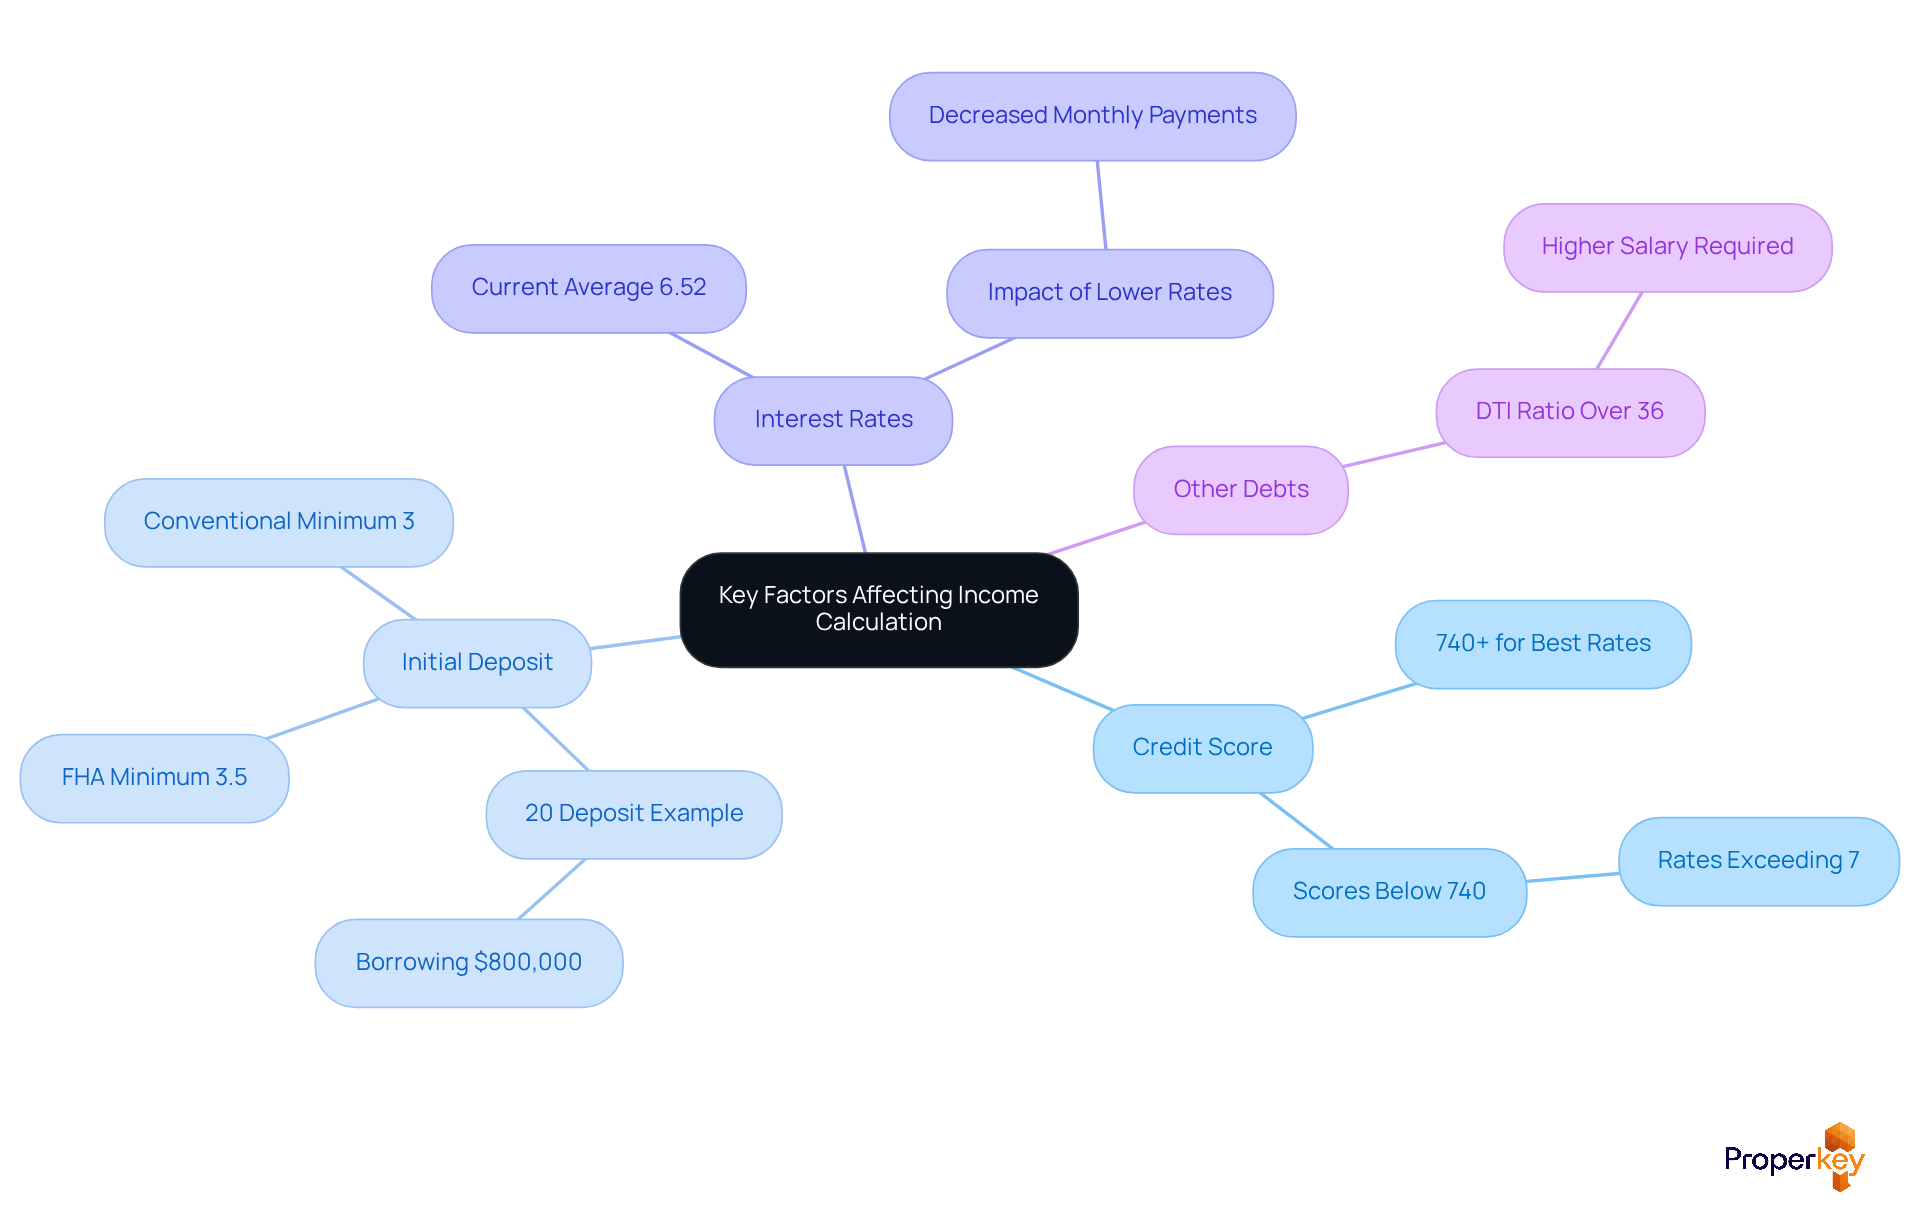
- Credit Score: An elevated credit score can greatly decrease your interest rate, lowering your monthly expenses. Lenders typically prefer a score of 740 or higher to secure the best rates. For instance, a borrower with a score of 740 may see rates around 6.5%, while those with lower scores could face rates exceeding 7%.
- Initial Deposit: The size of your initial deposit directly influences your mortgage amount. A larger down payment decreases the loan amount, which can lower your monthly payments and, consequently, the income needed. For example, a 20% deposit on a $1 million house would mean borrowing just $800,000, significantly impacting your monthly obligations. FHA loans require a minimum down payment of 3.5%, while conventional loans may need as little as 3%.
- Interest Rates: Current market interest rates significantly affect your monthly payment. As of August 2026, the average rate for a 30-year fixed loan is approximately 6.52%. A lower interest rate results in smaller payments, thus decreasing the income required to qualify for the loan. Competitive rates are often available for FHA and VA loans, which can further benefit eligible borrowers.
- Other Debts: High monthly debts can make it tougher to qualify for your mortgage. Lenders assess your total debt obligations, including car loans and student loans. If your total monthly debt payments exceed 36% of your gross income, lenders might require a higher salary to approve your home loan application.
Understanding these factors, along with the benefits of various loan types like FHA and VA loans, helps you assess your financial situation. This way, you can determine the income needed for a $1 million mortgage in California. Furthermore, using Loanvana's financing tool allows you to apply once and compare hundreds of loan options side-by-side from various lenders, making the process of finding the right financing for your luxury home even more efficient.
Calculate Your Required Income for a $1 Million Mortgage
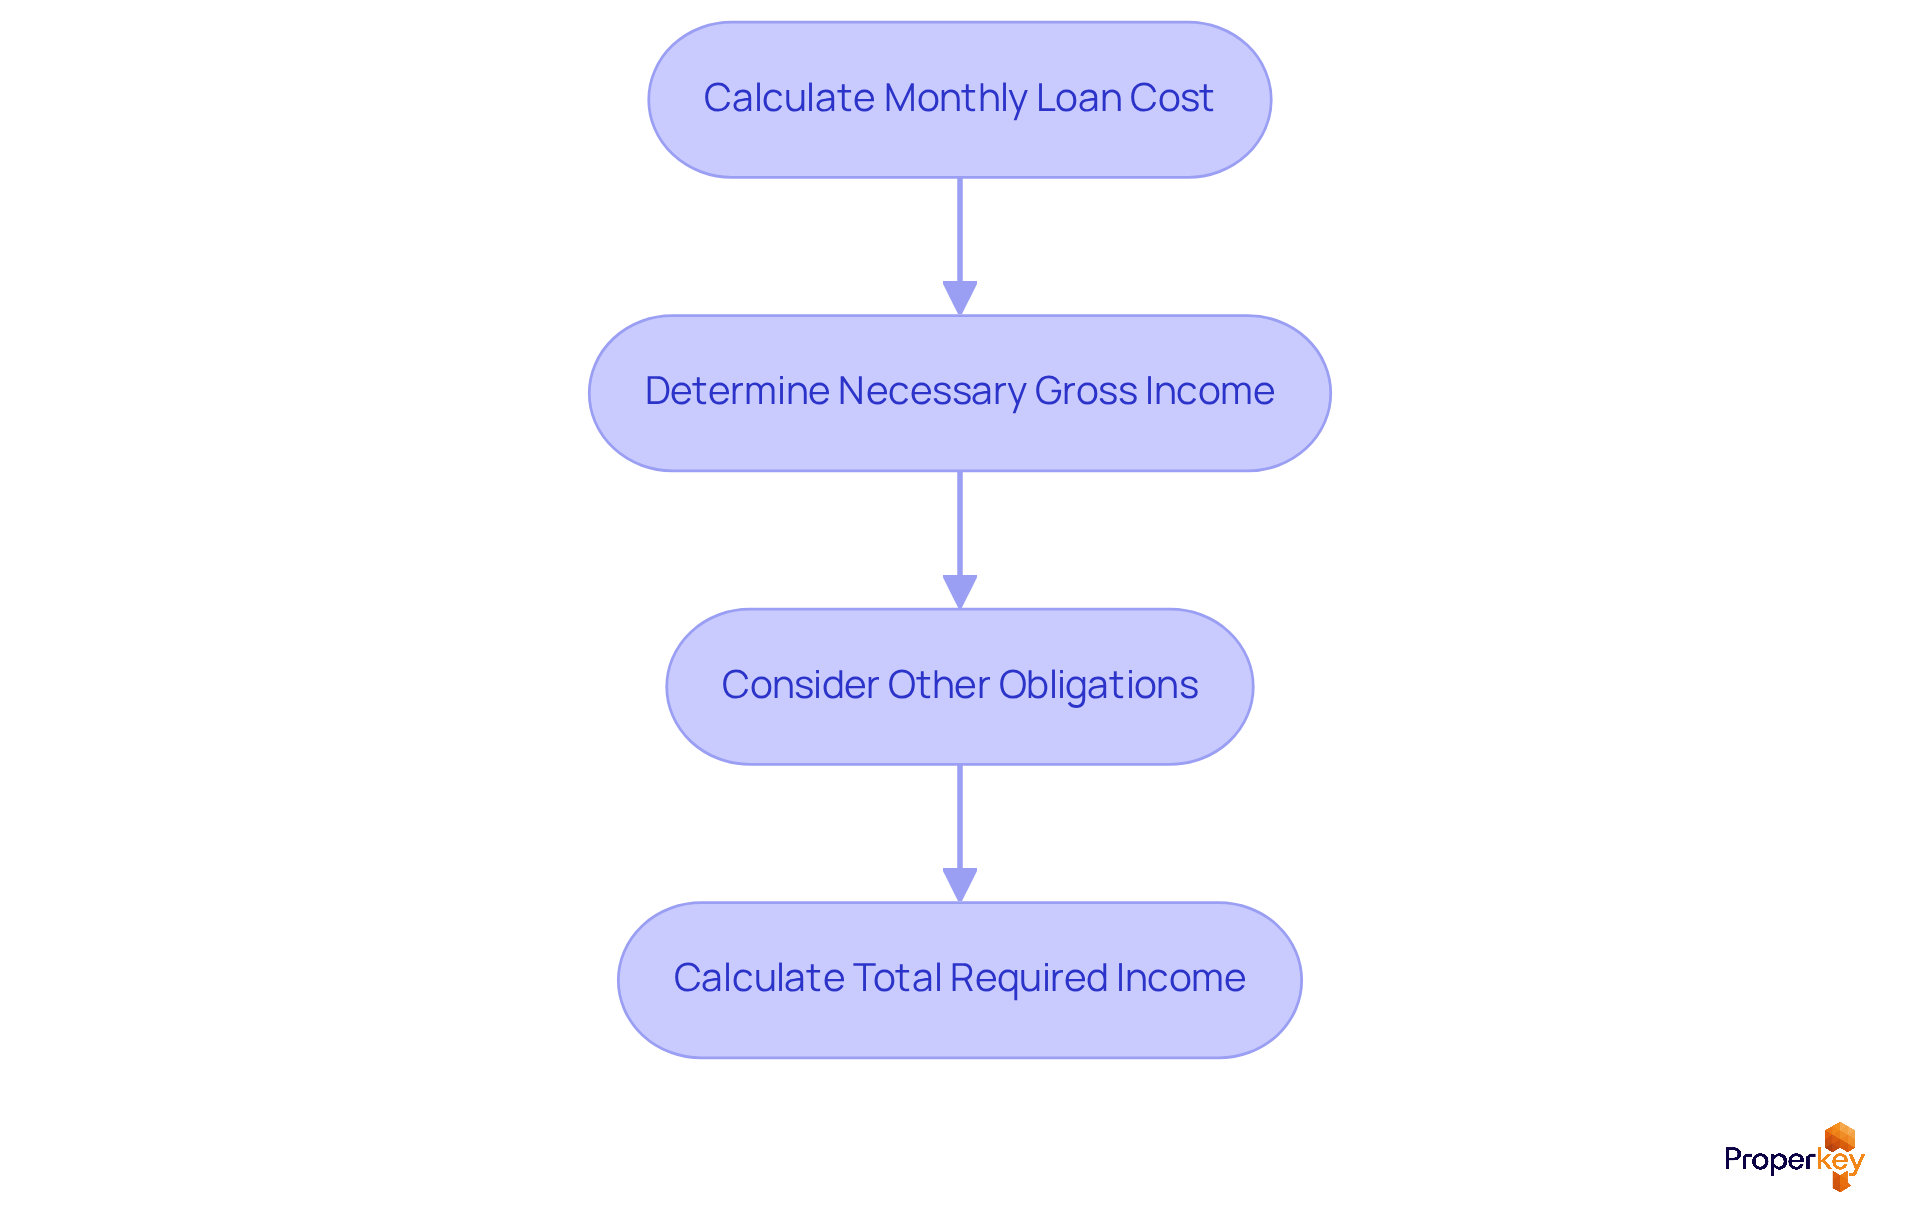
Navigating the intricacies of mortgage calculations can feel overwhelming, especially for first-time home sellers. To calculate the income needed for a $1 million mortgage, follow these steps:
- Calculate Your Monthly Loan Cost: Start by using a loan calculator to get a rough idea of your monthly costs based on the loan amount, interest rate, and how long you plan to pay it off. For instance, a $1 million loan at a 6.5% interest rate over 30 years, assuming a 20% down payment, results in a cost of approximately $5,057 toward principal and interest.
- Determine Your Necessary Gross Income: Apply the 28% guideline by dividing your recurring housing cost by 0.28. For example: $5,057 / 0.28 = $18,063. This is the total income needed for a $1 million mortgage to comfortably afford the loan cost, based on gross earnings.
- Consider Other Obligations: Don’t forget to factor in any other monthly debts you have; these will impact your overall mortgage costs and financial picture. For instance, if you have $1,000 in additional debts, your overall expense each month would be $6,057.
- Calculate Total Required Income: Using the 36% rule, divide your total debt obligations by 0.36. For example: $6,057 / 0.36 = $16,842. This is the minimum gross income needed for a $1 million mortgage per month to qualify for the loan.
Furthermore, if your down payment is below 20%, you might have to cover private insurance for loans, which can raise your regular expenses. Also, consider the varying costs of homeowners insurance and property taxes, as these can significantly affect your overall monthly payment.
To simplify your financing journey, leverage Loanvana's innovative tool that lets you apply just once and compare a multitude of loan options from various lenders side-by-side. This tool can assist you in each step of the loan calculation process, helping you find the best rates and terms available for a $1 million loan in California, Idaho, or Nevada. With the right tools and knowledge, you can confidently approach your mortgage calculations and secure the financing you need to achieve your homeownership goals.
Utilize Tools and Resources for Mortgage Calculations
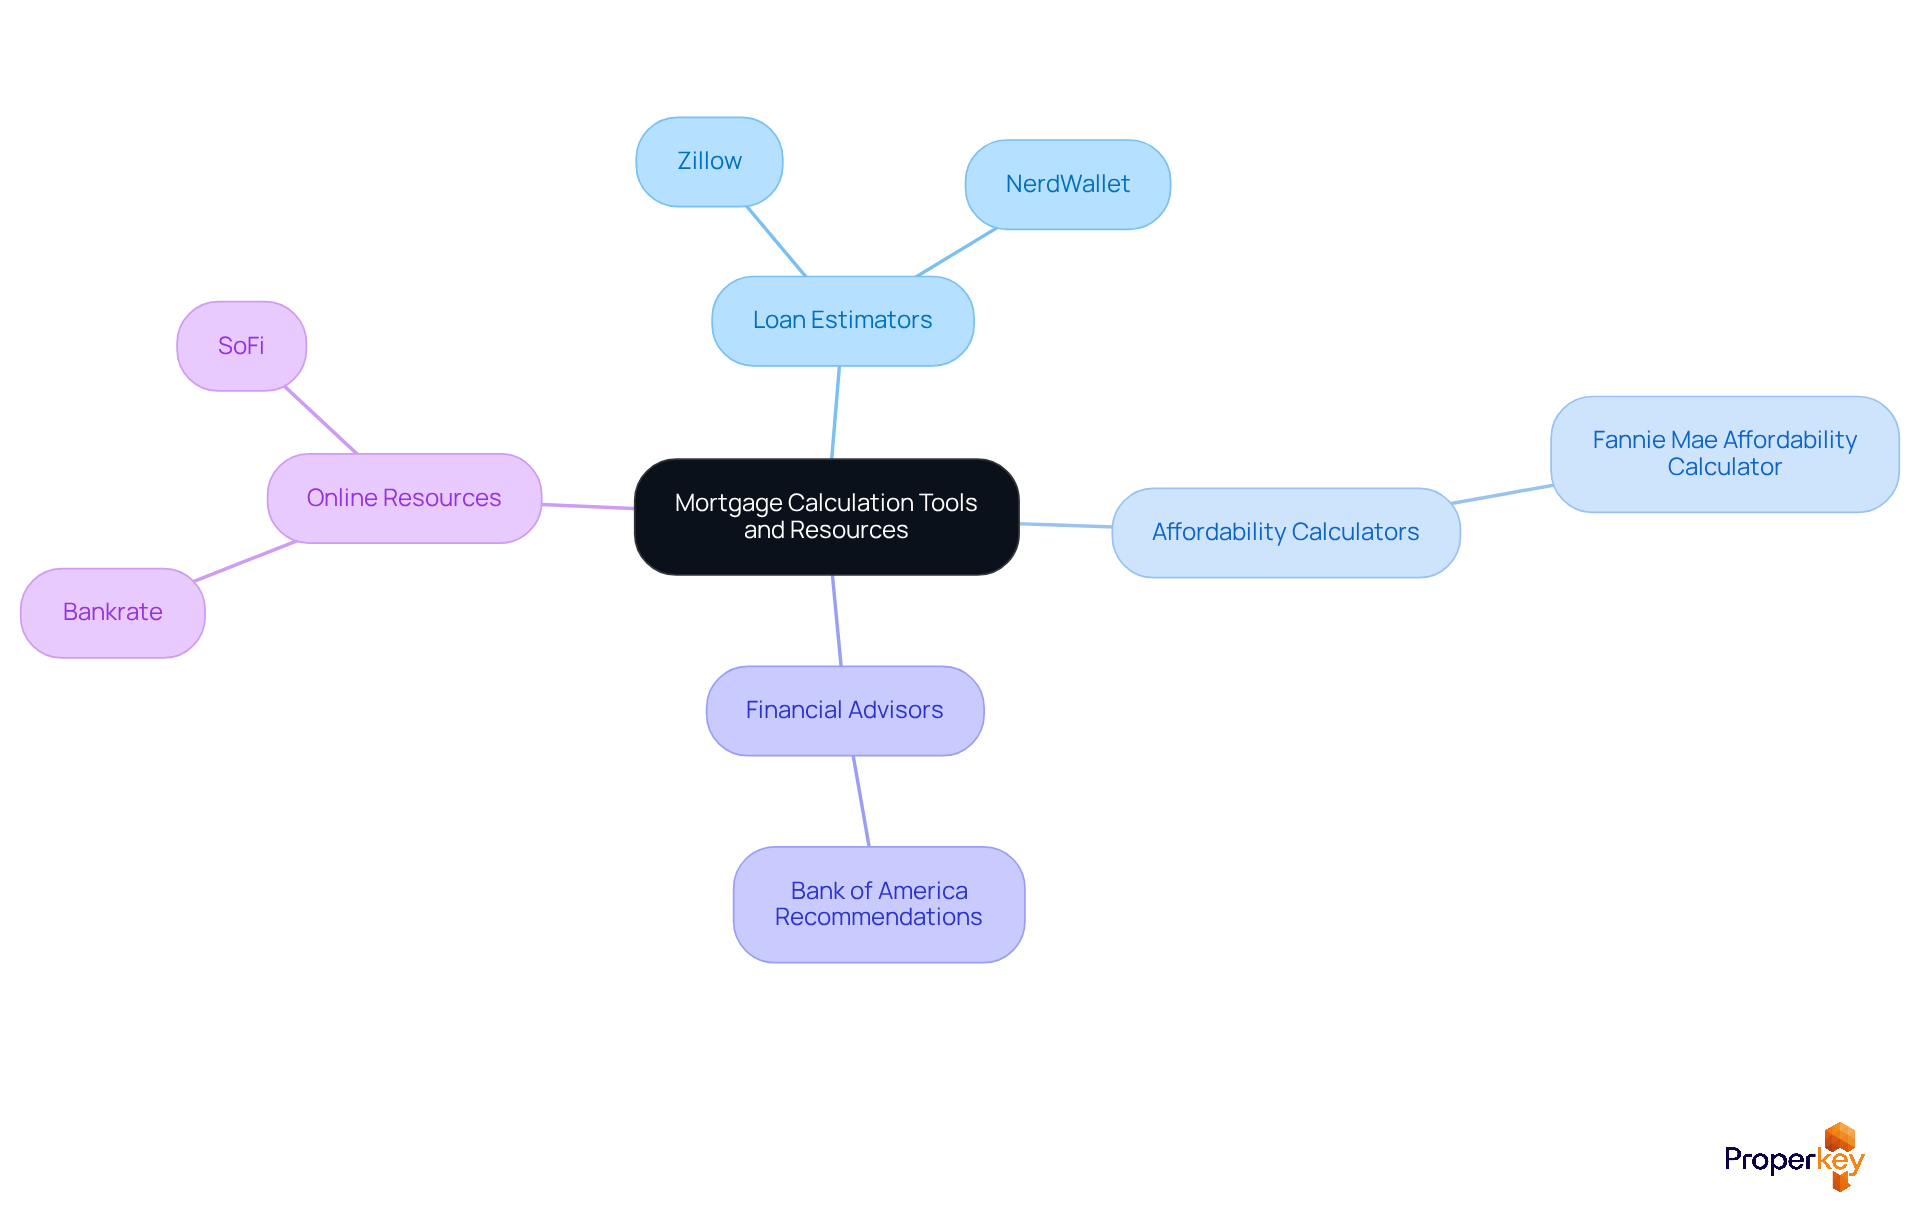
Navigating the complexities of mortgage calculations can be daunting for many home sellers. To effectively calculate the income needed for a $1 million mortgage, consider leveraging the following tools and resources:
- Loan estimators such as Zillow and NerdWallet provide platforms with loan calculators that assist in estimating the income needed for a $1 million mortgage and recurring costs. For example, with an average interest rate of 7% for a 30-year fixed-rate mortgage, your payment each month could be around $6,653, excluding taxes and insurance.
- Affordability Calculators: Tools like the Fannie Mae Affordability Calculator offer insights into how much home you can afford based on your earnings and existing debts, customized for the California, Idaho, and Nevada markets. It’s essential to ensure that your total monthly housing costs do not exceed 30% of your gross monthly income.
- Financial Advisors: Talking to a financial advisor can give you tailored insights that make navigating your mortgage easier. As Bank of America recommends, a down payment of at least 5% of the purchase price is advisable to secure better loan terms.
- Online Resources: Websites such as Bankrate and SoFi offer articles and guides that clarify loan requirements and calculations in detail, specifically addressing the needs of homebuyers in these states. Closing costs typically range from 2% to 5% of the loan amount, which is another crucial factor to consider in your overall budget.
Without proper guidance, you risk miscalculating your financial readiness, potentially jeopardizing your home purchase. Ensure you’re equipped with the right tools to confidently approach your mortgage application and secure your dream home.
Conclusion
Navigating the complexities of securing a $1 million mortgage can be daunting for many prospective homebuyers. Understanding the income required is essential. Key factors influencing the income needed include:
- Credit scores
- Down payment sizes
- Interest rates
- Existing debt obligations
Each of these elements plays a significant role in determining the overall financial picture and the monthly payments associated with a mortgage.
Utilizing tools like loan calculators and affordability assessments can further simplify this process. These resources allow potential buyers to make informed decisions tailored to their unique financial situations.
When you’re well-informed and have the right resources, you can tackle the mortgage process with confidence. By understanding the intricacies of income requirements and leveraging available tools, you can transform the mortgage process from a challenge into an opportunity for homeownership.
Frequently Asked Questions
What are the key metrics lenders evaluate for mortgage qualification?
Lenders typically evaluate two key metrics: the front-end ratio and the back-end ratio. The front-end ratio indicates that housing expenses should not exceed 28% of gross earnings, while the back-end ratio, which includes all recurring debts, should ideally remain under 36%.
How is the maximum allowable mortgage cost calculated?
The maximum allowable mortgage cost is calculated by taking 28% of your gross earnings. For example, if your gross earnings are $10,000, your maximum allowable mortgage cost would be $2,800.
What is the income requirement for a $1 million mortgage in 2026?
In 2026, the income needed for a $1 million mortgage will depend on the type of financing. For jumbo financing, the annual earnings should be around $230,000 with no consumer debt obligations. For conforming financing, the requirement drops to about $200,000.
How does the down payment size and credit score affect mortgage qualification?
The size of the down payment and the borrower's credit score significantly influence the income requirements for mortgage qualification. A larger down payment or a higher credit score may lower the income needed for qualification.
Can you provide an example of income needed for a jumbo financing mortgage?
For a borrower needing jumbo financing for a $1 million home with a 10% down payment at a 6.5% interest rate, the income needed would be approximately $305,226, before considering other debts.
What services does Vana offer to assist with mortgage qualification?
Vana offers a Free Loan Analysis to help explore refinancing options and can qualify you in just a few minutes, providing a Loan Qualification Letter immediately to streamline the process of securing a loan for a high-value home.
List of Sources
- Understand Mortgage Income Requirements
- Why the debt-to-income ratio matters (https://sffirecu.org/learning/why-debt-to-income-ratio-matters)
- How Much Income Do You Need To Buy A $1 Million Dollar Home - JVM Lending (https://jvmlending.com/blog/how-much-income-do-you-need-to-buy-a-1-million-dollar-home)
- How much income & down payment for a $1 million mortgage? (https://rate.com/mortgage/resource/how-can-i-afford-a-million-dollar-house)
- What Income Do You Need To Afford A $1 Million House? (https://lower.com/mortgages/what-income-do-you-need-to-afford-a-1-million-house)
- Identify Key Factors Affecting Income Calculation
- Income Requirements To Qualify For A Mortgage | Bankrate (https://bankrate.com/mortgages/proving-income-to-land-a-mortgage)
- Mortgage Rates Forecast For 2026: Experts Predict Whether Interest Rates Will Drop (https://forbes.com/advisor/mortgages/mortgage-interest-rates-forecast)
- Current California Mortgage and Refinance Rates | Bankrate (https://bankrate.com/mortgages/mortgage-rates/california)
- Average Mortgage Rates by Credit Score (https://experian.com/blogs/ask-experian/average-mortgage-rates-by-credit-score)
- Compare Today's Mortgage Interest Rates - NerdWallet (https://nerdwallet.com/mortgages/mortgage-rates)
- Calculate Your Required Income for a $1 Million Mortgage
- What Income Do You Need To Afford A $1 Million House? (https://lower.com/mortgages/what-income-do-you-need-to-afford-a-1-million-house)
- Here's the salary you need to afford a $1 million home (https://finance.yahoo.com/personal-finance/mortgages/article/salary-to-afford-1-milion-dollar-home-174754545.html)
- How Much Is the Payment On a $1 Million Mortgage in 2026? Complete Cost Breakdown (https://amerisave.com/learn/how-much-is-the-payment-on-a-million-mortgage-in-complete-cost-breakdown)
- How much income & down payment for a $1 million mortgage? (https://rate.com/mortgage/resource/how-can-i-afford-a-million-dollar-house)
- Utilize Tools and Resources for Mortgage Calculations
- Mortgage Calculator (https://mortgagecalculator.org)
- Mortgage Calculator | Fannie Mae (https://yourhome.fanniemae.com/calculators-tools/mortgage-calculator)
- Mortgage Calculator (https://zillow.com/mortgage-calculator)
- Mortgage Calculator from Bank of America (https://bankofamerica.com/mortgage/mortgage-calculator)
- Affordability Calculator - How Much House Can I Afford? | Zillow (https://zillow.com/mortgage-calculator/house-affordability)