Calculate Your Monthly Payment: How Much is a 300k Mortgage?

Introduction
Navigating the complexities of mortgage payments is crucial for anyone stepping into homeownership, particularly with substantial loans like a $300,000 mortgage. This guide breaks down the various components that make up a mortgage payment, equipping readers with the tools to calculate their monthly obligations accurately.
With fluctuating interest rates and local tax regulations, how can potential homeowners make informed financial decisions? Understanding these factors not only demystifies the mortgage process but also empowers buyers to navigate their financial futures with confidence, avoiding costly mistakes.
Understand Mortgage Payments and Their Components
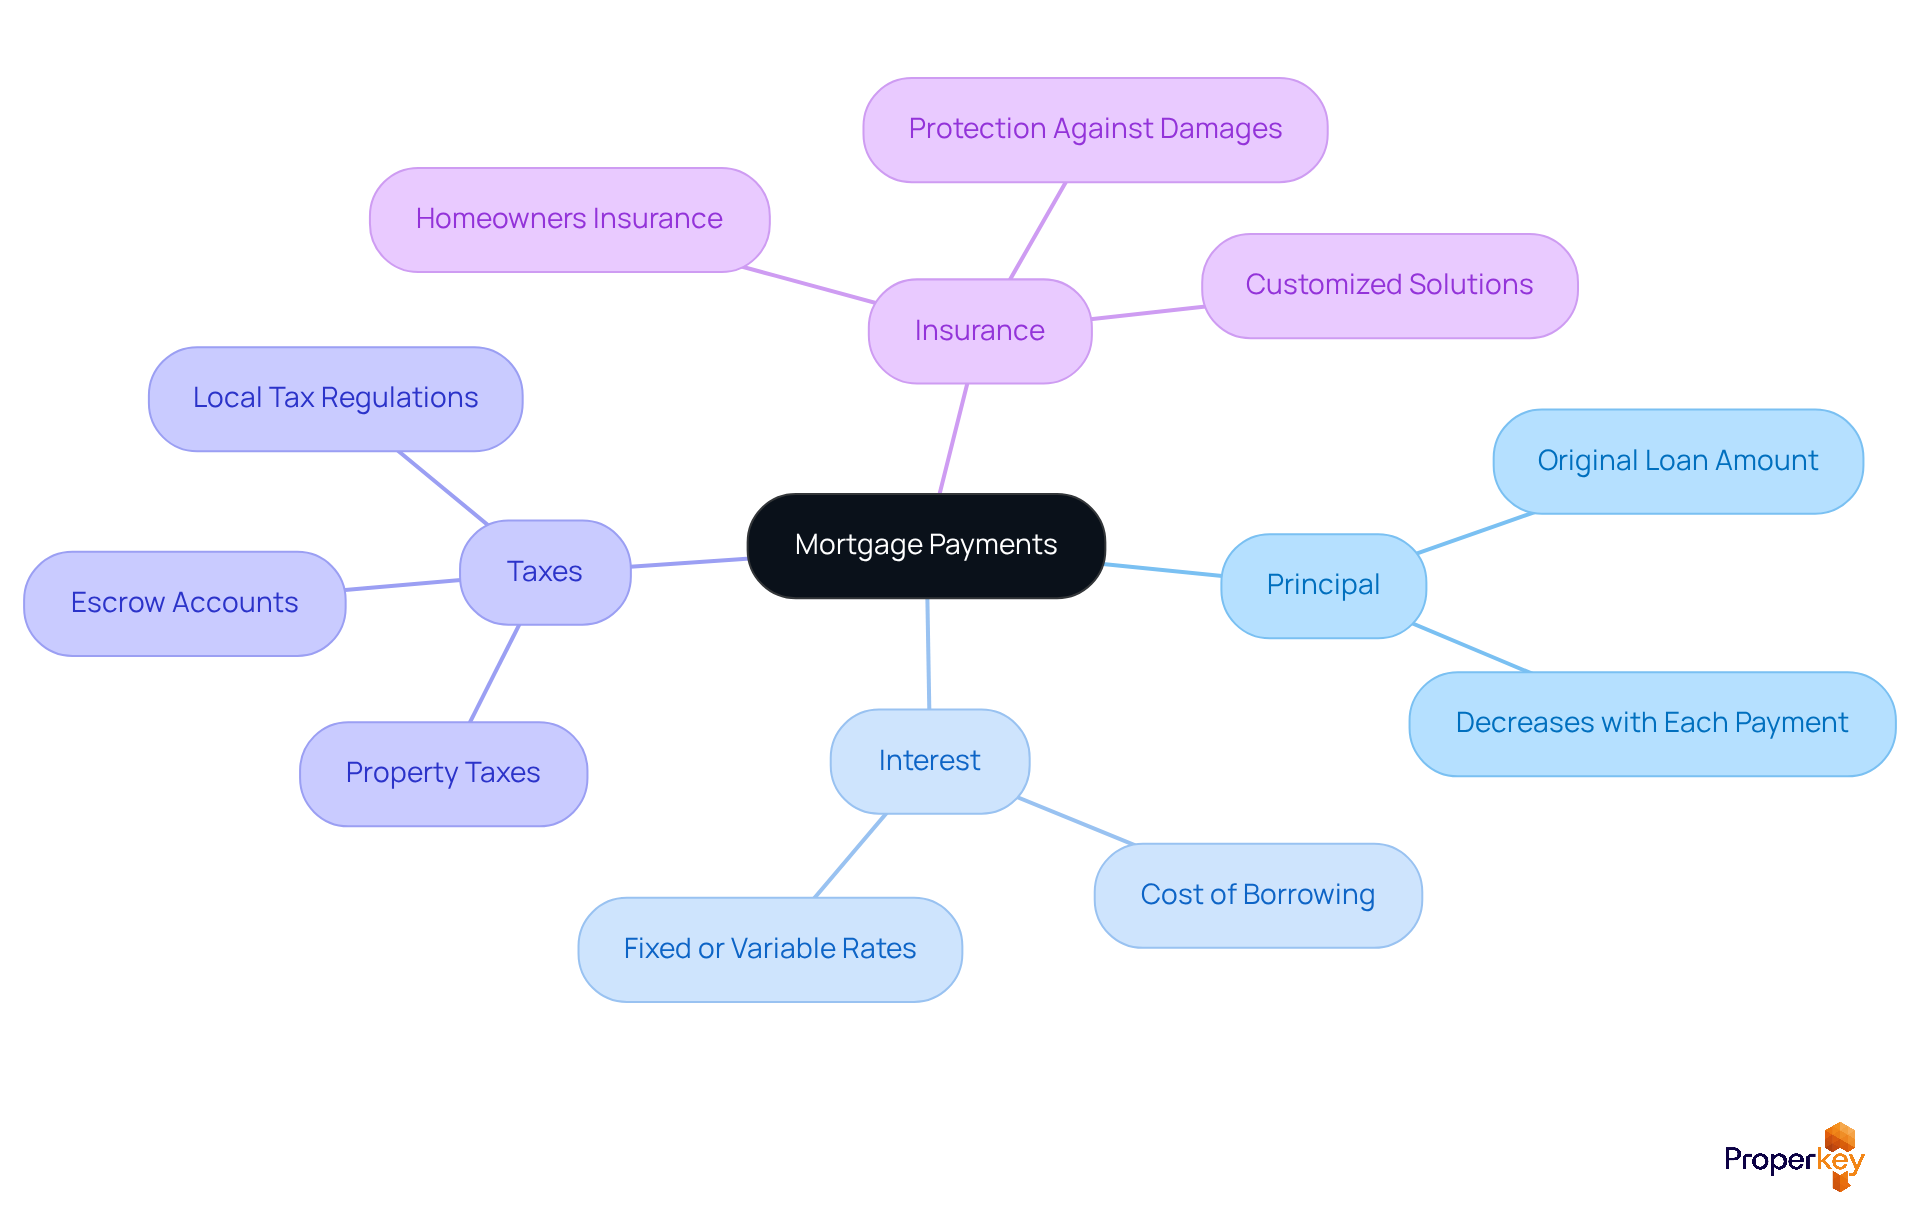
Are you aware of the hidden costs that come with your mortgage payment? A mortgage payment typically consists of four main components, commonly referred to as PITI:
- Principal: This is the original loan amount borrowed from the lender. Each regular installment decreases this balance, aiding in the eventual ownership of the home.
- Interest: This represents the cost of borrowing the principal amount, expressed as a percentage. Interest charges can be fixed or variable, significantly affecting the total expense throughout the duration of the loan.
- Taxes: Property taxes are typically incorporated in your regular installment and are frequently kept in an escrow account until they are due. In California, for example, homeowners encounter elevated property tax rates, which can significantly influence regular expenses. Navigating local tax regulations can be daunting, but understanding them is essential for accurate budgeting.
- Insurance: Homeowners insurance safeguards your property from damages and is also part of your regular charge. This coverage is crucial, especially in areas prone to natural disasters, such as California. Additionally, exploring customized insurance solutions from Properkey can provide tailored coverage options that fit your lifestyle.
Understanding these elements helps you accurately calculate how much is a 300k mortgage per month, allowing you to manage your budget effectively. For instance, in California, the average housing cost is roughly $3,977, which represents about 69% of the median income. Ignoring these elements can lead to unexpected financial strain. Furthermore, potential buyers should be aware of VA loans and USDA financing options that may offer favorable terms and lower costs, making homeownership more accessible. By mastering these components, you can navigate the complexities of homeownership with confidence.
Calculate Monthly Payments Using the Mortgage Formula
Calculating your monthly mortgage payment can seem daunting, but it doesn't have to be. To calculate your monthly mortgage payment for a $300,000 loan, you can use the following formula:
M = P [r(1 + r)^n] / [(1 + r)^n - 1]
Where:
- M = Total monthly mortgage payment
- P = Principal loan amount (e.g., $300,000)
- r = Monthly interest rate (annual rate divided by 12)
- n = Number of payments (loan term in months)
Step-by-Step Calculation:
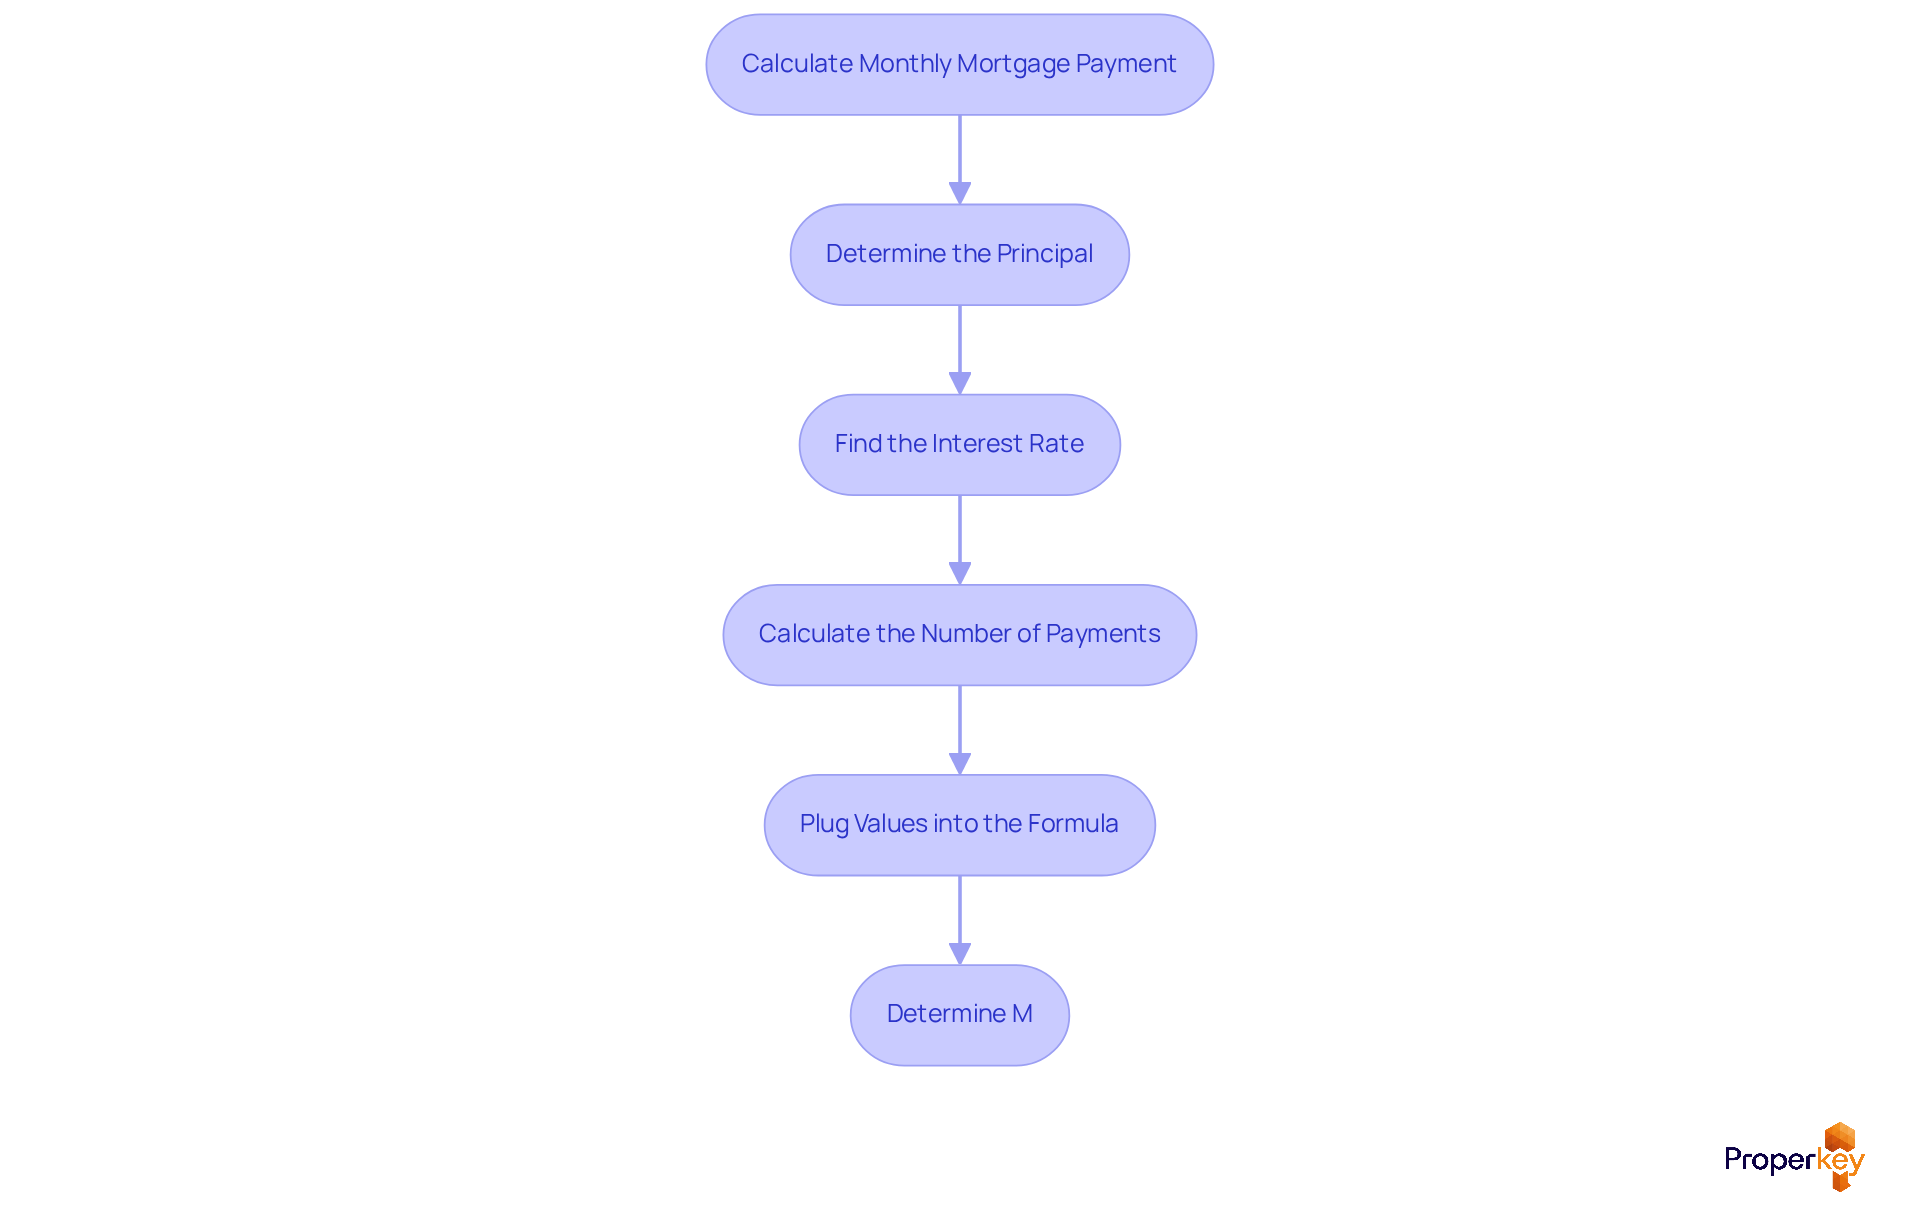
- Determine the Principal: For a $300,000 loan, P = 300,000.
- Find the Interest Rate: If your annual interest rate is 6.71% (the current average for a 30-year fixed-rate loan), then r = 0.0671 / 12 = 0.00559167.
- Calculate the Number of Payments: For a 30-year loan, n = 30 * 12 = 360.
-
Plug Values into the Formula:
- M = 300,000 [0.00559167(1 + 0.00559167)^360] / [(1 + 0.00559167)^360 - 1]
- Determine M: This will provide your recurring charge amount.
Using this formula, you can easily figure out your monthly loan payment based on different loan amounts and interest rates. For instance, with the current average monthly mortgage payment in California being approximately $3,533, knowing how much is a 300k mortgage per month can help you assess your financial readiness for homeownership. This knowledge empowers you to make informed choices that align with your financial goals. Furthermore, examining different loan choices and contrasting costs can lead to significant savings, as many buyers unknowingly overpay for their loans by not exploring all available options. Loanvana offers a financing tool that allows you to apply once and compare hundreds of loan options side-by-side from multiple lenders, ensuring you find the best rates available. Chibuzo Ezeokeke points out that many lenders use the 28/36 rule to help you figure out how much of your income should go toward housing costs. By taking the time to compare options, you can secure a loan that not only fits your budget but also supports your long-term financial success.
Explore Factors Affecting Your Monthly Mortgage Payment
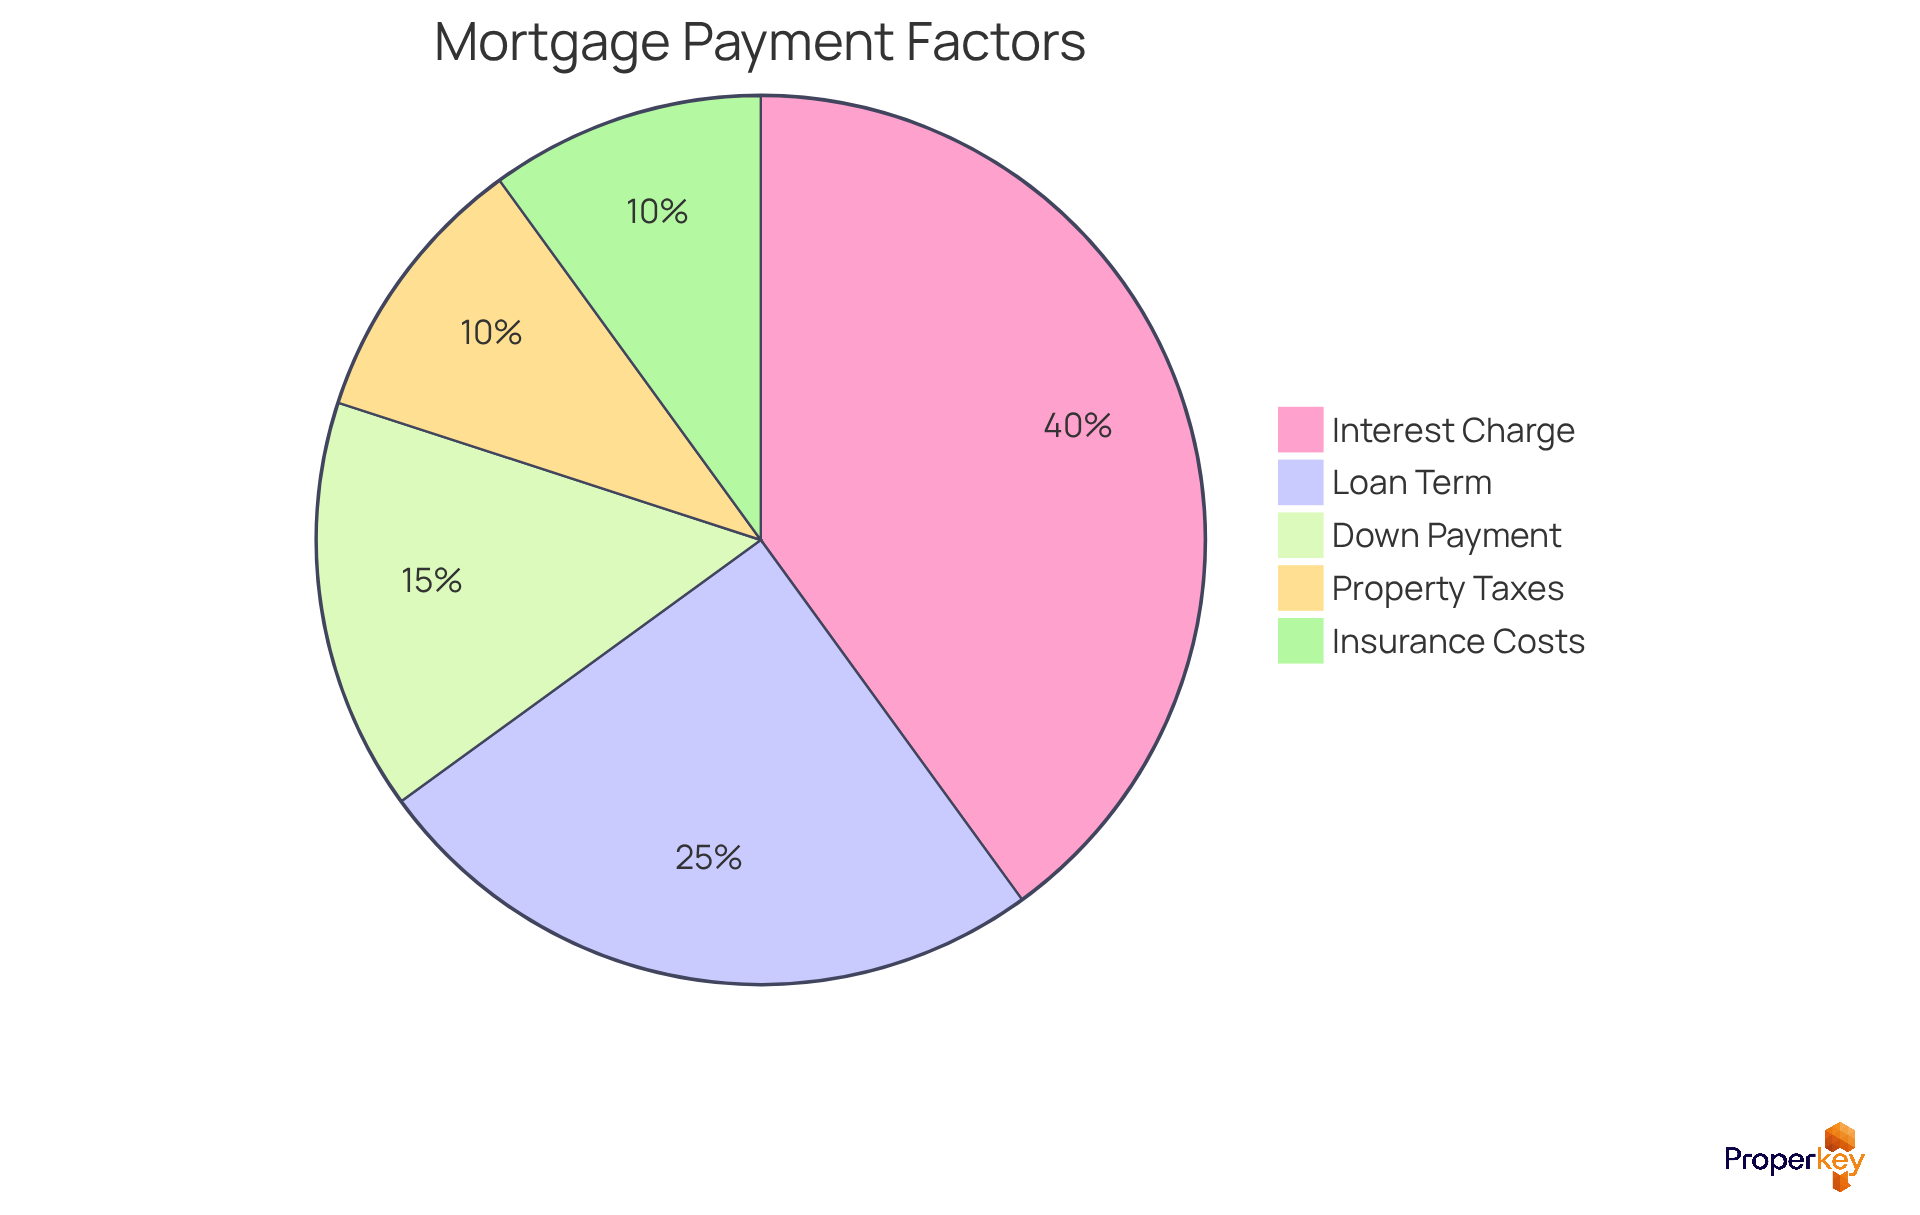
Navigating the complexities of mortgage payments, such as how much is a 300k mortgage per month, can feel overwhelming, especially in competitive markets like California, Idaho, and Nevada. Several factors significantly influence your monthly mortgage payment:
- Interest Charge: When it comes to your monthly expenses, the interest charge plays a pivotal role. With elevated rates resulting in higher costs and climbing above 7%, many buyers are questioning how much is a 300k mortgage per month.
- Loan Term: The duration of your loan influences your regular obligations. When considering how much is a 300k mortgage per month, it's important to note that shorter durations, such as 15 years, generally lead to higher regular costs but reduced total interest expenses compared to longer durations like 30 years, which distribute costs over a more extended period.
- Down Payment: A larger down payment decreases the principal amount financed, which can reduce your regular charge and potentially remove private mortgage insurance (PMI). For example, a 10% deposit on a $300,000 house can greatly reduce recurring expenses, leading to inquiries about how much is a 300k mortgage per month.
- Property Taxes: Property taxes differ significantly by area and can greatly influence your regular costs if included in your escrow. In California, for example, property taxes can be particularly high, impacting overall affordability.
- Insurance Costs: Homeowners insurance rates fluctuate based on coverage levels and property location. In regions with greater risks, like those susceptible to natural disasters, insurance expenses can considerably increase your monthly costs.
Grasping these elements is crucial for managing your home loan effectively. As costs rise, the need for strategic planning becomes more pressing than ever, especially when evaluating how much is a 300k mortgage per month, with increasing loan costs averaging $2,891 for the median-priced residence in California as of October 2023.
Implement Strategies to Lower Your Monthly Mortgage Costs
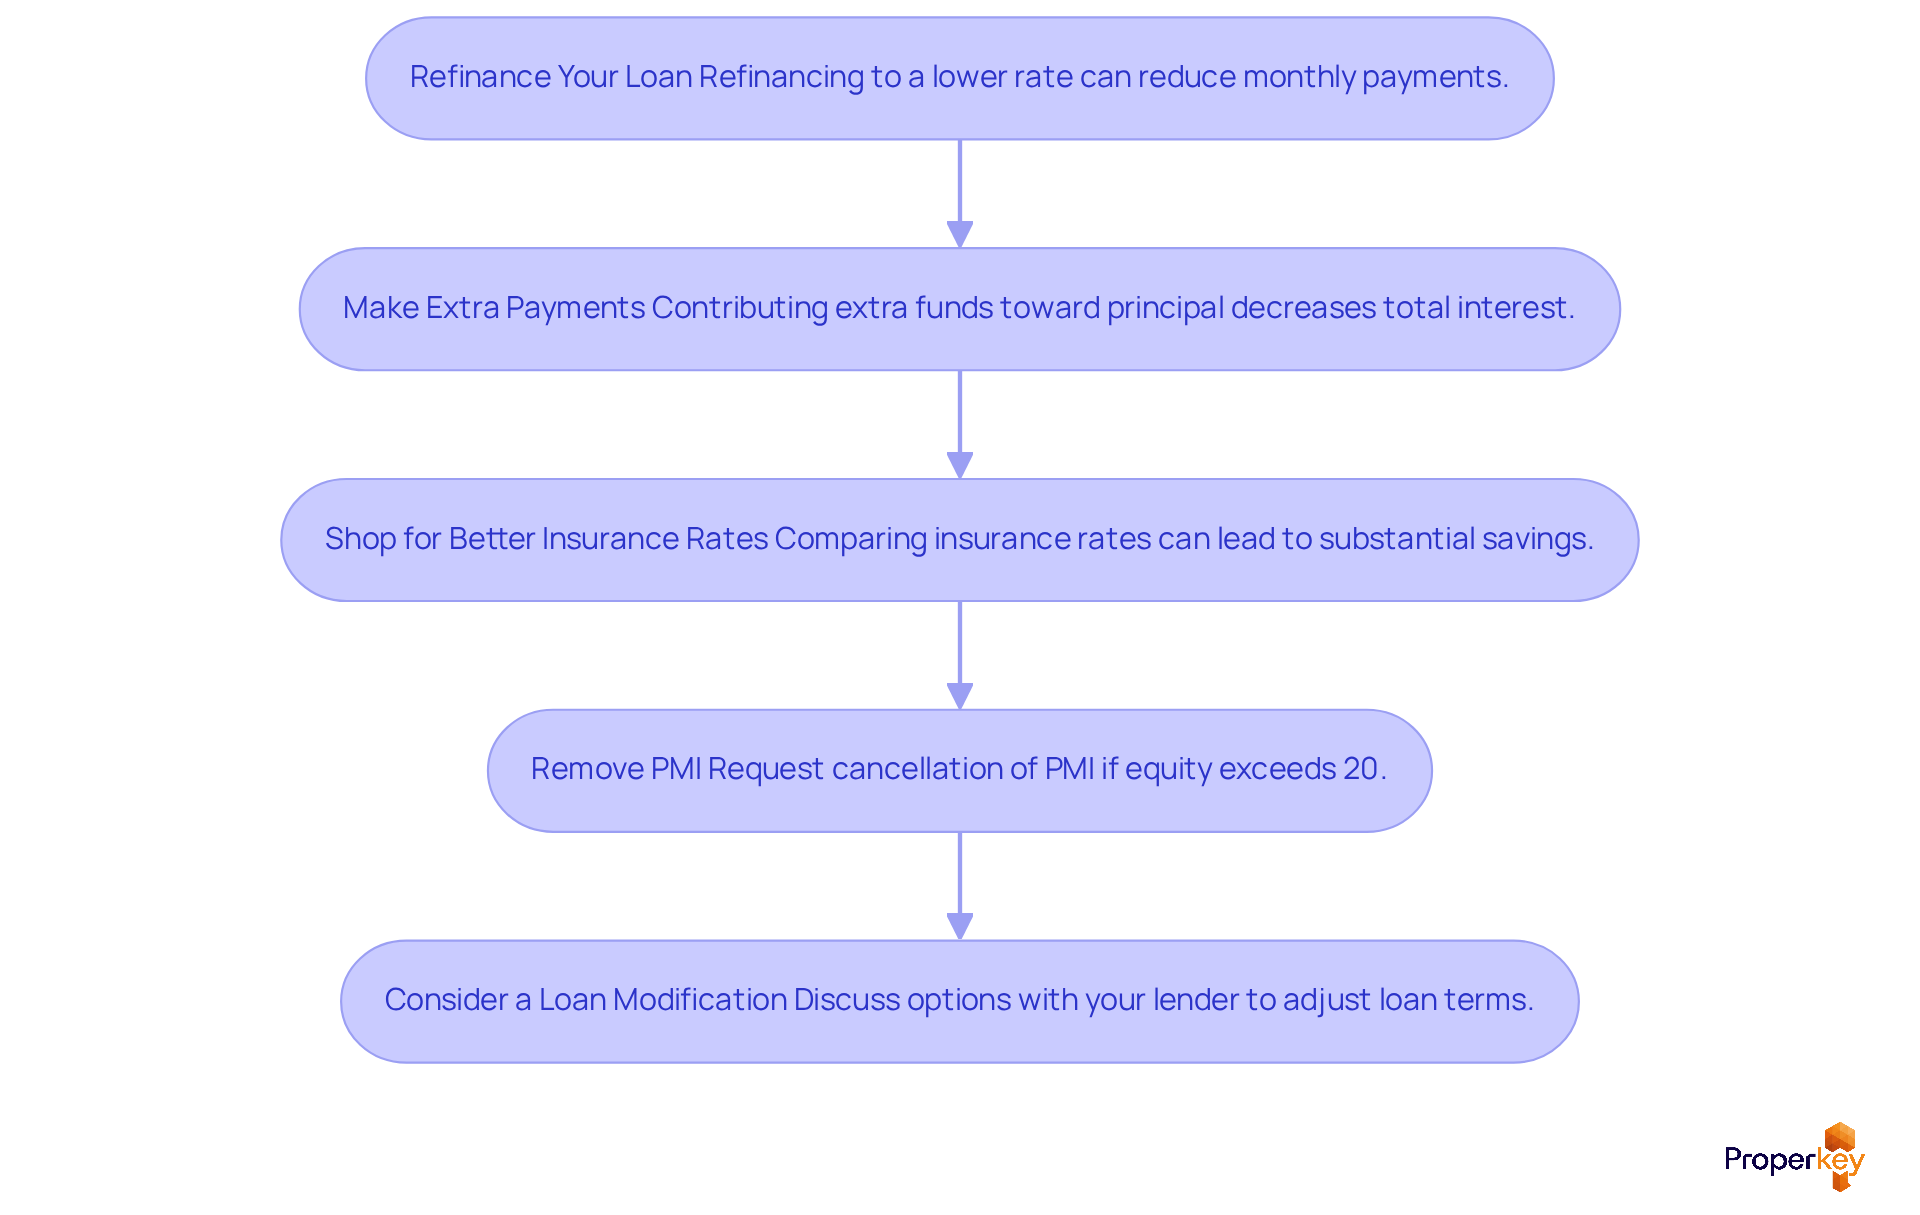
Are you feeling the pressure of rising mortgage costs? You're not alone. To effectively lower your monthly mortgage costs, consider implementing the following strategies:
- Refinance Your Loan: If interest rates have dropped since you obtained your loan, refinancing to a lower rate can significantly reduce your monthly payment. In California, for instance, the average mortgage rate was 6.26% in September 2025, down from higher figures in previous years. This makes refinancing a viable option for many homeowners. With Loanvana's financing tool, you can apply once and compare hundreds of loan options side-by-side from various lenders, ensuring you find the best offers available.
- Make Extra Payments: Contributing additional funds toward your principal can decrease the total interest paid over the life of the loan and shorten the repayment term. In a high-rate environment, this strategy can be a game changer. It helps you build equity faster.
- Shop for Better Insurance Rates: Regularly comparing homeowners insurance rates can lead to substantial savings. Properkey provides customizable home insurance plans with instant quotes, which can assist in reducing your overall expenses.
- Remove PMI: If your equity exceeds 20%, you can request the cancellation of private mortgage insurance (PMI), resulting in significant monthly savings. This is especially relevant for homeowners who have seen their property values increase.
- Consider a Loan Modification: Many homeowners are struggling to keep up with rising mortgage payments. Discussing loan modification options with your lender can help adjust your loan terms to make them more manageable. It can give you the breathing room you need to avoid foreclosure, a worry many homeowners face today.
By adopting these strategies, you can regain control over your finances and enjoy the benefits of homeownership. Imagine a future where your mortgage payment is manageable, allowing you to focus on what truly matters.
Conclusion
Navigating the complexities of mortgage payments can feel overwhelming for many homebuyers, especially when trying to understand how much a $300k mortgage truly costs. By understanding the key components of your mortgage - principal, interest, taxes, and insurance - you can make informed financial decisions that fit your budget and long-term goals. This knowledge not only simplifies the process but also opens doors to better financial opportunities.
Key insights discussed include:
- The importance of calculating monthly payments using the mortgage formula
- Recognizing factors that influence payment amounts
- Implementing strategies to lower costs
From understanding how interest rates and loan terms affect your monthly obligations to exploring options like refinancing and removing private mortgage insurance, each element plays a crucial role in managing your mortgage effectively.
By embracing this knowledge, you’re not just preparing for homeownership; you’re taking control of your financial destiny.
Frequently Asked Questions
What are the main components of a mortgage payment?
A mortgage payment typically consists of four main components known as PITI: Principal, Interest, Taxes, and Insurance.
What does the principal component of a mortgage payment refer to?
The principal is the original loan amount borrowed from the lender. Each regular installment decreases this balance, contributing to the eventual ownership of the home.
How is interest calculated in a mortgage payment?
Interest represents the cost of borrowing the principal amount, expressed as a percentage. It can be either fixed or variable, which significantly affects the total expense over the duration of the loan.
What role do property taxes play in mortgage payments?
Property taxes are typically included in the regular mortgage installment and are often held in an escrow account until they are due. In California, property tax rates can be elevated, impacting regular expenses.
Why is homeowners insurance important in a mortgage payment?
Homeowners insurance protects your property from damages and is part of the regular mortgage charge. It is especially crucial in areas prone to natural disasters, such as California.
How can understanding mortgage components help with budgeting?
Understanding the components of a mortgage payment allows for accurate calculations of monthly expenses, helping to manage budgets effectively and avoid unexpected financial strain.
What are VA loans and USDA financing options?
VA loans and USDA financing options are types of loans that may offer favorable terms and lower costs, making homeownership more accessible for potential buyers.
List of Sources
- Understand Mortgage Payments and Their Components
- Map shows the states paying the most in mortgage payments (https://newsweek.com/map-shows-states-paying-most-mortgage-payments-2018626)
- Monthly Mortgage Payments for Homeowners Who Moved in 2024 Were $2,225, Above the U.S. Median of $1,521 (https://census.gov/library/stories/2025/09/recent-homebuyers-mortgage-payments.html)
- What is the average mortgage payment? (https://rocketmortgage.com/learn/average-mortgage-payment)
- Mortgage payments have nearly doubled in the past decade. These counties saw the biggest rise (https://kcra.com/article/mortgage-rates-impact-homeowners/68151086)
- Calculate Monthly Payments Using the Mortgage Formula
- What’s the average mortgage payment in Nevada? (https://rocketmortgage.com/learn/average-mortgage-payment-nevada)
- How Much is the Average Mortgage in California? (https://triadfs.com/news/how-much-is-the-average-mortgage-in-california)
- 30-Year Fixed Rate Mortgage Average in the United States (https://fred.stlouisfed.org/series/mortgage30us)
- Compare Today's 30-Year Mortgage Rates | Bankrate (https://bankrate.com/mortgages/30-year-mortgage-rates)
- Mortgage Rates (https://freddiemac.com/pmms)
- Explore Factors Affecting Your Monthly Mortgage Payment
- Data Spotlight: The Impact of Changing Mortgage Interest Rates | Consumer Financial Protection Bureau (https://consumerfinance.gov/data-research/research-reports/data-spotlight-the-impact-of-changing-mortgage-interest-rates)
- Mortgage payments have nearly doubled in the past decade. These counties saw the biggest rise (https://kcra.com/article/mortgage-rates-impact-homeowners/68151086)
- High mortgage rates compound housing affordability challenges (https://pbs.org/newshour/show/high-mortgage-rates-compound-housing-affordability-challenges)
- National Mortgage Database (NMDB®) Aggregate Statistics | FHFA (https://fhfa.gov/data/nmdb)
- How Interest Rates Affect Your Mortgage Payments - Great Basin Federal Credit Union (https://greatbasin.org/how-interest-rates-affect-your-mortgage-payments)
- Implement Strategies to Lower Your Monthly Mortgage Costs
- US Mortgage Statistics 2026: Debt, Delinquency and Foreclosure Data (https://lendingtree.com/home/mortgage/u-s-mortgage-market-statistics)
- Redfin’s 2026 Predictions: Welcome to The Great Housing Reset (https://redfin.com/news/housing-market-predictions-2026)
- Mortgage payments have nearly doubled in the past decade. These counties saw the biggest rise (https://kcra.com/article/mortgage-rates-impact-homeowners/68151086)
- Mortgage Rates Slide: Best Tips For A Low Rate | Bankrate (https://bankrate.com/mortgages/tips-as-mortgage-rates-slide-to-year-low)
- Mortgage refinancing demand surges. Here's who can benefit now. (https://cbsnews.com/news/mortgage-refinancing-demand-surges-heres-who-can-benefit-now)



