How Much of Your Net Income Should Go to Mortgage Payments?

Introduction
In today's fluctuating housing market, understanding how much of your net income to allocate to mortgage payments is more critical than ever. With rising home prices and varying income levels, determining the right percentage can significantly impact your financial stability and long-term goals.
So, how can you assess your unique situation to make informed decisions and avoid financial strain?
Understand Your Financial Landscape
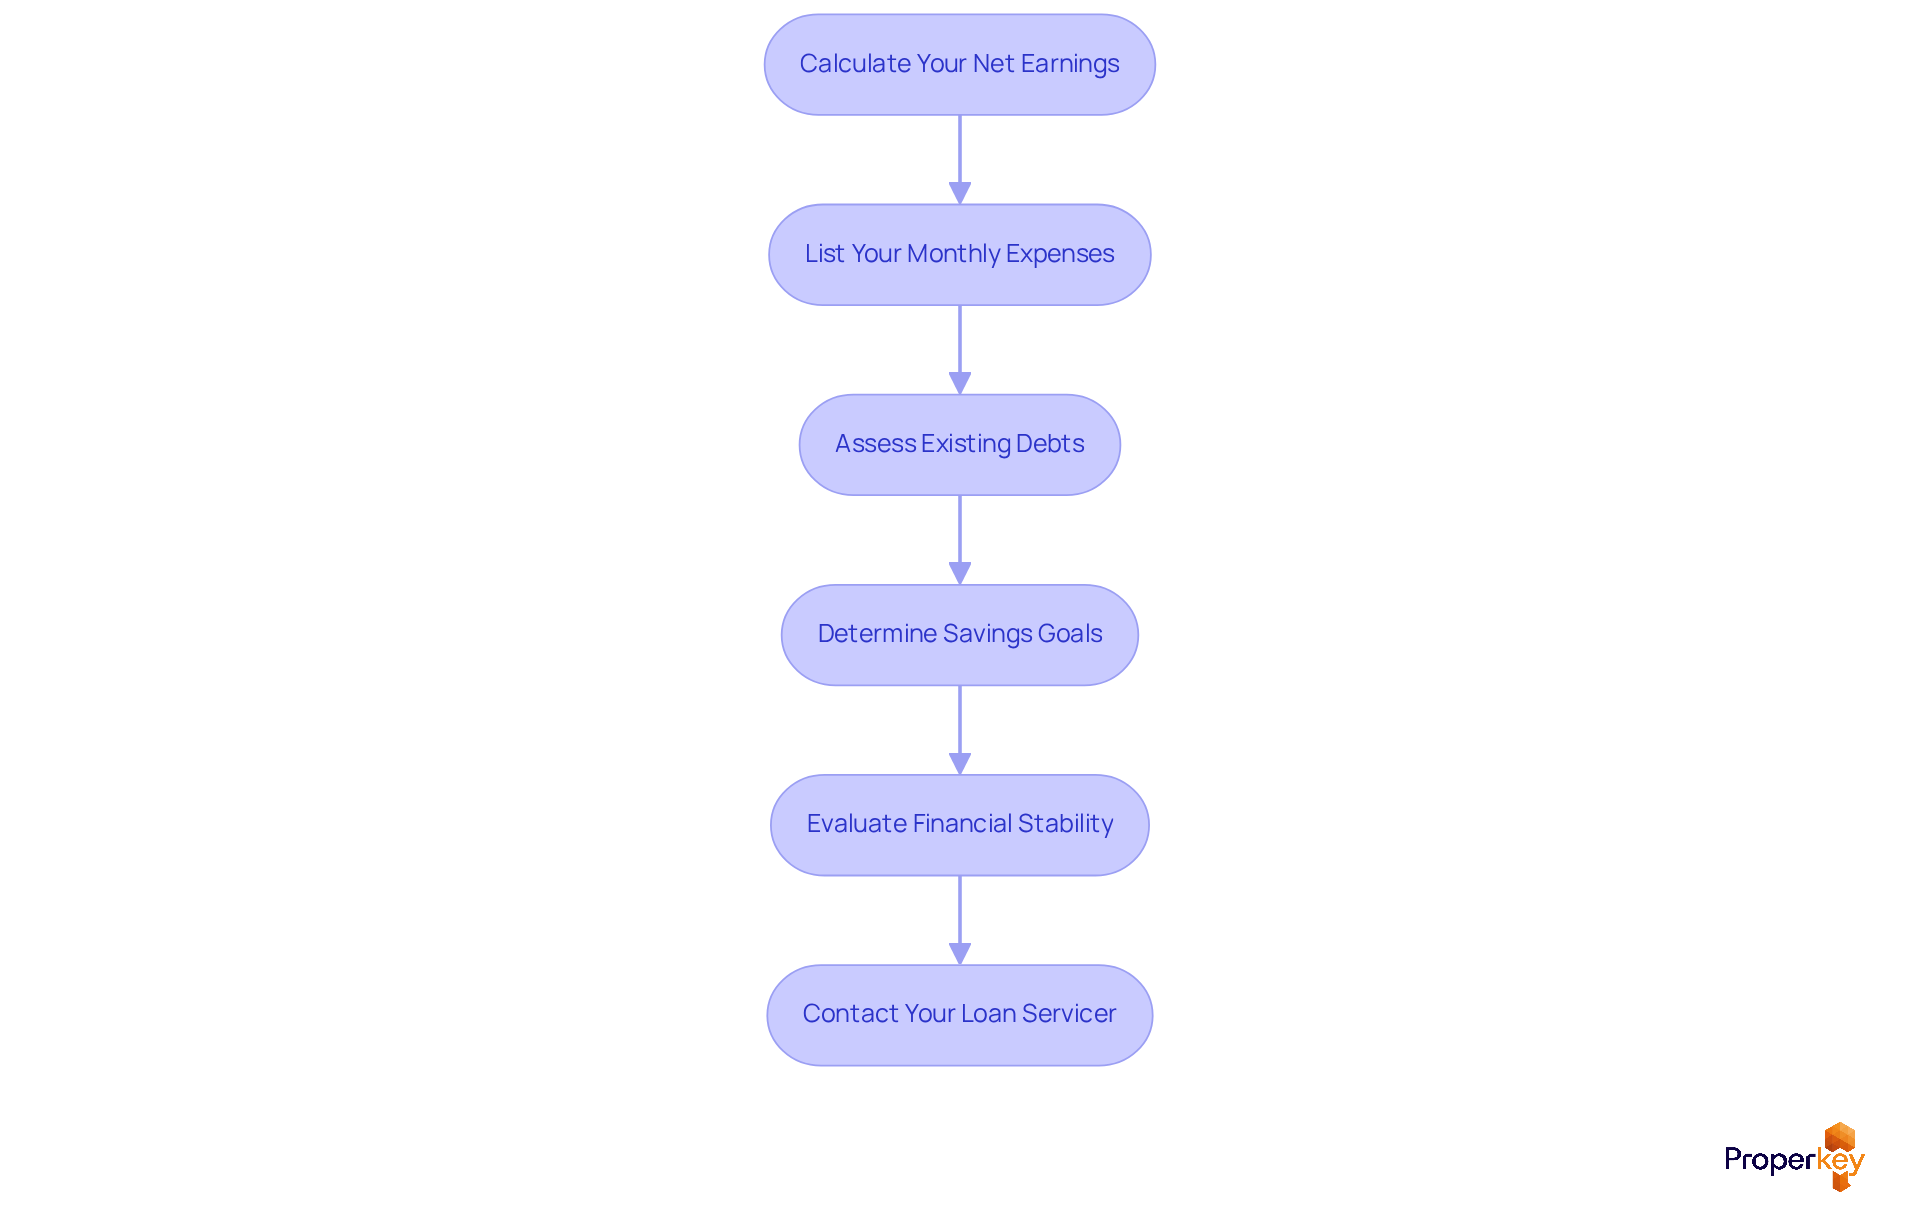
Navigating the complexities of mortgage payments can be daunting, especially when financial stability is at stake. To determine how much of net income should go to mortgage payments, start by evaluating your overall financial situation. Follow these steps:
- Calculate Your Net Earnings: Begin by determining your net earnings. This is your total revenue after taxes and other deductions. In California, the average net income in 2026 is about $5,000 per month. This figure reflects the state's higher living costs, making your calculations crucial.
- List Your Monthly Expenses: Create a detailed list of your monthly expenses, including utilities, groceries, transportation, insurance, and any other recurring costs. This helps you understand your financial responsibilities and how much of net income should go to mortgage payments.
- Assess Existing Debts: Take stock of any existing debts, such as credit card balances, student loans, or car payments. Understanding your debt load is essential for calculating your debt-to-income (DTI) ratio, which lenders often use to assess mortgage eligibility. In California, it is advisable that total monthly debt should not exceed 43 percent of your gross monthly income.
- Determine Savings Goals: Consider your savings goals, including emergency funds, retirement savings, and other monetary objectives. This will help you allocate funds appropriately and ensure you are not stretching your budget too thin. For example, reserving money for unforeseen costs can avert economic pressure in the long term.
- Evaluate Financial Stability: Reflect on your job security and any potential changes in earnings. Unpredictable income can strain your budget, making it crucial to allocate funds wisely. Homeowners in Idaho and Nevada may experience different job market dynamics that could affect their income stability.
- Contact Your Loan Servicer: If you face challenges in making loan installments, reach out to your loan servicer for assistance. They can offer choices and tools to help you manage your loan effectively.
This understanding empowers you to secure a stable financial future.
Explore Common Mortgage-to-Income Ratios
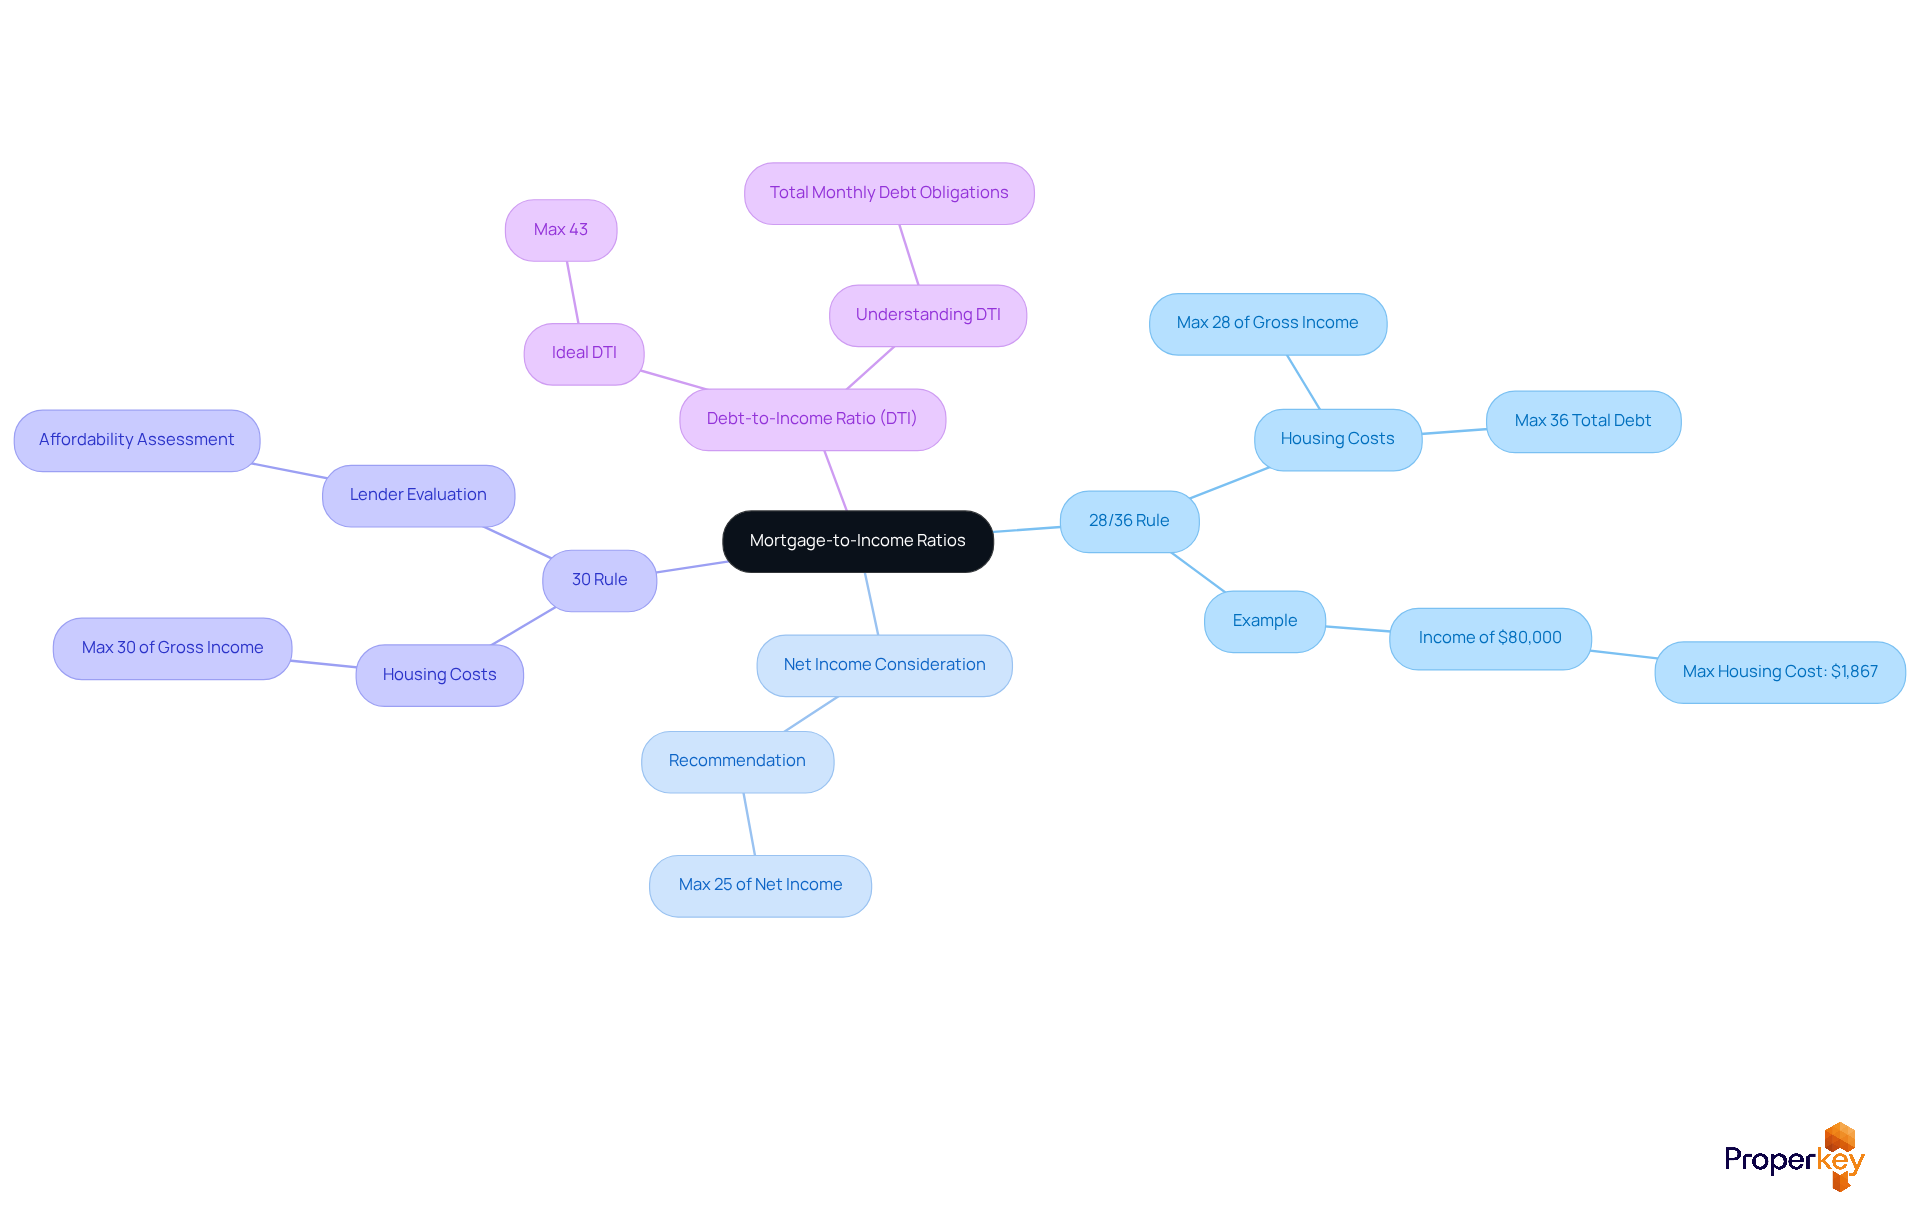
Navigating the complexities of loan-to-income ratios is essential for home sellers aiming to set realistic housing costs. Here are some widely recognized guidelines:
- 28/36 Rule: This guideline indicates that no more than 28% of your total monthly earnings should be allocated to housing costs, which encompass mortgage installments, property taxes, and insurance. Furthermore, total debt obligations, including all monthly responsibilities such as auto loans and credit cards, should not surpass 36% of your gross earnings. For instance, an individual earning $80,000 each year should target a maximum housing cost of approximately $1,867 per month according to this guideline.
- Some experts suggest that homeowners should consider how much of net income should go to mortgage payments, recommending no more than 25%. This method considers how much of net income should go to mortgage after taxes, providing a more realistic perspective on economic capacity.
- 30% Rule: Another common guideline is that housing costs should not exceed 30% of your gross monthly income. This guideline is frequently utilized by lenders to evaluate affordability and ensure borrowers can handle their loan obligations without economic stress.
- Debt-to-Income Ratio (DTI): Lenders typically look for a DTI ratio of 43% or lower, which includes all monthly debt payments. Knowing your DTI helps you understand how much mortgage you can realistically afford, considering all your financial obligations.
In states like California, Idaho, and Nevada, these ratios matter more than ever as home prices continue to rise and incomes vary. For example, in California, the median household income is roughly $83,150, indicating that under the 28% rule, a household should target a maximum housing cost of about $1,867 each month. However, many households are struggling to keep up with rising home prices, which often exceed $400,000. Notably, only about 46% of California households could qualify for a mortgage on a bottom-tier home in 2026, highlighting the challenges faced by potential homebuyers in the current market.
Case studies demonstrate these challenges: Parker, earning $100,000 each year, can afford a monthly housing cost of $2,333 under the 28/36 guideline, supporting a purchase price around $330,000. However, with a 50% DTI, he could be eligible for as much as $450,000, which would take up 62% of his total earnings, possibly resulting in economic pressure.
By understanding these ratios, you can make informed decisions that protect your financial well-being in a challenging market.
Calculate Your Ideal Mortgage Payment
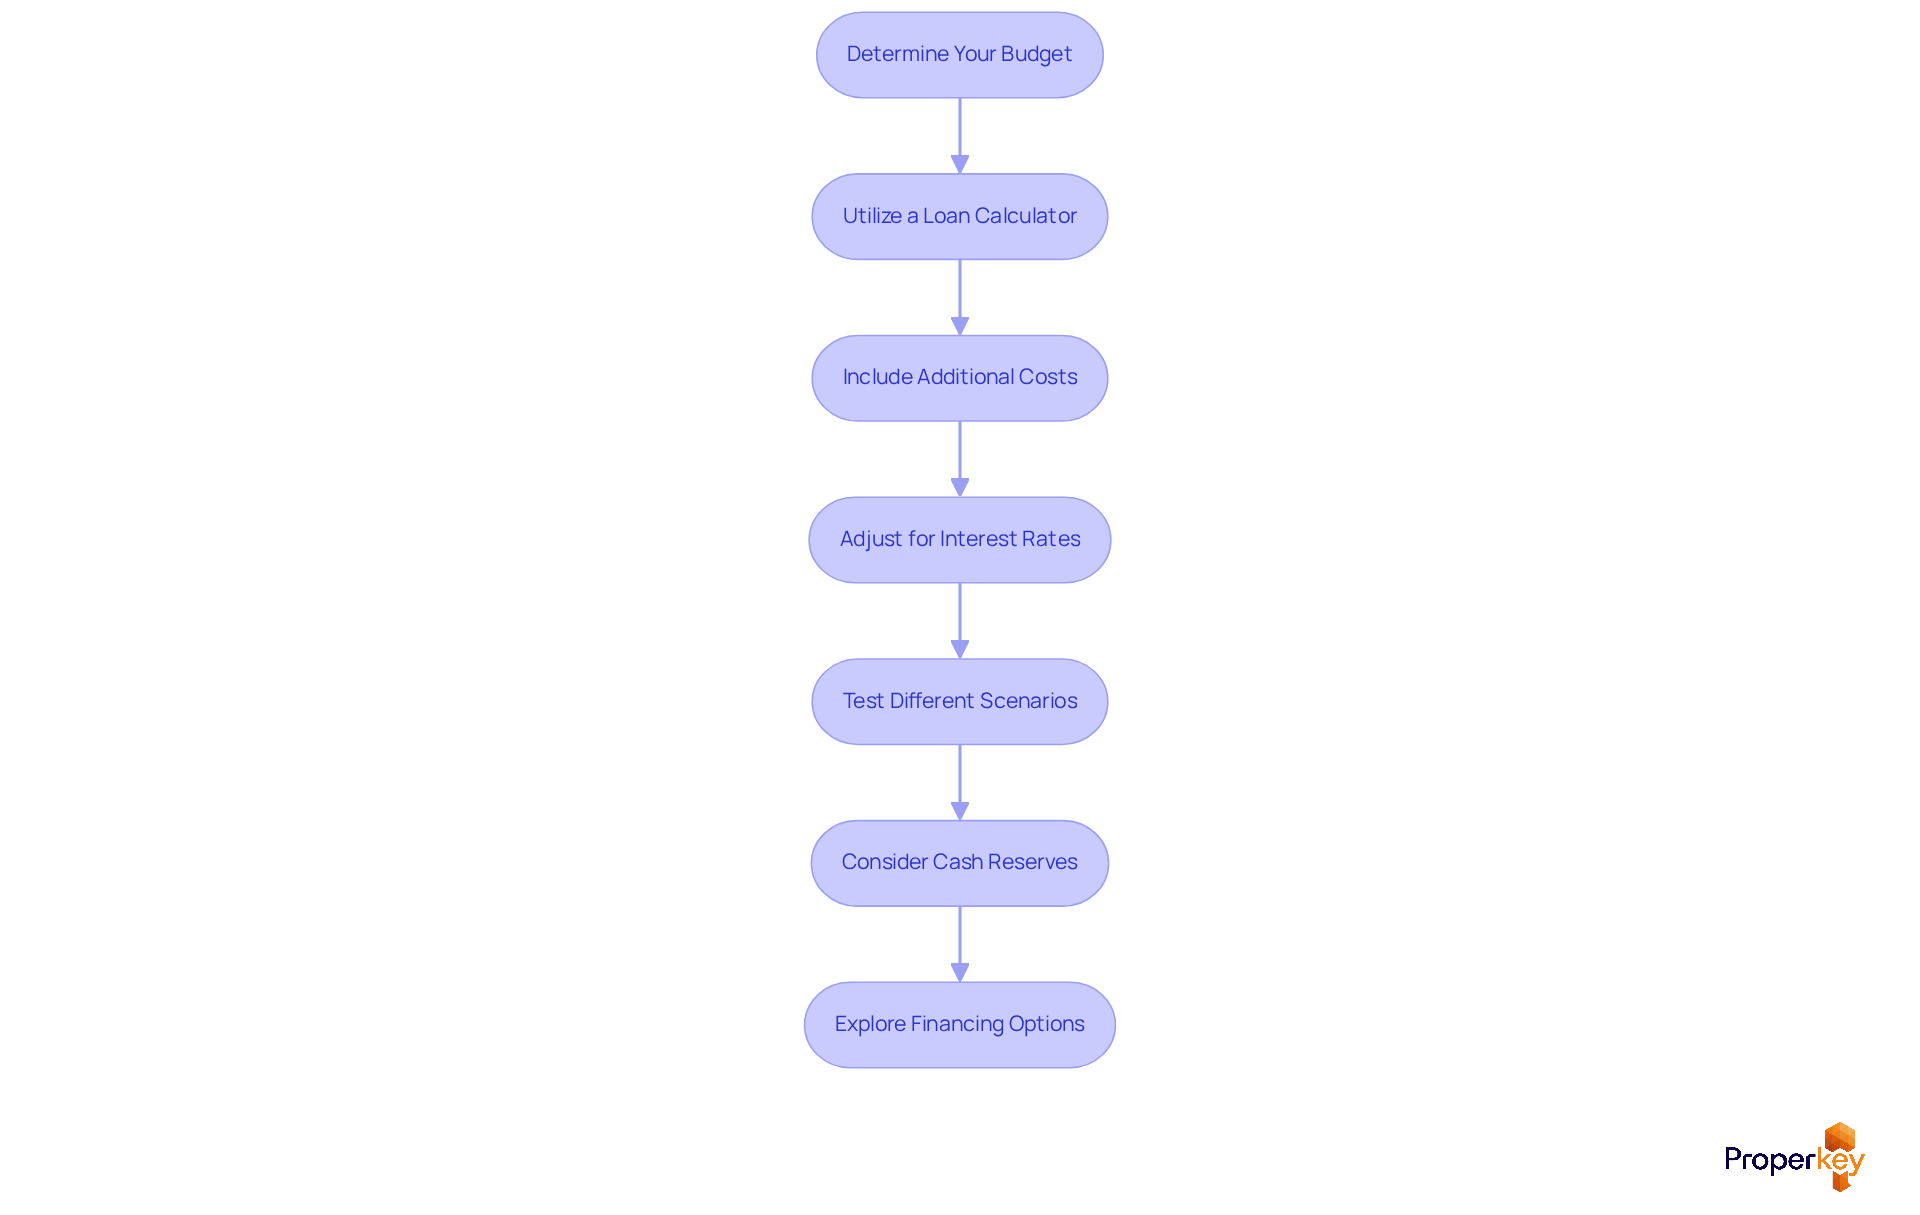
Navigating the complexities of mortgage payments can be daunting for many home sellers. To calculate your ideal mortgage payment, follow these steps:
- Determine your budget by evaluating your financial circumstances and deciding how much of net income should go to mortgage each month. The 28/36 guideline indicates that no more than 28% of your gross monthly income should be allocated to housing expenses, which raises the question of how much of net income should go to mortgage, while total debt obligations should not surpass 36%.
- Utilize a Loan Calculator: Use an online loan calculator to enter your desired loan amount, interest rate, and loan duration. This tool will provide an estimate of your monthly charge, including principal and interest.
- Include Additional Costs: Don’t forget about extra costs like property taxes and homeowner's insurance. If you need private mortgage insurance (PMI), that’s another expense to factor in. For instance, homeowner's insurance usually amounts to around $35 monthly for each $100,000 of the home's worth, which can greatly influence your overall monthly expense.
- Adjust for Interest Rates: Stay informed about current interest rates, as they can significantly affect your mortgage cost. A lower interest rate can decrease your monthly cost, while a higher rate will raise it. Monitoring market trends will help you make informed decisions.
- Test Different Scenarios: Experiment with various loan amounts and terms to see how they affect your monthly cost. This method will assist you in achieving a balance between an affordable cost and the home you desire.
- Consider Cash Reserves: You’ll want to keep some cash reserves handy to cover a few months of mortgage payments and other costs. This monetary cushion can provide peace of mind and help you handle unforeseen expenses.
- Explore Financing Options: Consider using Loanvana's financing tool, which allows you to apply once and compare hundreds of loan options side-by-side from multiple lenders. This tool streamlines the process of discovering the best rates and terms for your loan while offering access to real-time interest rates.
By understanding these steps, you empower yourself to make sound financial decisions that safeguard your future. Remember, grasping your economic landscape and the local real estate market in California, Idaho, and Nevada is crucial for making informed decisions.
Consider Financial Implications and Risks
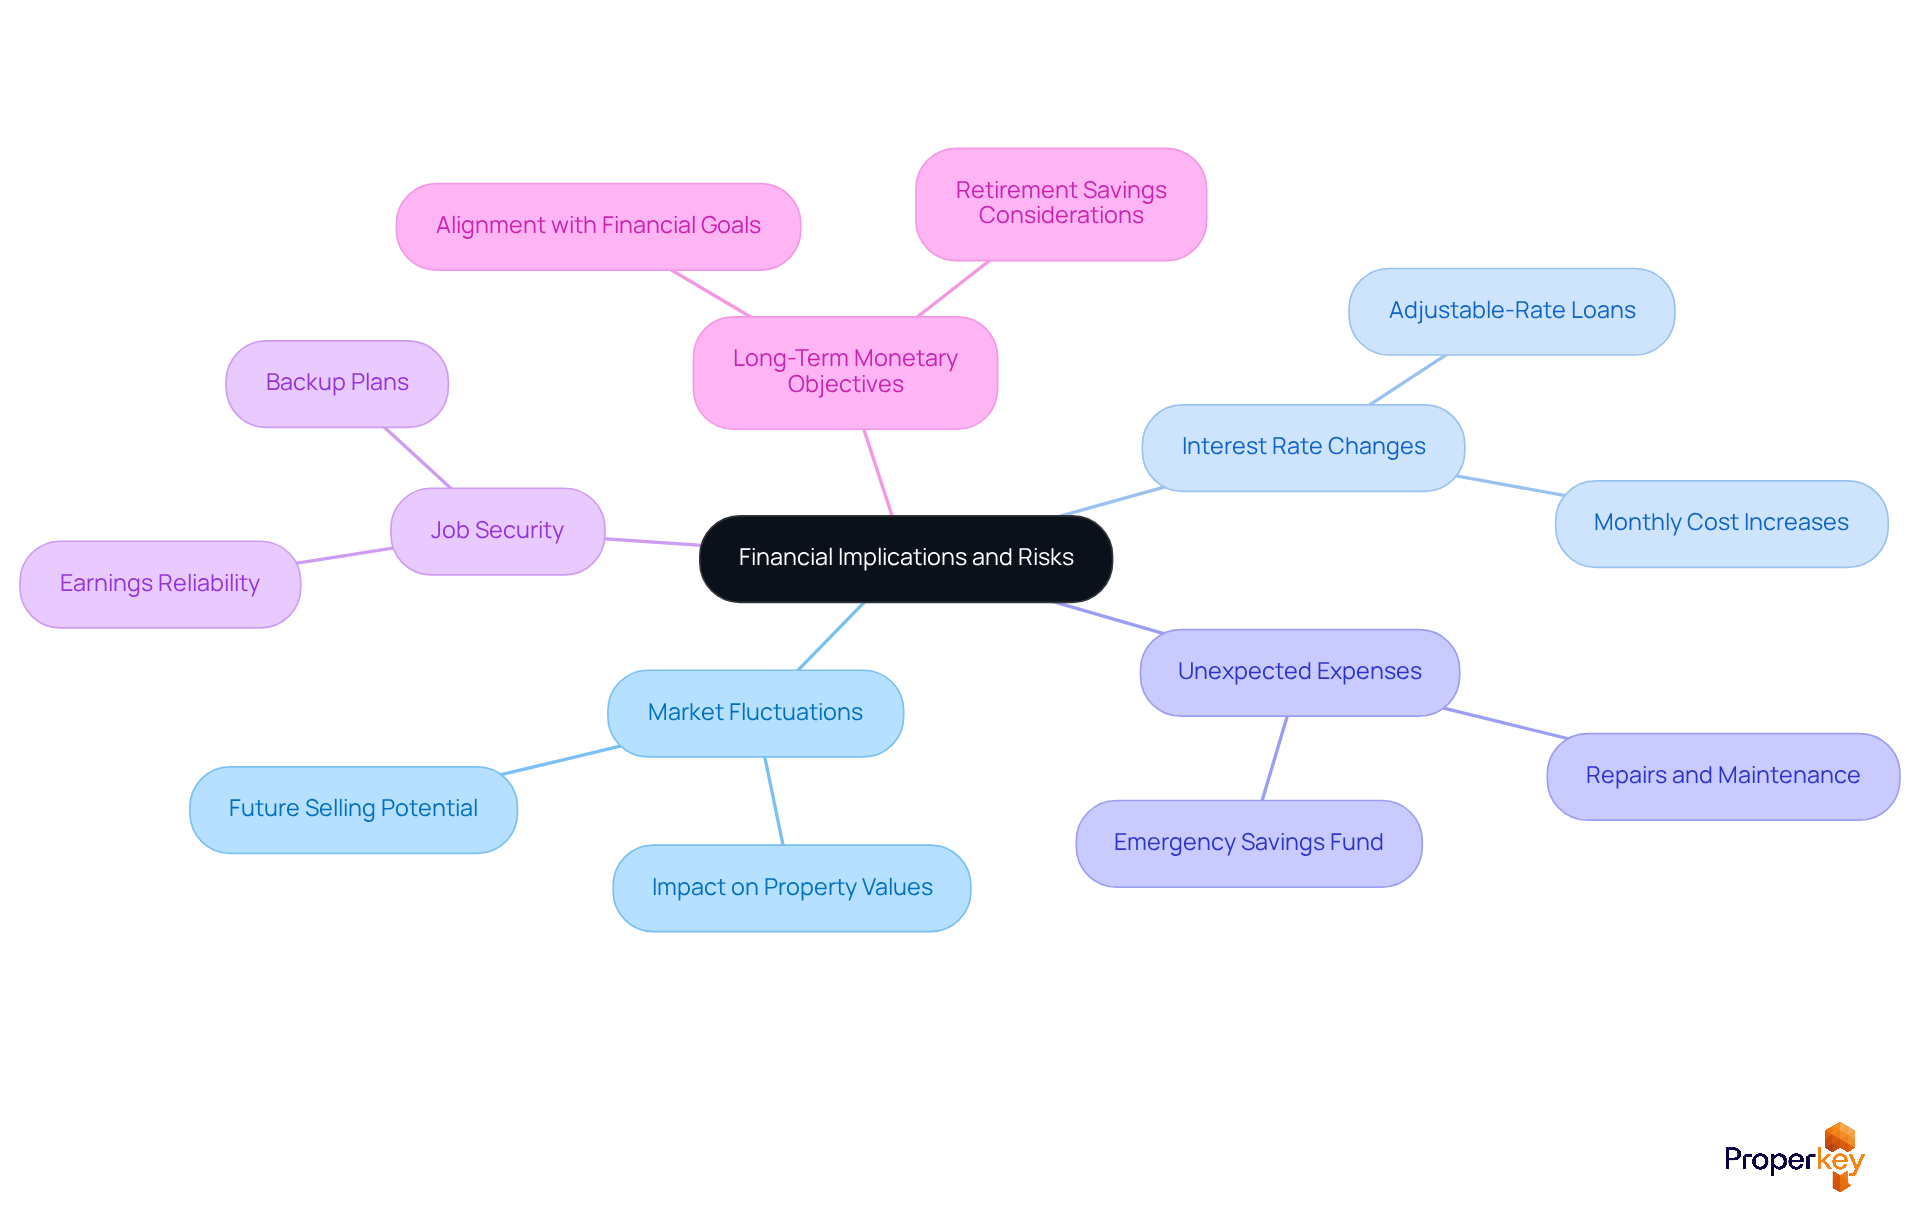
Navigating mortgage payments requires a keen understanding of financial risks and implications. Here are key factors to consider:
- Market Fluctuations: Housing markets in California, Idaho, and Nevada can swing dramatically, affecting property values and your future selling potential. A downturn could leave you owing more than your home is worth, creating financial strain.
- Interest Rate Changes: Choosing an adjustable-rate loan? Be ready for possible interest rate hikes. These changes can significantly raise your monthly costs over time, impacting your overall budget and economic stability.
- Unexpected Expenses: Homeownership often comes with surprise costs, like repairs and maintenance. You need to keep a financial cushion to handle these costs without risking your mortgage payments. An emergency savings fund can help manage affordability risks from unforeseen changes in earnings.
- Job Security: Assess your job stability and earnings reliability. Changes in your financial situation can directly affect your ability to make loan payments. Having a backup plan, like an emergency fund, is wise in case of job loss or reduced income.
- Long-Term Monetary Objectives: Reflect on how a home loan fits into your broader financial strategy. Ensure that allocating part of your earnings to housing costs aligns with your long-term goals, such as retirement savings or funding education.
By weighing these financial risks, you can make a smarter choice about how much of net income should go to mortgage payments, paving the way for a secure financial future.
Conclusion
Many prospective homeowners find themselves overwhelmed by the complexities of mortgage payments. Understanding how much of your net income should be allocated to these payments is essential for maintaining financial stability and making informed home-buying decisions. Evaluating your personal finances - income, expenses, and existing debts - will help you pinpoint a sustainable mortgage payment that aligns with your financial goals.
Key insights from this article highlight the importance of common mortgage-to-income ratios, such as the 28/36 rule and the 30% guideline, which serve as benchmarks for assessing affordability. Additionally, calculating the ideal mortgage payment involves considering various factors, including interest rates, additional costs, and potential market fluctuations. Recognizing the financial implications and risks associated with homeownership empowers you to make sound decisions that protect your economic well-being.
This understanding not only enhances financial stability but also empowers individuals to make informed choices. By prioritizing financial health and adhering to recommended guidelines, prospective homeowners can confidently navigate the mortgage landscape, ensuring their investment aligns with their long-term financial objectives.
Frequently Asked Questions
How can I determine how much of my net income should go to mortgage payments?
Start by evaluating your overall financial situation, which includes calculating your net earnings, listing your monthly expenses, assessing existing debts, determining savings goals, and evaluating your financial stability.
What are net earnings and how do I calculate them?
Net earnings are your total revenue after taxes and other deductions. For example, in California, the average net income in 2026 is about $5,000 per month.
Why is it important to list my monthly expenses?
Listing your monthly expenses helps you understand your financial responsibilities and how much of your net income can be allocated to mortgage payments.
How do existing debts affect my mortgage payment calculations?
Existing debts, such as credit card balances and student loans, impact your debt-to-income (DTI) ratio, which lenders use to assess mortgage eligibility. In California, it is advisable that total monthly debt should not exceed 43 percent of your gross monthly income.
What should I consider when determining my savings goals?
Consider your savings goals for emergency funds, retirement savings, and other monetary objectives to ensure you allocate funds appropriately and avoid stretching your budget too thin.
How does financial stability influence my mortgage payment decisions?
Reflecting on your job security and potential changes in earnings is crucial, as unpredictable income can strain your budget and affect how you allocate funds for mortgage payments.
What should I do if I have challenges making loan installments?
If you face challenges in making loan installments, it is advisable to contact your loan servicer for assistance, as they can offer options and tools to help you manage your loan effectively.
List of Sources
- Understand Your Financial Landscape
- Mortgages | Consumer Financial Protection Bureau (https://consumerfinance.gov/consumer-tools/mortgages)
- Difficulties Making Your Mortgage Payments? | FDIC.gov (https://fdic.gov/consumer-resource-center/2021-01/difficulties-making-your-mortgage-payments)
- How Do Mortgages Work? | City National Bank (https://cnb.com/personal-banking/insights/how-does-mortgage-work.html)
- The 'biggest mistake' people make when they're falling behind on mortgage payments (https://pbs.org/newshour/nation/worried-about-your-mortgage-payment-heres-what-experts-recommend)
- Is Gross Income or Net Income Better for Calculating Mortgage Affordability? | Total Mortgage (https://totalmortgage.com/learn/is-gross-income-or-net-income-better-for-calculating-mortgage-affordability)
- Explore Common Mortgage-to-Income Ratios
- Mapped: California Metros Where Homebuyers Have To Fork Out Biggest Share of Income To Afford a Mortgage (https://realtor.com/news/trends/california-metros-homeowners-income-mortgage-payments)
- California Homebuyers Face Nation's Biggest Affordability Gap (https://nationalmortgageprofessional.com/news/california-homebuyers-face-nations-biggest-affordability-gap)
- How Much House Can You Afford in 2026? A Complete Guide to Your Home Budget (https://amerisave.com/learn/how-much-house-can-you-afford-in-a-complete-guide-to-your-home-budget)
- California housing affordability retreated in the second quarter after reaching a four-year high in early 2026, C.A.R. reports (https://prnewswire.com/news-releases/california-housing-affordability-retreated-in-the-second-quarter-after-reaching-a-four-year-high-in-early-2026-car-reports-302844012.html)
- Calculate Your Ideal Mortgage Payment
- How Much House Can I Afford? Affordability Calculator - NerdWallet (https://nerdwallet.com/mortgages/calculators/how-much-house-can-i-afford)
- Affordability Calculator - How Much House Can I Afford? | Zillow (https://zillow.com/mortgage-calculator/house-affordability)
- Mortgage affordability calculator: What house can I afford? | Chase.com (https://chase.com/personal/mortgage/calculators-resources/affordability-calculator)
- How Much House Can I Afford? | Affordability Calculator | Wells Fargo (https://wellsfargo.com/mortgage/calculators/home-affordability-calculator)
- Mortgage Affordability Calculator | Fannie Mae (https://yourhome.fanniemae.com/calculators-tools/mortgage-affordability-calculator)
- Consider Financial Implications and Risks
- Mortgage costs could jump for millions, Bank says (https://bbc.com/news/articles/cn8g3n9y5x0o)
- Impact of Mortgage Delinquency on Finances - HAR.com (https://har.com/ri/2371/how-mortgage-delinquency-affects-your-financial-future)
- The Big Shift in Mortgage Lending That Poses Risks to the Housing Market (https://gao.gov/blog/big-shift-mortgage-lending-poses-risks-housing-market)
- Purchase demand at risk as monthly payments hit new highs (https://nationalmortgagenews.com/news/purchase-demand-at-risk-as-monthly-payments-hit-new-highs)
- Risks Associated with Mortgages Tabid (https://continuum-wealth.co.uk/Financial-Services/Mortgages/Risks-Associated-with-Mortgages)