Master Getting a 2nd Mortgage: Steps, Benefits, and Risks Explained
Introduction
Homeowners often find themselves overwhelmed by the intricacies of second mortgages, unsure of where to begin. This guide will walk you through the essential steps, benefits, and risks associated with obtaining a second mortgage, equipping you with the knowledge to leverage your home equity effectively. However, understanding the risks is crucial; without this knowledge, homeowners may inadvertently jeopardize their financial future.
Define a Second Mortgage: Understanding the Basics
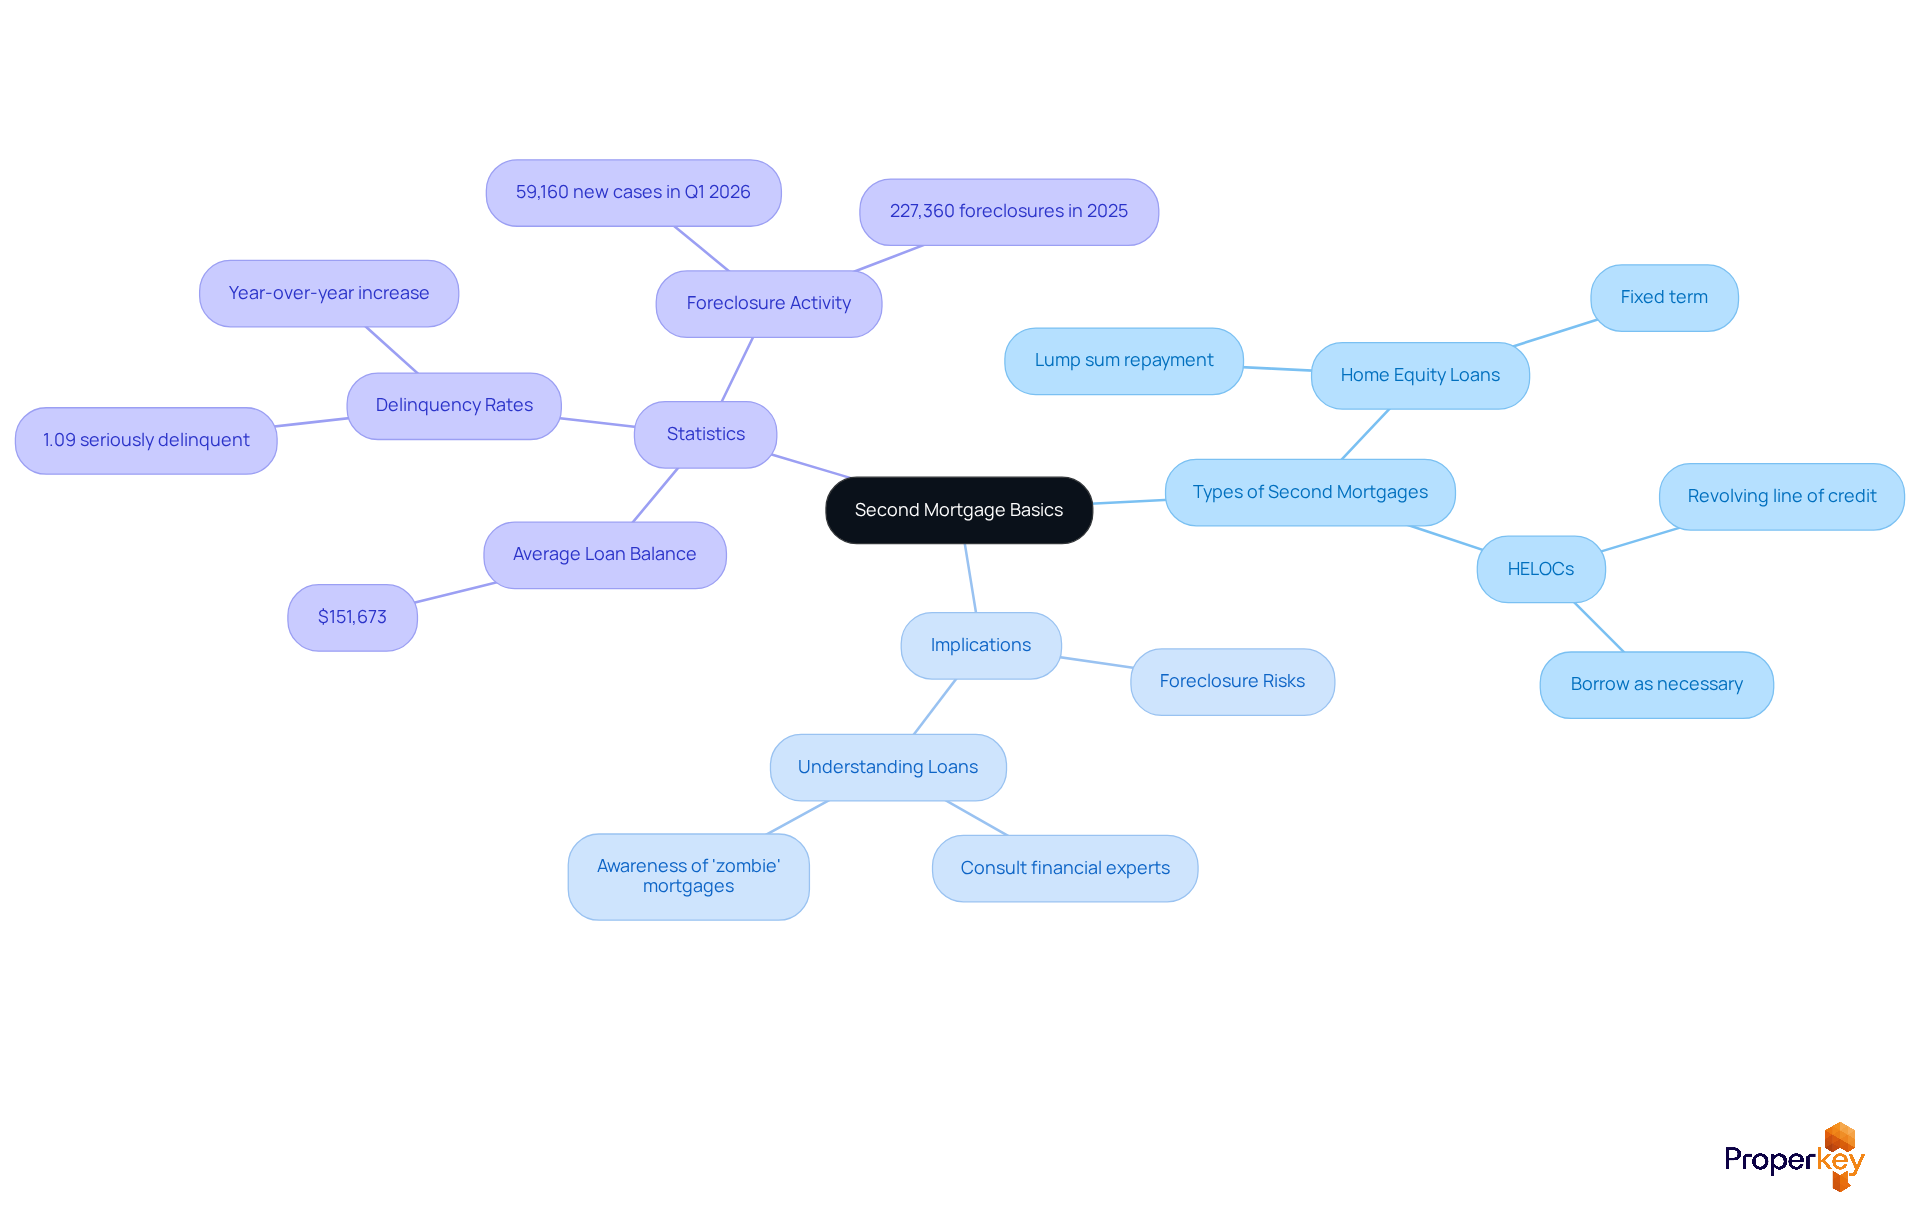
Navigating the complexities of getting a 2nd mortgage can be daunting for homeowners, especially when unexpected financial strains arise. An additional loan, often referred to as getting a 2nd mortgage, is a financial instrument that allows property owners to access the equity of their asset while keeping their primary loan. This loan is secured by your home. If you fail to repay, it could lead to foreclosure. Usually, additional loans are classified into two categories:
- Home equity loans
- Home equity lines of credit (HELOCs)
Home equity loans provide a lump sum that is repaid over a fixed term, making them suitable for one-time expenses. In contrast, HELOCs operate as a revolving line of credit, enabling property owners to borrow as necessary, which can be especially advantageous for ongoing projects or emergencies.
In California, the resurgence of dormant second mortgages, often called 'zombie' second mortgages, has raised concerns among property owners. Homeowners may find themselves unexpectedly facing repayment demands for loans they thought were inactive. This situation highlights the importance of understanding the consequences of getting a 2nd mortgage today. For instance, homeowners who believed these debts were inactive may face demands for repayment, sometimes threatening foreclosure if they do not address the situation before getting a 2nd mortgage.
As of 2026, the average loan balance in the U.S. stands at $151,673, with 1.09% of these balances seriously delinquent, indicating that most borrowers are managing their payments effectively. However, the rise in foreclosure activity-59,160 new cases in the first quarter of 2026-emphasizes the need for caution when considering getting a 2nd mortgage. Homeowners should consult with financial experts to navigate these options wisely, ensuring they make informed decisions that align with their financial goals. Understanding the implications of additional loans is crucial; failing to do so could jeopardize your financial stability and home ownership.
Navigate the Application Process for a Second Mortgage
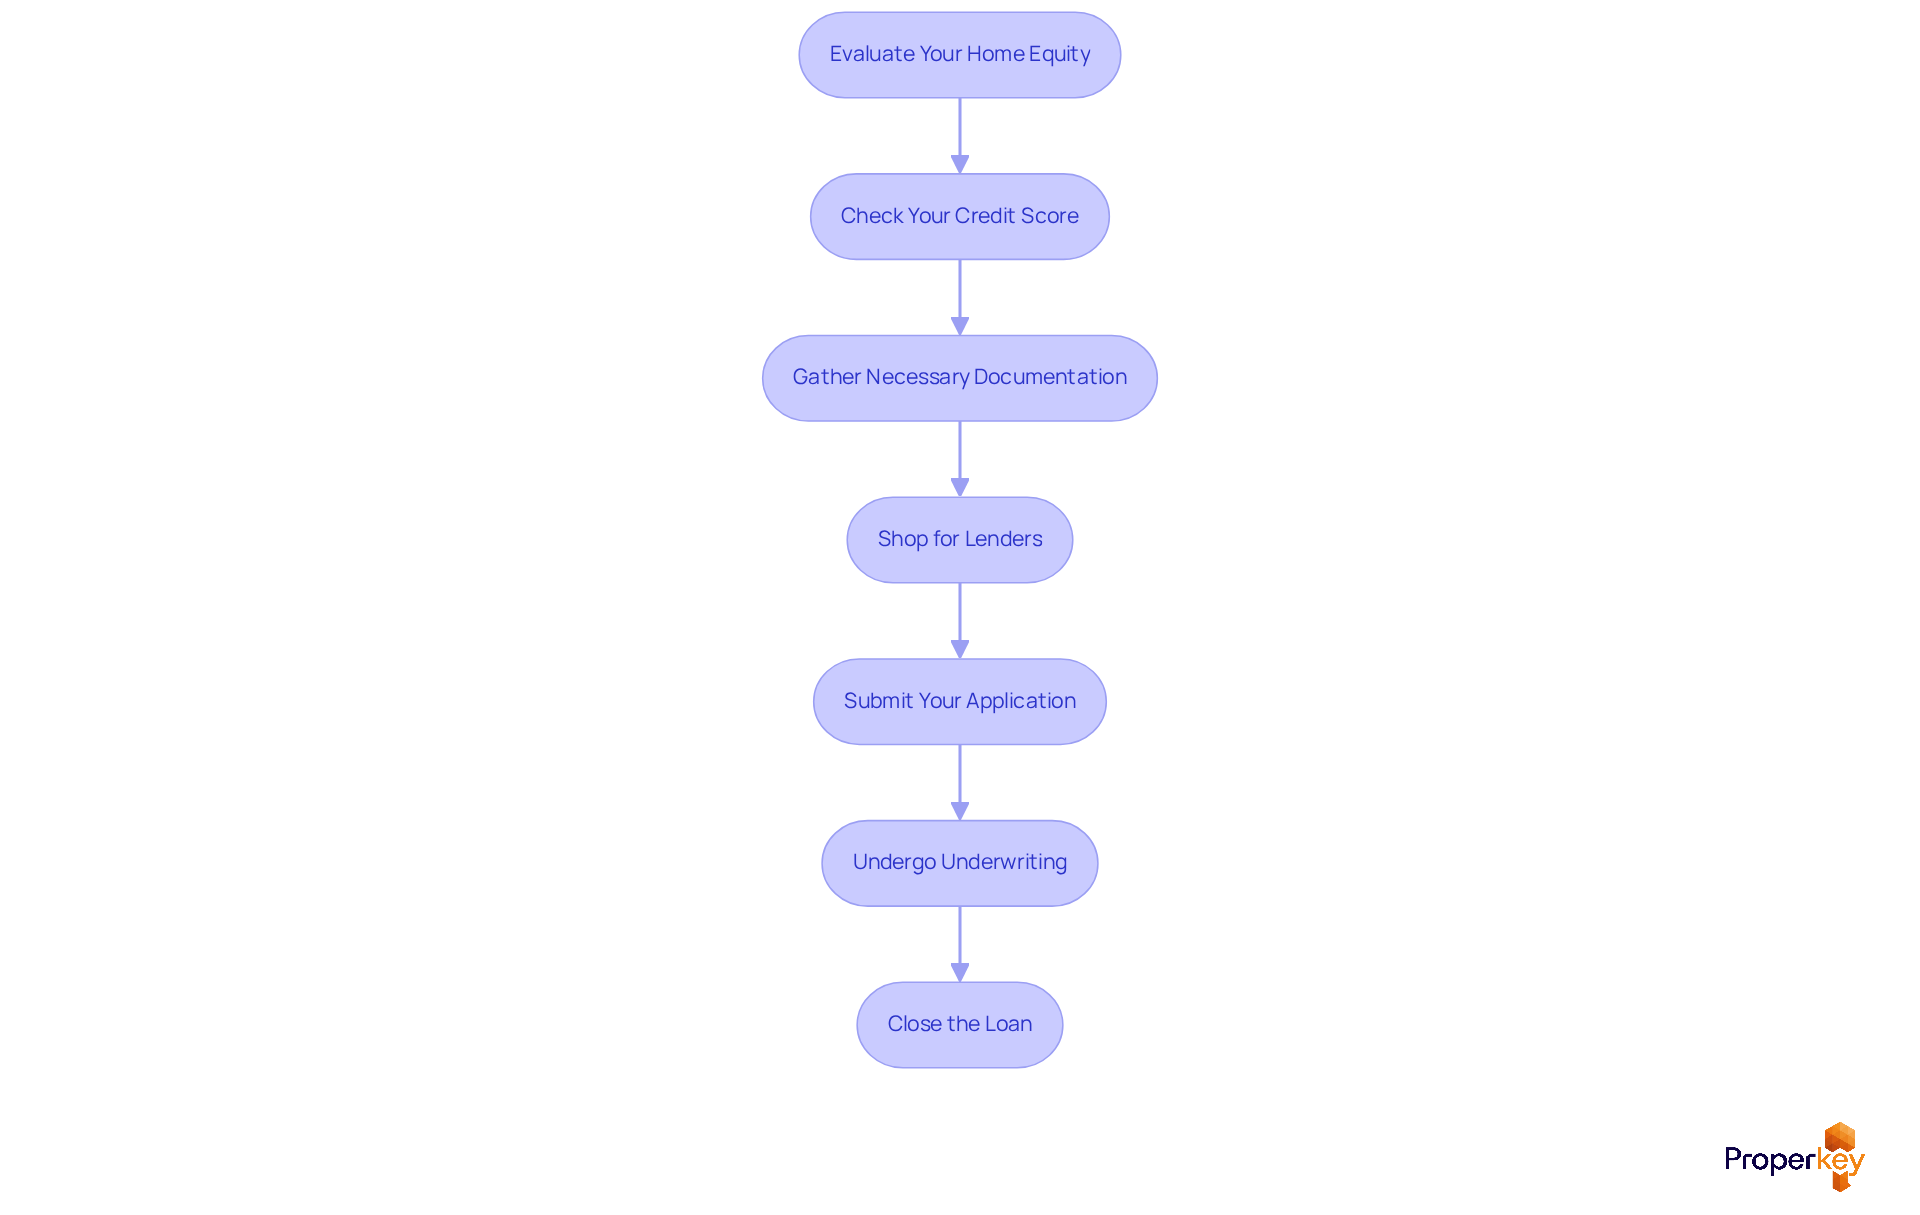
Navigating the complexities of getting a 2nd mortgage can be daunting, but understanding the essential steps can empower you to make informed decisions.
- Evaluate Your Home Equity: Start by determining your home equity. This is simply the difference between your home's current market value and what you still owe on your initial loan. Most lenders typically require at least 15% to 20% equity to qualify for getting a 2nd mortgage. Without adequate equity, your chances of getting a 2nd mortgage diminish significantly.
- Check Your Credit Score: Your credit score plays a pivotal role in securing favorable loan terms. Aim for a score of 620 or higher to enhance your chances. Review your credit report for any errors or discrepancies that could affect your score. Failing to address your credit score could lead to higher interest rates or even denial of your application.
- Gather Necessary Documentation: Get your paperwork in order. This includes proof of income-like pay stubs and tax returns-a list of your debts and assets, and proof of homeownership.
- Shop for Lenders: Investigate and compare rates and terms from a variety of lenders, including both traditional banks and online options. Loanvana simplifies this process with its financing tool, allowing you to apply once and compare hundreds of loan options side-by-side from multiple lenders. This feature offers wholesale access to loan programs and clear comparisons, assisting you in finding the most competitive deal suited to your circumstances.
- Submit Your Application: Fill out the lender's application form carefully, making sure to include all necessary documentation. Be prepared for a credit check and a home appraisal-these are standard parts of the process.
- Undergo Underwriting: The lender will evaluate your application, scrutinize your financial profile, and decide your eligibility for the loan.
- Close the Loan: Once your application gets the green light, you'll sign the loan documents and receive your funds. These funds can be used for various purposes, such as home improvements or debt consolidation, offering you monetary flexibility. By following these steps, you position yourself not just to secure a loan, but to unlock the potential of your home equity for your financial future.
Explore the Benefits of a Second Mortgage: Financial Opportunities
While getting a 2nd mortgage can unlock financial opportunities, it also carries significant risks that every homeowner must consider. A second mortgage can provide homeowners with several financial advantages:
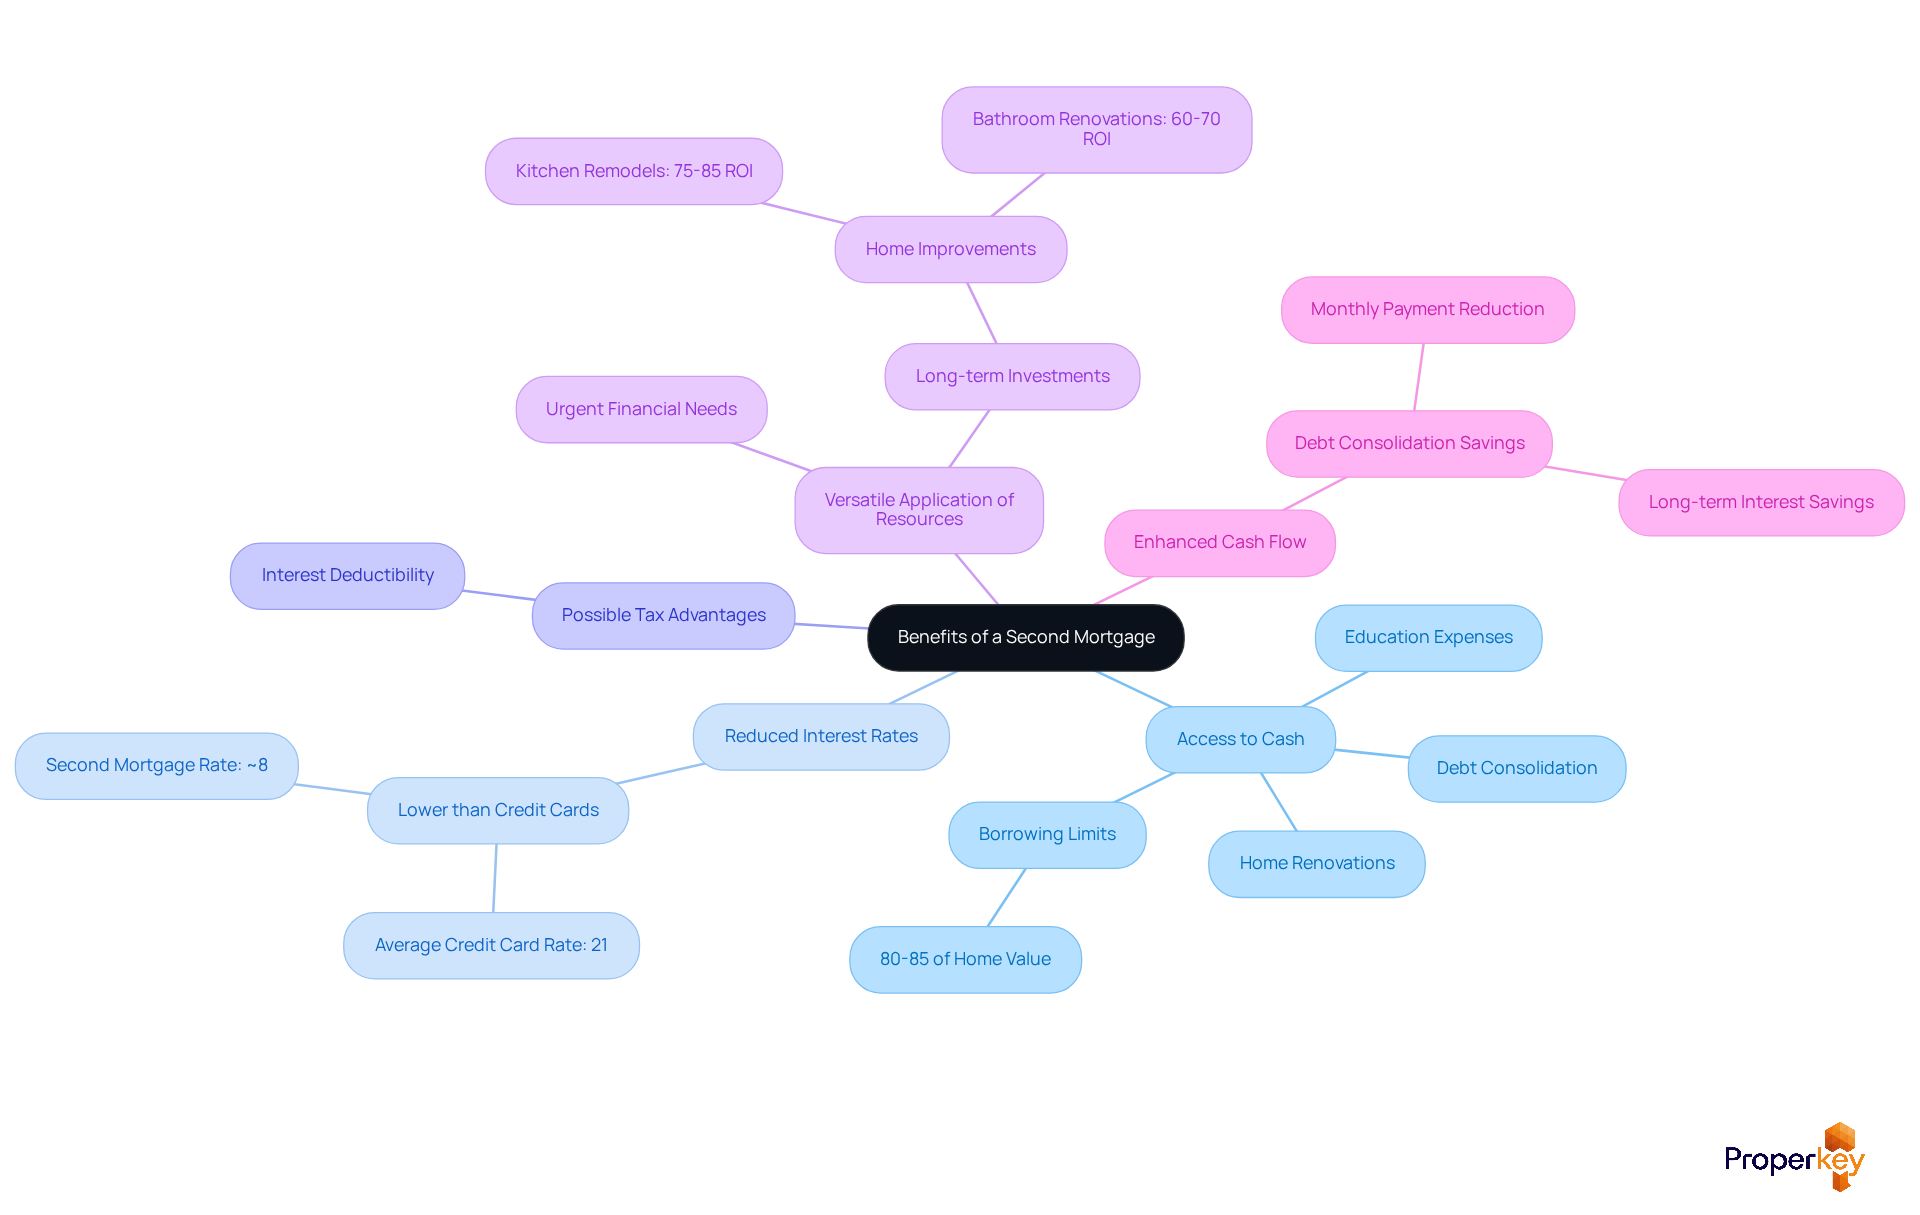
- Access to Cash: Homeowners can leverage their home equity to access substantial funds for various needs, such as home renovations, education expenses, or debt consolidation. In California, homeowners can typically borrow up to 80-85% of their home's appraised value. This access to cash can be substantial.
- Reduced Interest Rates: Compared to unsecured loans or credit cards, which often have average interest rates near 21%, additional home loans typically provide lower rates. This makes them a more affordable borrowing option, especially for those looking to consolidate high-interest debts.
- Possible Tax Advantages: The interest paid on an additional loan may be tax-deductible, similar to a primary loan, offering extra relief for property owners who itemize their deductions.
- Versatile Application of Resources: Resources from an additional loan can be employed for various purposes, allowing property owners to tackle urgent financial requirements or invest in enduring projects that increase property worth, such as kitchen or bathroom upgrades, which can generate returns of 60-85% on investment.
- Enhanced Cash Flow: By merging high-interest debts into an additional loan, property owners can reduce their monthly payments and enhance their overall cash flow. For instance, merging credit card debt with an average interest rate of 21% into an additional loan at 8% can save property owners thousands in interest payments over time.
However, the risk of foreclosure looms if payments are missed, even if the primary loan is current. Furthermore, to be eligible for an additional loan, property owners generally require an acceptable credit rating (typically between 620 and 700) and adequate equity in their residence.
Experts predict that by 2026, homeowners in California, Idaho, and Nevada could access an average of $70,000 by getting a 2nd mortgage, emphasizing the economic opportunities present in these markets. Economic specialists highlight that additional loans can serve as a strategic resource for handling costs and enhancing monetary stability, as long as homeowners thoroughly evaluate their capacity to handle extra debt. Understanding both the benefits and risks of a second mortgage is crucial for making informed financial decisions that protect your home and future.
Assess the Risks: Understanding the Drawbacks of a Second Mortgage
Are you aware that second mortgages, while seemingly beneficial, can lead to severe financial pitfalls? While they can offer financial flexibility, potential borrowers must carefully consider the significant risks involved:
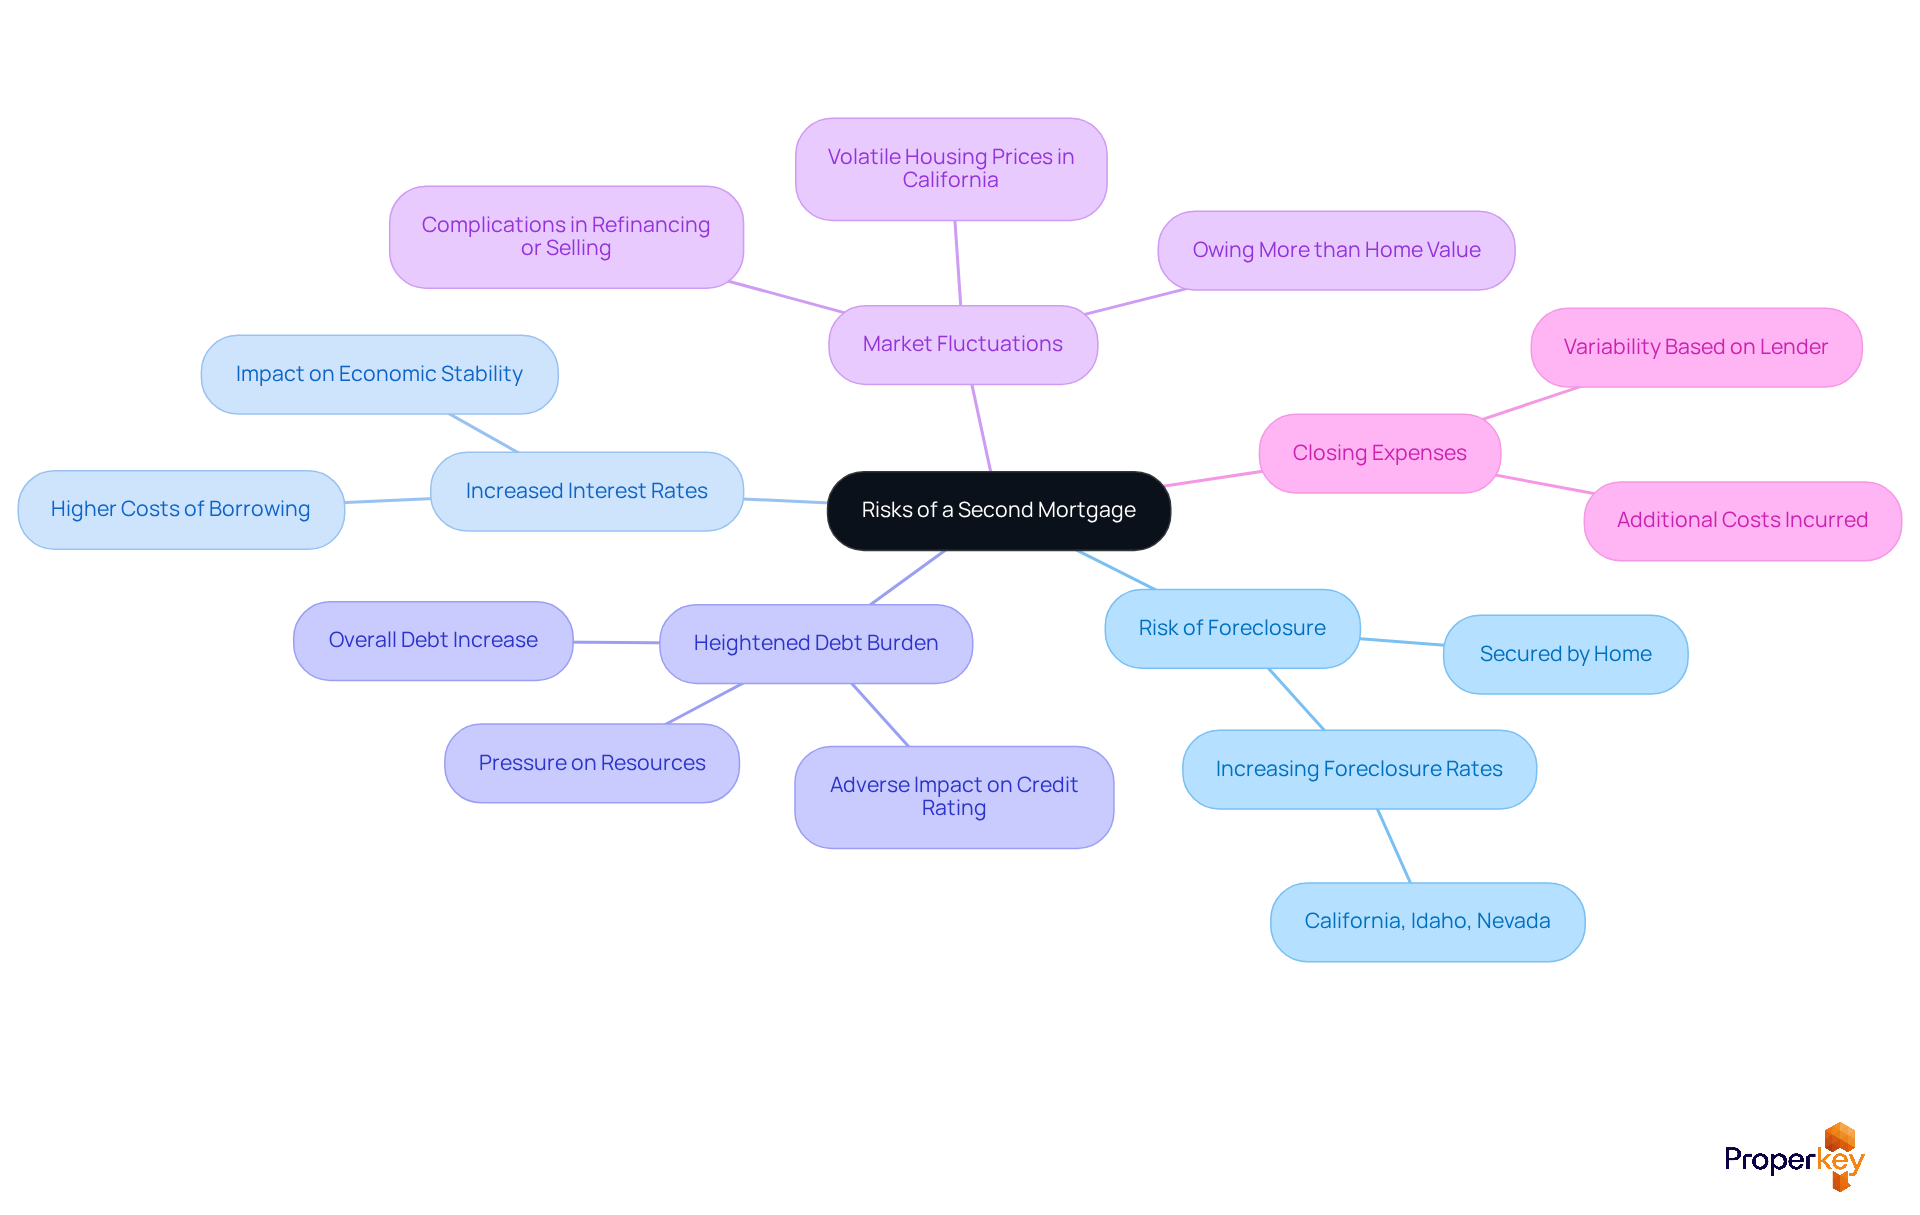
- Risk of Foreclosure: An additional loan is secured by your home, meaning that failure to make timely payments can lead to foreclosure, jeopardizing your home ownership. Recent data shows that foreclosure rates associated with additional loans are increasing in California, Idaho, and Nevada, emphasizing the urgency of this risk.
- Increased Interest Rates: Typically, additional loans carry elevated interest rates compared to primary loans, which can raise the total expense of borrowing and affect your economic stability.
- Heightened Debt Burden: Taking on an additional loan elevates your overall debt, possibly putting pressure on your resources and adversely impacting your credit rating, particularly if your economic circumstances shift.
- Market Fluctuations: In a declining real estate market, you may find yourself owing more on your loans than your home is worth, complicating future refinancing or selling efforts. This situation is particularly relevant in California, where housing prices can be volatile.
- Closing Expenses: Like any loan, additional loans incur closing expenses, which can increase the burden of obtaining the loan. Homeowners should be prepared for these additional expenses, which can vary significantly based on the lender and the specifics of the loan.
Many homeowners are surprised when they suddenly face repayment demands for dormant second mortgages, known as 'zombie' loans. These loans can resurface unexpectedly, leading to significant economic distress. For instance, homeowners may receive notices demanding large sums for these previously forgotten debts, which can be shocking and traumatic.
Without proper guidance, the allure of a second mortgage could lead you down a path of financial uncertainty that’s hard to escape. Consulting with financial advisors or housing counselors is essential for understanding the implications of getting a 2nd mortgage and navigating the associated risks effectively. The Consumer Finance Protection Bureau emphasizes the importance of seeking professional guidance to ensure informed decision-making in this complex landscape.
Conclusion
Understanding the complexities of second mortgages is crucial for homeowners aiming to leverage their property equity effectively. A second mortgage can take the form of a home equity loan or a home equity line of credit (HELOC). Both options allow you to access funds while keeping your primary mortgage intact. However, it's essential to approach this financial decision with caution. Missing payments on a second mortgage can lead to serious consequences, including foreclosure.
Key steps for obtaining a second mortgage include:
- Evaluating your home equity
- Checking your credit score
- Gathering necessary documentation
The benefits of a second mortgage, such as access to cash for home improvements or debt consolidation, are significant. Yet, the risks, including the possibility of increased debt burden and market fluctuations, cannot be overlooked. Understanding these dynamics is vital for making informed choices that align with your financial goals.
Deciding to pursue a second mortgage is a significant step that requires careful consideration. Homeowners are encouraged to consult with financial experts to navigate the complexities and ensure they are fully aware of both the opportunities and risks involved. Consulting with financial experts can transform your understanding of second mortgages, ensuring you make informed decisions. By taking informed steps, homeowners can turn the challenges of second mortgages into opportunities for financial growth.
Frequently Asked Questions
What is a second mortgage?
A second mortgage is an additional loan that allows property owners to access the equity of their home while keeping their primary mortgage. It is secured by the home, meaning failure to repay could lead to foreclosure.
What are the two main types of second mortgages?
The two main types of second mortgages are home equity loans and home equity lines of credit (HELOCs). Home equity loans provide a lump sum that is repaid over a fixed term, while HELOCs function as a revolving line of credit that allows borrowing as needed.
What are home equity loans used for?
Home equity loans are typically used for one-time expenses, as they provide a lump sum that is repaid over a fixed term.
How do HELOCs differ from home equity loans?
HELOCs differ from home equity loans in that they operate as a revolving line of credit, enabling homeowners to borrow as necessary, which is beneficial for ongoing projects or emergencies.
What are 'zombie' second mortgages?
'Zombie' second mortgages refer to dormant second mortgages that homeowners may believe are inactive but can unexpectedly resurface, leading to repayment demands and potential foreclosure.
What should homeowners consider before getting a second mortgage?
Homeowners should consult with financial experts to understand the implications of getting a second mortgage, as failing to do so could jeopardize their financial stability and home ownership.
What is the current state of second mortgage balances in the U.S.?
As of 2026, the average loan balance in the U.S. stands at $151,673, with 1.09% of these balances seriously delinquent, indicating that most borrowers are managing their payments effectively.
What recent trend has been observed regarding foreclosure activity?
There has been a rise in foreclosure activity, with 59,160 new cases reported in the first quarter of 2026, emphasizing the need for caution when considering a second mortgage.
List of Sources
- Define a Second Mortgage: Understanding the Basics
- 'Zombie' Second Mortgages Spur New Battles in California, Maryland (https://insurancejournal.com/news/west/2026/03/17/862217.htm)
- US Mortgage Statistics 2026: Debt, Delinquency and Foreclosure Data (https://lendingtree.com/home/mortgage/u-s-mortgage-market-statistics)
- New ‘second mortgage’ could help self-employed borrowers weather a recession (https://ocregister.com/2022/07/28/new-second-mortgage-could-help-self-employed-borrowers-weather-a-recession)
- "Zombie" second mortgages are back and could put your home at risk (https://kcra.com/article/zombie-second-mortgages-homeowners-foreclosure/73232213)
- Navigate the Application Process for a Second Mortgage
- New California Law on Servicing of Second Mortgages Causes Confusion Among Lenders and Servicers (https://sheppard.com/insights/blogs/new-california-law-on-servicing-of-second-mortgages-causes-confusion-among-lenders-and-servicers)
- What Is the Average Credit Score in the US? (https://experian.com/blogs/ask-experian/what-is-the-average-credit-score-in-the-u-s)
- Homeowners’ Equity Remains High | FHFA (https://fhfa.gov/blog/statistics/homeowners-equity-remains-high)
- New ‘second mortgage’ could help self-employed borrowers weather a recession (https://ocregister.com/2022/07/28/new-second-mortgage-could-help-self-employed-borrowers-weather-a-recession)
- Explore the Benefits of a Second Mortgage: Financial Opportunities
- Is a Second Mortgage Right for You? The Benefits and Pitfalls Explained - Bay Area Funding Group (https://bayareafunding.com/blog/is-a-second-mortgage-right-for-you-the-benefits-and-pitfalls-explained)
- What Is a Second Mortgage? | Riverview Bank (https://riverviewbank.com/what-is-a-second-mortgage)
- New CA and PA Laws Impact 2nds, Homeowners Deceived About PACE Liens - HELN News (https://hel.news/articles/regulation/new-ca-and-pa-laws-impact-2nds-homeowners-deceived-about-pace-liens)
- Second Mortgage in 2026: 7 Things Every Homeowner Should Know Before Tapping Home Equity (https://amerisave.com/learn/second-mortgage-in-things-every-homeowner-should-know-before-tapping-home-equity)
- Second Mortgages Are a Great Way to Access Cash—but Are They Right for You? | New American Funding (https://newamericanfunding.com/learning-center/homeowners/second-mortgages-are-a-great-way-to-access-cashbut-are-they-right-for-you)
- Assess the Risks: Understanding the Drawbacks of a Second Mortgage
- 'Zombie' Second Mortgages Spur New Battles in California, Maryland (https://insurancejournal.com/news/west/2026/03/17/862217.htm)
- 15 Ways to Fight Foreclosure of Zombie Second Mortgages | NCLC Digital Library (https://library.nclc.org/article/15-ways-fight-foreclosure-zombie-second-mortgages)
- "Zombie" second mortgages are back and could put your home at risk (https://kcra.com/article/zombie-second-mortgages-homeowners-foreclosure/73232213)
- Brown Calls for Action to Protect Homeowners from Zombie Mortgages | United States Committee on Banking, Housing, and Urban Affairs (https://banking.senate.gov/newsroom/majority/brown-action-homeowners-zombie-mortgages)
- Bloomberg: ‘Zombie’ Second Mortgages Spur New Battles in State Capitols (https://nclc.org/bloomberg-zombie-second-mortgages-spur-new-battles-in-state-capitols)