Master Home Mortgage Pre Qualification: A Step-by-Step Guide for Buyers

Introduction
Navigating the mortgage landscape can be daunting for prospective homebuyers, especially in today's competitive market. This essential step not only clarifies financial capabilities but also enhances credibility with sellers, making it a crucial part of the homebuying journey. This lack of understanding can lead to missed opportunities in securing a home. By grasping these differences, buyers can position themselves as strong contenders in the market.
Define Mortgage Pre-Qualification and Pre-Approval
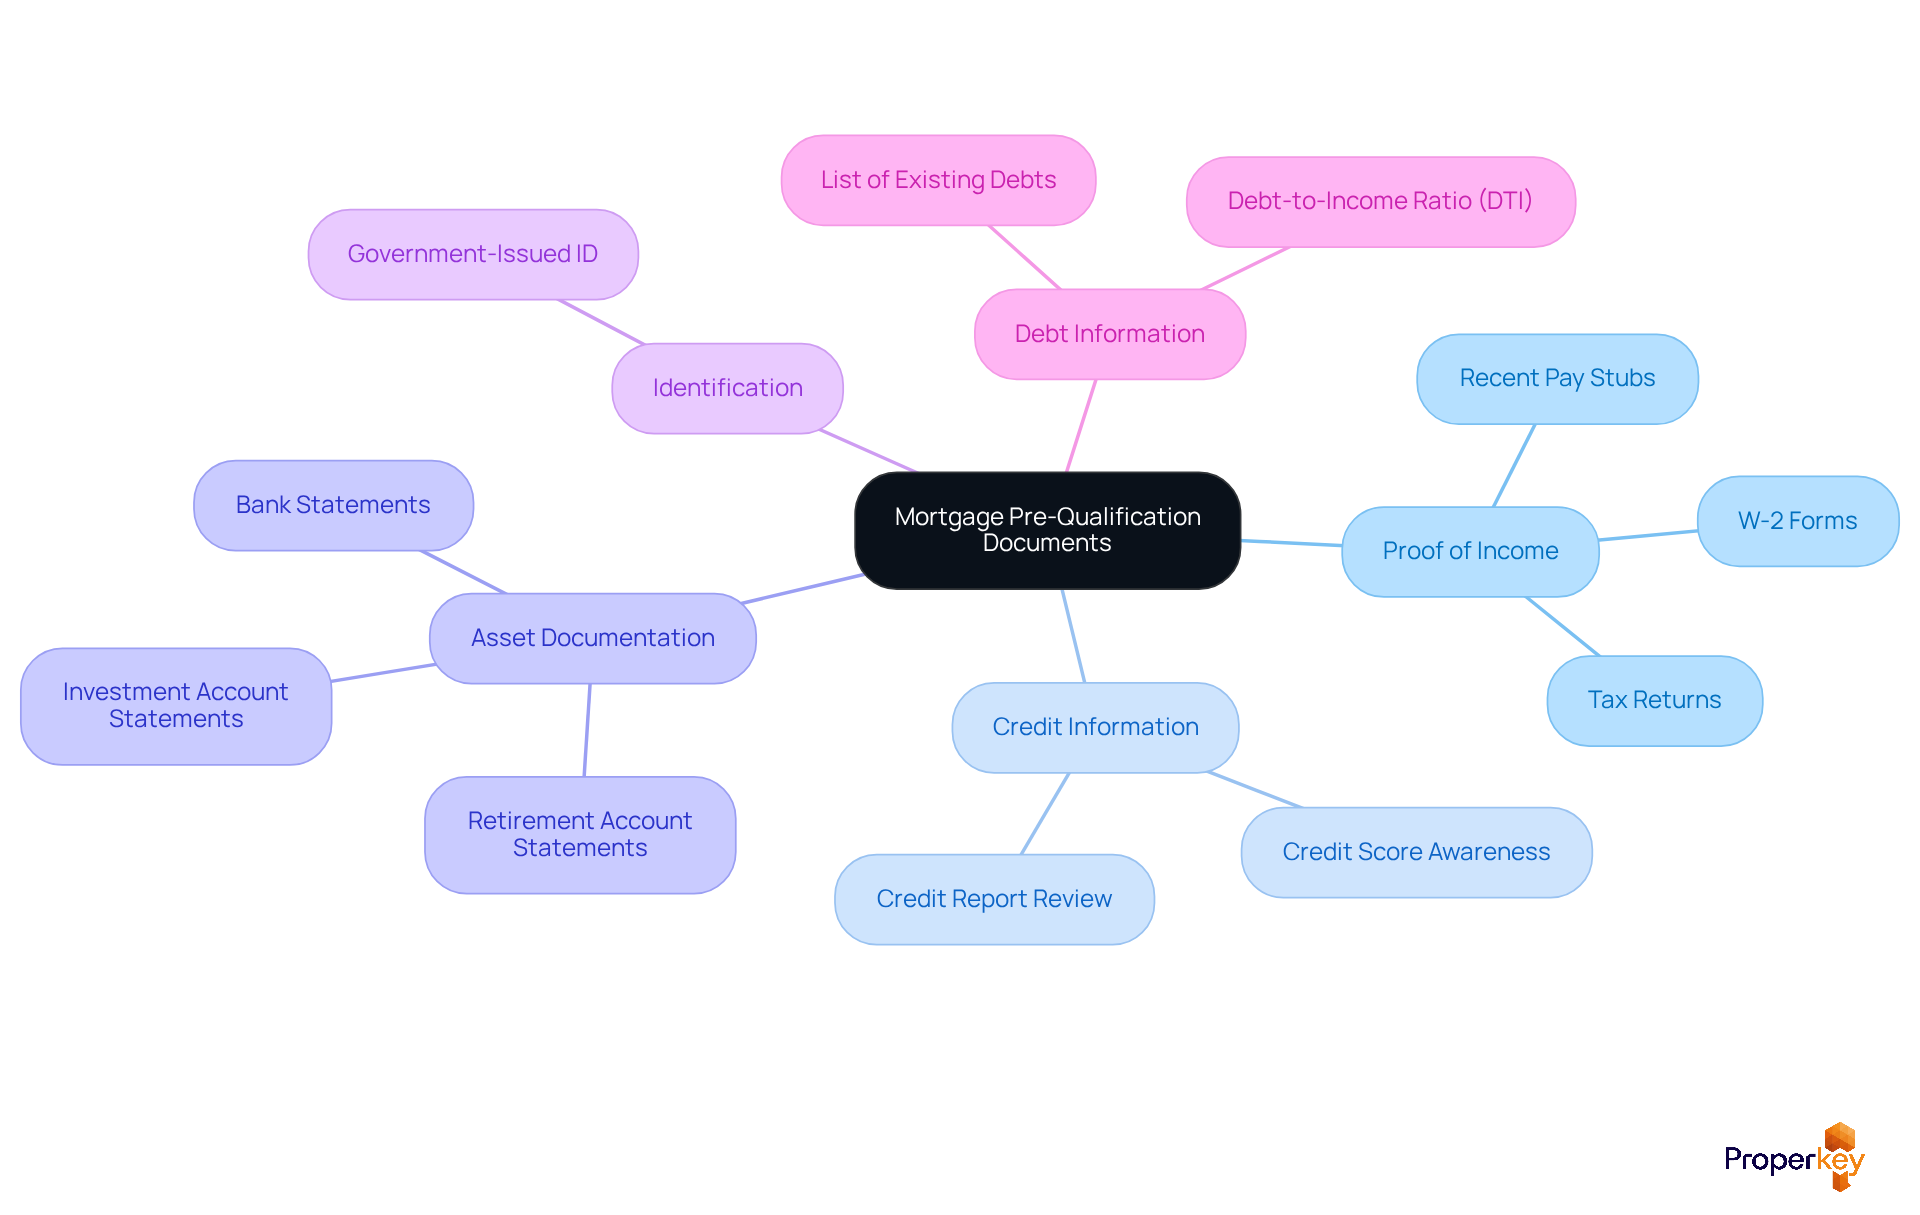
Understanding the nuances of home mortgage pre-qualification and pre-approval can be the difference between securing your dream home and missing out in a competitive market. Each step serves a unique purpose in the homebuying process:
- Mortgage Pre-Qualification: This informal estimate gives you a ballpark figure of how much you might be able to borrow based on self-reported financial information. Typically, it involves a brief conversation with a lender and doesn’t require extensive documentation. Home mortgage pre-qualification is an excellent starting point for purchasers to gauge their budget and understand their borrowing potential.
- Mortgage Pre-Approval: In contrast, pre-approval is a formal process where the lender verifies your financial information, including credit score, income, and debts. This step requires documentation such as pay stubs, tax returns, and bank statements. A pre-approval letter indicates that the lender is prepared to provide you with a specific sum, increasing your appeal as a purchaser to sellers.
Navigating the mortgage landscape can feel overwhelming, especially when competing offers flood the market. Comprehending these differences is essential for individuals looking to secure a home. For example, in competitive markets like California, sellers frequently favor proposals from pre-approved purchasers, as it signifies financial preparedness and minimizes the risk of financing problems. A case study highlighted that individuals with pre-approval were able to secure homes even against higher competing offers, demonstrating the significant advantage it provides.
With Vana's streamlined loan qualification system, you can qualify in just a few minutes and receive your Loan Qualification Letter promptly. For those seeking a stronger assurance, a full Loan Approval Letter is available for free upon qualification. This efficiency is a game-changer in a market where great homes can disappear in the blink of an eye. Additionally, Vana utilizes transparent, up-to-date, and publicly accessible resources, including Fannie Mae and Freddie Mac guidelines, to ensure you have the most accurate information. As of 2026, the average 30-year fixed mortgage rate is approximately 6%, lower than recent highs, and pre-approval can accelerate the final loan processing, making it a strategic decision for individuals looking to act quickly. By prioritizing pre-approval, you’re not just preparing to buy; you’re positioning yourself for success in a fast-paced real estate environment.
Gather Necessary Documentation for Pre-Qualification
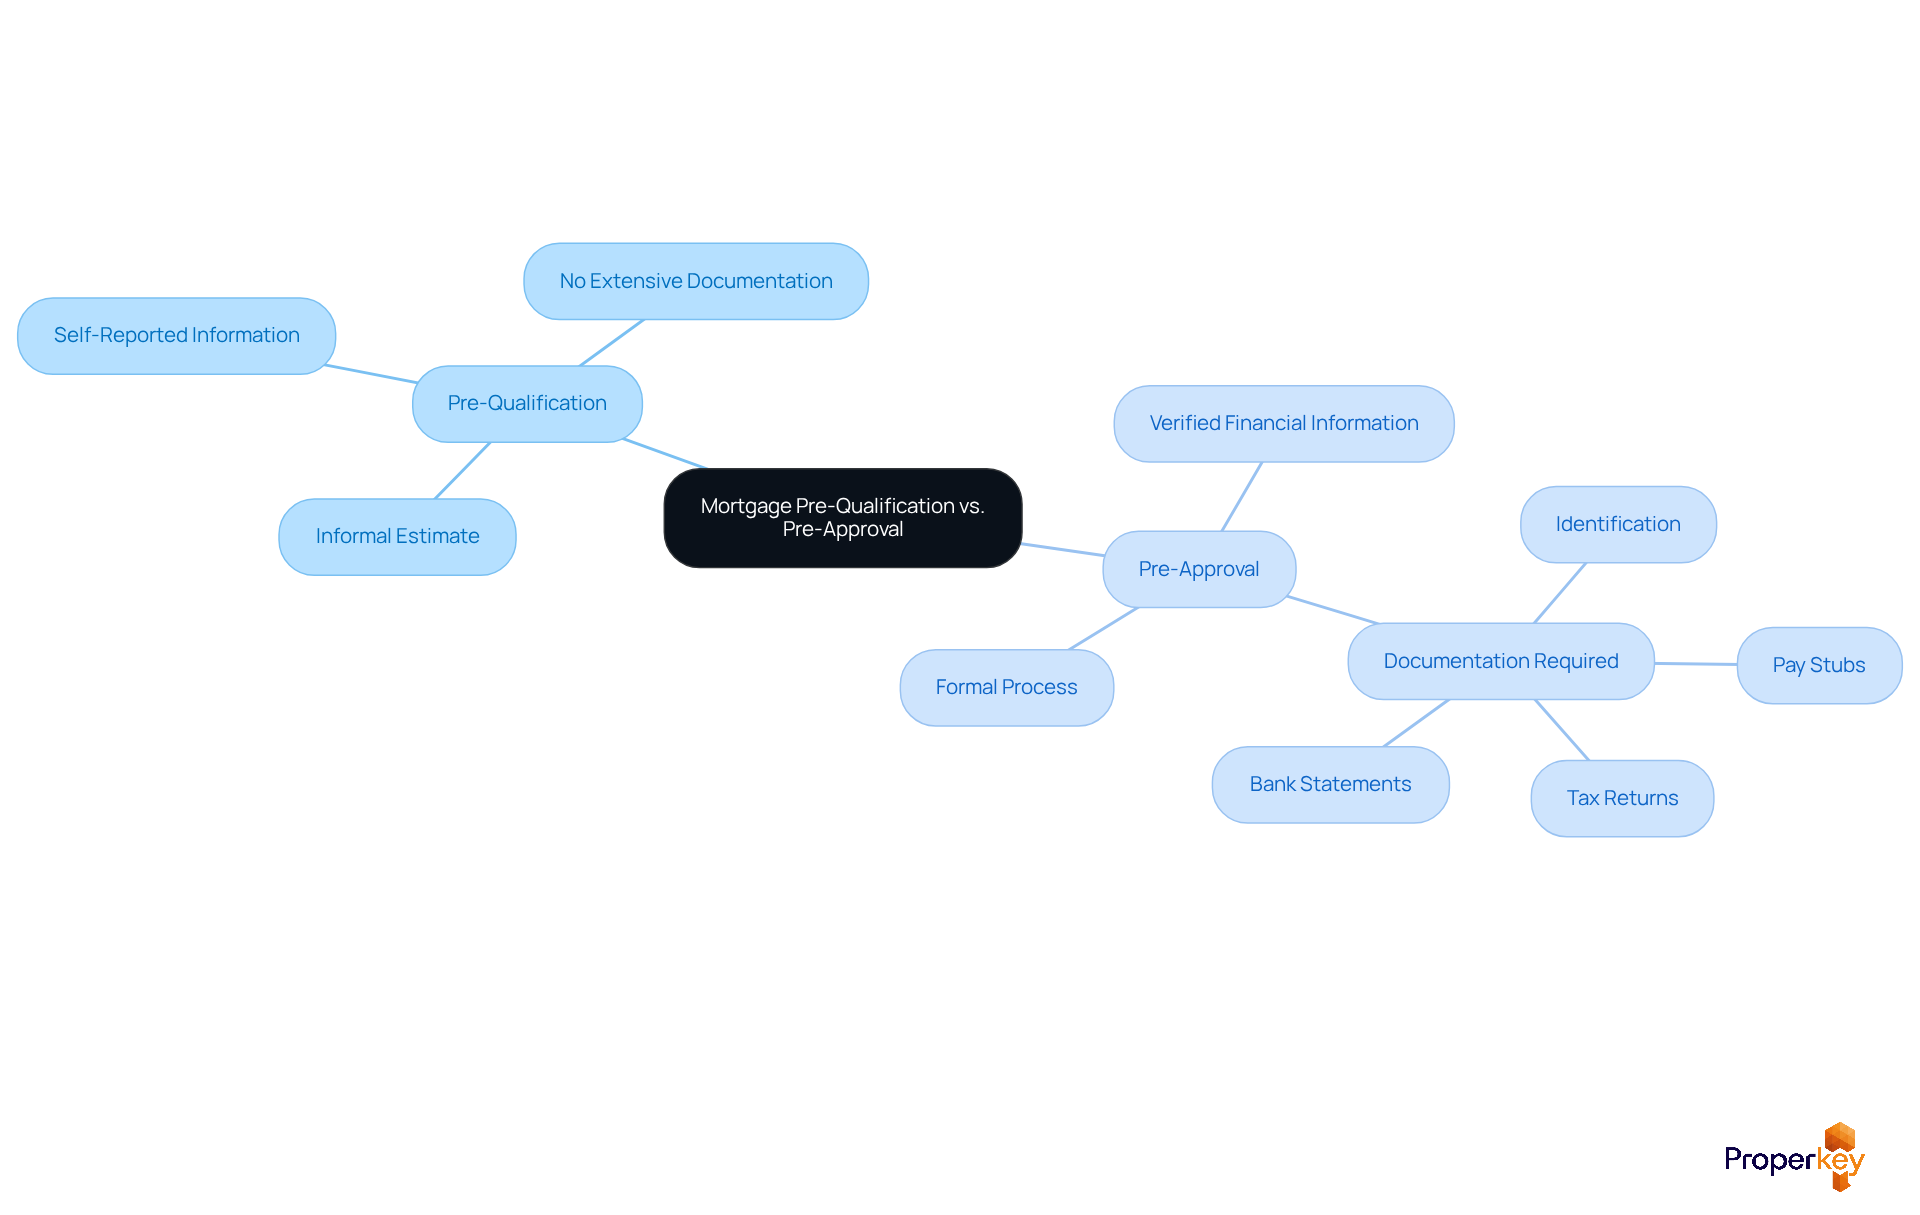
Navigating the home mortgage pre-qualification process can feel daunting without the right preparation, but having the right documents can make all the difference. To successfully obtain a mortgage pre-qualification, gather the following key documents:
- Proof of Income: Include recent pay stubs from the last 30 days, W-2 forms from the past two years, and, if self-employed, tax returns for the last two years.
- Credit Information: While lenders will pull your credit report, knowing your credit score in advance can help identify any issues that may need addressing.
- Asset Documentation: Provide bank statements for checking and savings accounts, investment accounts, and any other assets that demonstrate your economic stability, typically covering the last two to three months.
- Identification: A government-issued ID, such as a driver’s license or passport, is necessary to verify your identity.
- Debt Information: Compile a list of existing debts, including credit cards, student loans, and other loans, to help the lender assess your debt-to-income ratio (DTI).
When you organize these documents ahead of time, you’ll find that the process of home mortgage pre-qualification becomes much smoother and more efficient. Understanding your DTI is crucial, as lenders typically prefer a ratio below 36% for conventional loans. Additionally, if you have a history of on-time rent payments, this can further demonstrate your financial responsibility, especially for first-time homebuyers.
In competitive markets like California, Idaho, and Nevada, being prepared with these documents not only speeds up the process but also shows sellers you mean business, boosting your chances of landing your dream home.
Understand the Impact of Pre-Qualification on Homebuying
In California's fast-paced housing market, navigating the complexities of home buying can feel overwhelming, especially without mortgage pre-qualification. Here are the key benefits:
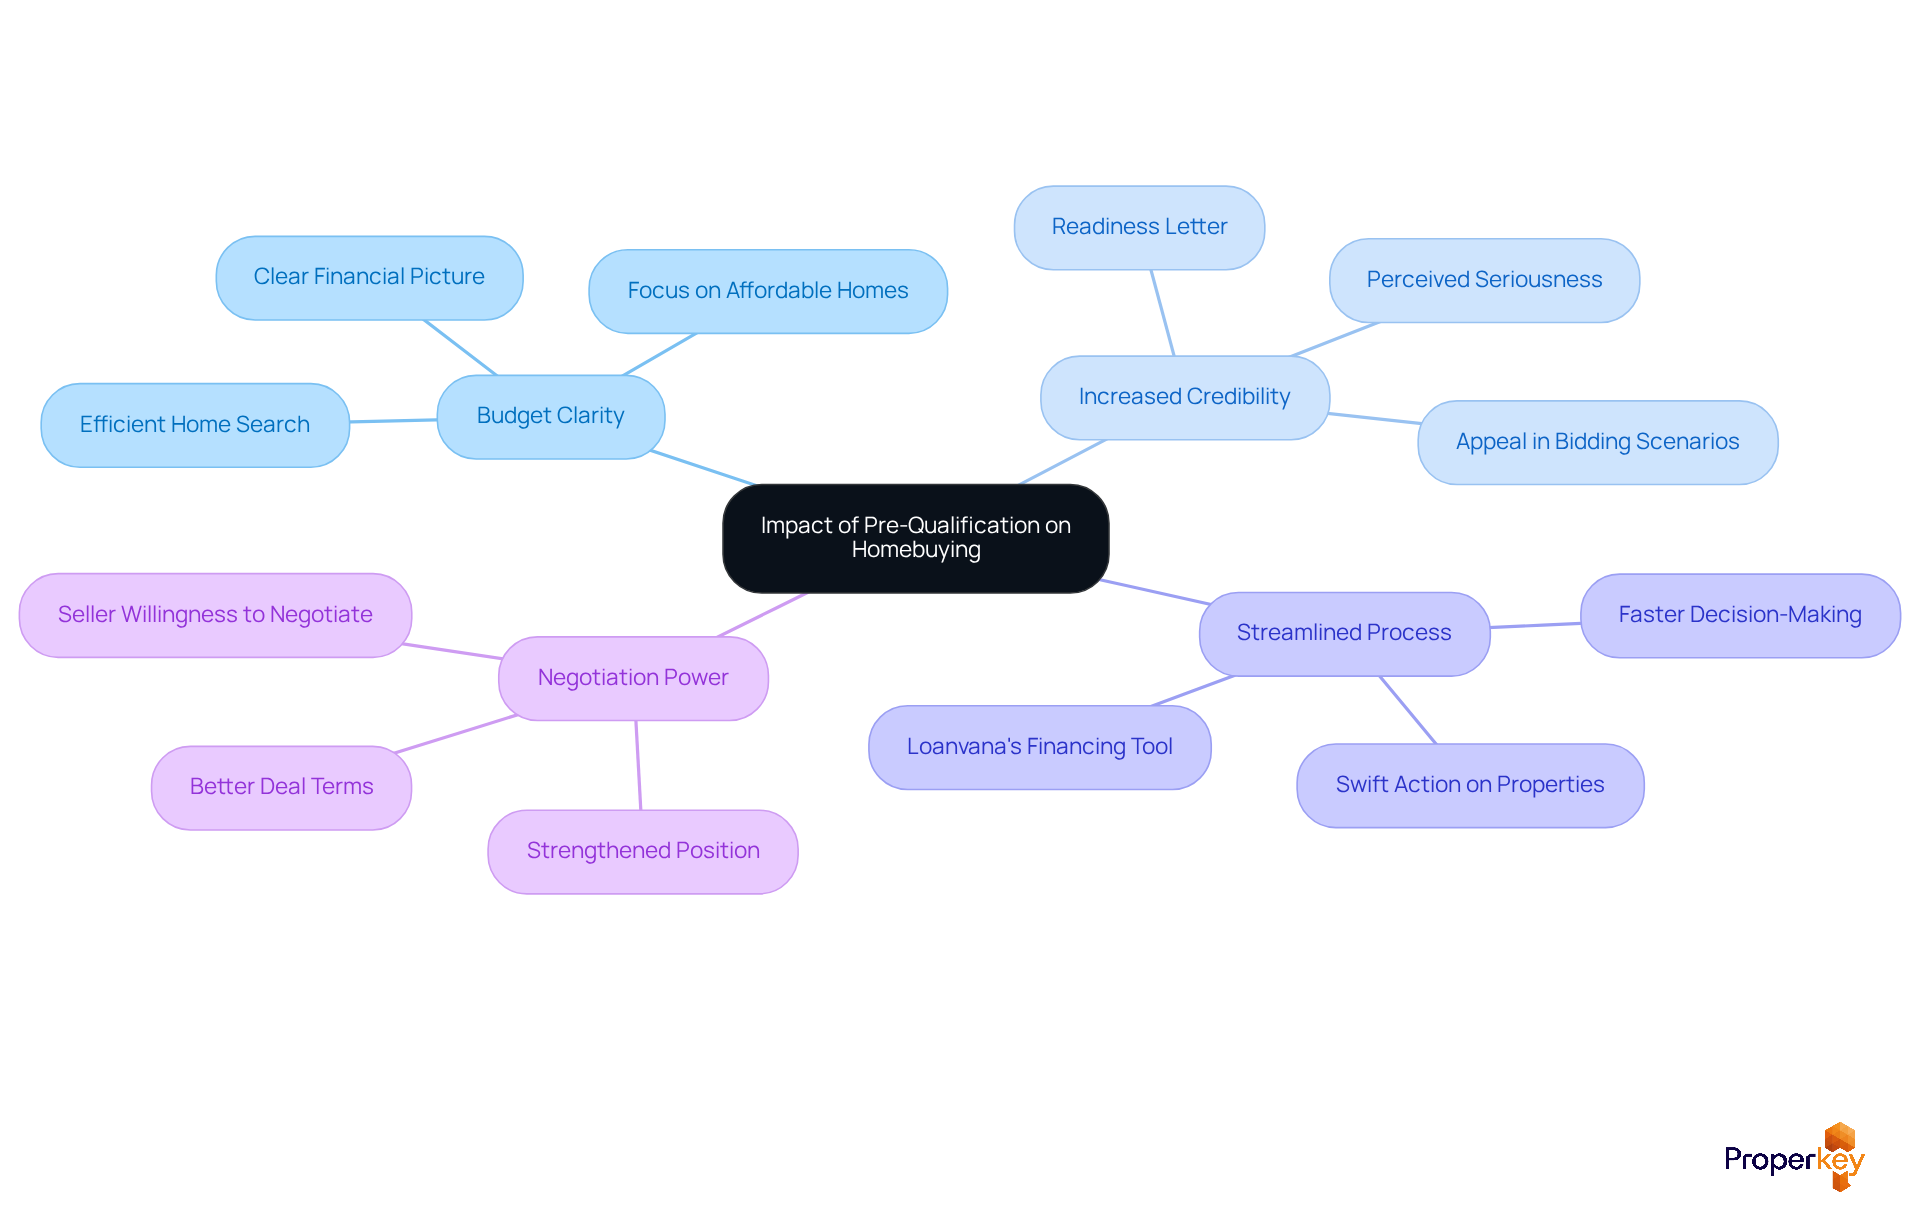
- Budget Clarity: Pre-qualification offers a clearer picture of your financial capacity, enabling you to focus on homes within your budget. This way, you won't waste time on homes that are out of reach, allowing for a more efficient home search.
- Increased Credibility: Sellers often perceive pre-qualified buyers as more serious and committed. A readiness letter shows your monetary preparedness, increasing your appeal in competitive bidding scenarios.
- Streamlined Process: With prior assessment, you can act swiftly when you find a desirable property. Understanding your budgetary limits enables faster decision-making and accelerates the offer process, which is essential in rapidly changing markets. Additionally, Loanvana's financing tool allows you to apply once and compare hundreds of loan options side-by-side from multiple lenders, further simplifying your financing journey.
- Negotiation Power: Being pre-qualified strengthens your negotiating position. Sellers are more inclined to negotiate with buyers who have demonstrated financial readiness through prior qualification, potentially leading to better deal terms.
Overall, mortgage pre-approval is a strategic step that significantly enhances your homebuying experience, particularly in California's dynamic real estate landscape. For example, first-time homebuyers who obtain prior approval often find themselves better prepared to navigate the complexities of the market, resulting in higher success rates in acquiring their desired homes. By securing pre-qualification, you not only enhance your buying power but also position yourself for success in a market that waits for no one.
Debunk Common Myths About Mortgage Pre-Qualification
In California's competitive housing market, many potential buyers are misled by common myths surrounding mortgage pre-qualification:
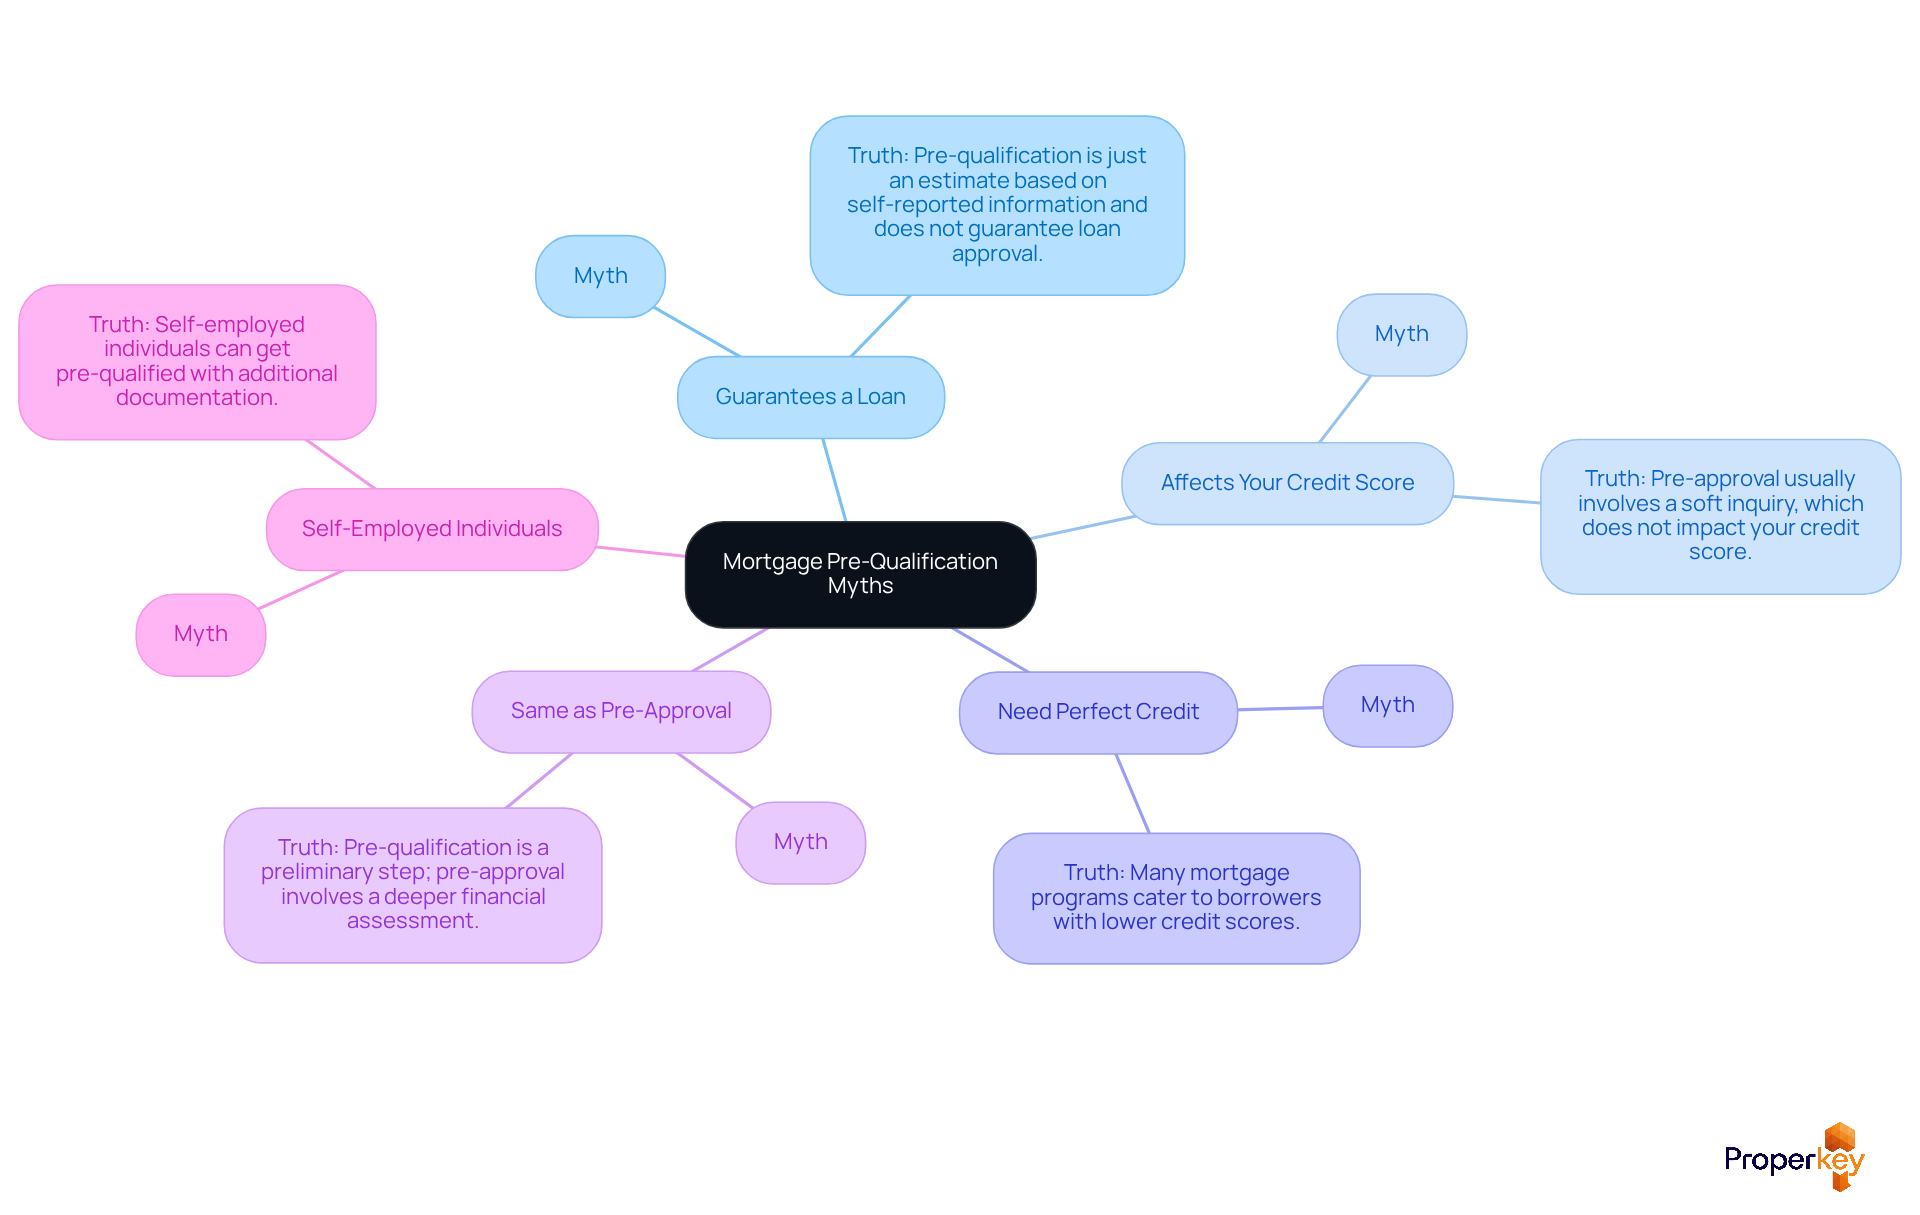
- Myth: Pre-Qualification Guarantees a Loan: Many buyers think that getting pre-qualified is a guaranteed ticket to a mortgage, but that's not the case. In reality, this initial assessment is just an estimate. It relies on self-reported information and doesn’t guarantee loan approval.
- Myth: Pre-Approval Affects Your Credit Score: Some buyers worry that obtaining pre-approval will hurt their credit score. The truth is, this process usually involves a soft inquiry, which doesn’t impact your credit score.
- Myth: You Need Perfect Credit to Get Pre-Qualified: Many people think that only those with stellar credit can get pre-qualified, but that’s a myth. Lenders look at various factors, and many mortgage programs cater to borrowers with lower credit scores, making homeownership more attainable.
- Myth: Pre-Qualification is the Same as Pre-Approval: This misunderstanding is common among homebuyers. Pre-qualification is just a preliminary step, while pre-approval involves a deeper dive into your financial situation, giving you a clearer picture of your borrowing potential.
- Myth: Self-Employed Individuals Cannot Get Pre-Qualified: Self-employed individuals can absolutely get pre-qualified. They just need to provide some extra documentation, like tax returns and profit-loss statements.
By debunking these myths, potential buyers can approach the pre-qualification process with greater confidence and clarity. Understanding these facts is crucial as you navigate the complexities of California's housing market. By understanding these myths, you can confidently navigate the mortgage landscape and take the first step toward homeownership in California.
Conclusion
Navigating the mortgage pre-qualification process can be daunting for prospective homebuyers, yet it is a crucial step in securing your dream home. By understanding the differences between pre-qualification and pre-approval, you can position yourself more effectively in the competitive real estate market. This foundational step clarifies your financial capabilities and enhances your credibility with sellers, making it essential in your homebuying journey.
Throughout this article, we’ve shared key insights, including:
- The importance of gathering necessary documentation
- How pre-qualification impacts budgeting and negotiation
- Debunking common myths that often mislead buyers
By preparing the right documents and grasping the true nature of pre-qualification, you can streamline your home search and significantly increase your chances of success in a fast-paced market.
In the end, getting pre-qualified isn’t just a box to check; it’s a powerful tool that helps buyers make smart choices and seize opportunities quickly. Embracing this process not only boosts your buying power but also fosters confidence as you navigate the complexities of homeownership. In a competitive market, being pre-qualified can mean the difference between landing your dream home and watching it slip away.
Frequently Asked Questions
What is mortgage pre-qualification?
Mortgage pre-qualification is an informal estimate that gives you a rough idea of how much you might be able to borrow based on self-reported financial information. It typically involves a brief conversation with a lender and does not require extensive documentation.
What is mortgage pre-approval?
Mortgage pre-approval is a formal process where the lender verifies your financial information, including credit score, income, and debts. This step requires documentation such as pay stubs, tax returns, and bank statements, and results in a pre-approval letter indicating the specific sum the lender is prepared to provide.
Why is pre-approval important in a competitive housing market?
In competitive markets, sellers often prefer offers from pre-approved purchasers because it signifies financial preparedness and reduces the risk of financing issues. Pre-approval can give buyers a significant advantage, as demonstrated by cases where pre-approved individuals secured homes even against higher competing offers.
How can Vana assist with mortgage qualification?
Vana offers a streamlined loan qualification system that allows you to qualify in just a few minutes and receive your Loan Qualification Letter promptly. They also provide a full Loan Approval Letter for free upon qualification, enhancing your readiness in a fast-paced market.
What resources does Vana use to ensure accurate information?
Vana utilizes transparent, up-to-date, and publicly accessible resources, including Fannie Mae and Freddie Mac guidelines, to ensure that you have the most accurate information regarding mortgage qualifications.
What is the average mortgage rate as of 2026?
As of 2026, the average 30-year fixed mortgage rate is approximately 6%, which is lower than recent highs.
How does pre-approval affect the loan processing time?
Pre-approval can accelerate the final loan processing, making it a strategic decision for individuals looking to act quickly in the real estate market.
List of Sources
- Define Mortgage Pre-Qualification and Pre-Approval
- Understanding Pre-Approval vs. Pre-Qualification (https://newrez.com/blog/mortgage-101/understanding-pre-approval-vs-pre-qualification)
- A Competitive Edge: Why You Need a Pre-Approval Letter in a Hot Housing Market | New American Funding (https://newamericanfunding.com/learning-center/homebuyers/a-competitive-edge-why-you-need-a-pre-approval-letter-in-a-hot-housing-market)
- Why Get Pre-Approved for a Mortgage? 5 Questions Answered. (https://apgfcu.com/post/why_get_preapproved_for_a_mortgage_5_questions_answered.html)
- Mortgage Pre-Qualification vs. Pre-Approval: What’s the Difference? (https://psbt.com/Learn/Resources/PSBT-Corner-News/mortgage-pre-qualification-vs-pre-approval)
- Why Mortgage Pre-Approval Matters Before the Spring Market - Integrity Home Mortgage (https://ihmcloans.com/mortgage-pre-approval-spring-housing-market)
- Gather Necessary Documentation for Pre-Qualification
- The Complete Mortgage Preapproval Checklist for 2026 (https://sistarmortgage.com/blog/mortgage-preapproval-checklist)
- Documents Needed For Mortgage Preapproval | Bankrate (https://bankrate.com/mortgages/documents-for-preapproval)
- What Documents Are Needed for a Mortgage Preapproval? (https://experian.com/blogs/ask-experian/what-documents-are-needed-for-mortgage-preapproval)
- What’s needed for a pre-approval application? (https://guildmortgage.com/blog/whats-needed-for-a-pre-approval-application)
- Your Mortgage Pre-Approval Checklist (https://credible.com/mortgage/mortgage-preapproval-documents)
- Understand the Impact of Pre-Qualification on Homebuying
- Mortgage Pre-Approval in California (https://sammamishmortgage.com/mortgage-pre-approval-ca)
- Mortgage Pre-Approval vs. Pre-Qualification: What's the Difference? | CU SoCal (https://cusocal.org/resources/blog/whats-the-difference-between-mortgage-pre-approval-and-pre-qualification)
- Mortgage Prequalification vs. Preapproval - Understanding the Difference (https://bankofamerica.com/mortgage/learn/mortgage-prequalification)
- Mortgage Pre-Approval in California: Why It Matters Before You Shop (https://uslendingcompany.com/blog/mortgage-pre-approval-in-california)
- California Housing Affordability Tracker (2nd Quarter 2026) [EconTax Blog] (https://lao.ca.gov/LAOEconTax/Article/Detail/793)
- Debunk Common Myths About Mortgage Pre-Qualification
- 6 Mortgage Myths to Leave in 2025 (https://thefederalsavingsbank.com/Blog/6-mortgage-myths-to-leave-in-2025)
- 5 Mortgage Myths Debunked: What You Need to Know - PMR Loans (https://pmrloans.com/5-mortgage-myths-debunked-what-you-need-to-know)
- 5 Common Mortgage Myths Debunked | First Bank (https://localfirstbank.com/article/5-common-mortgage-myths-debunked)
- Mortgage myths debunked | Mortgage tips | Citizens (https://citizensbank.com/learning/mortgage-myth-debunked.aspx)
- Common Mortgage Myths Debunked - Federal First Lending LLC (https://federalfirstlending.com/common-mortgage-myths-debunked)