Master Mortgage Affordability: Key Factors and Strategies for Buyers

Introduction
Many prospective home buyers find themselves lost in the complexities of mortgage affordability, a crucial factor in their journey to homeownership.
With fluctuating interest rates and economic factors influencing borrowing costs, navigating this landscape can be daunting.
Let’s explore the key elements that shape mortgage affordability and discover strategies that empower buyers to secure the best rates and make informed decisions.
Understanding these elements is not just beneficial; it’s essential for making informed decisions that can significantly impact your financial future.
Explain How Mortgage Rates Work
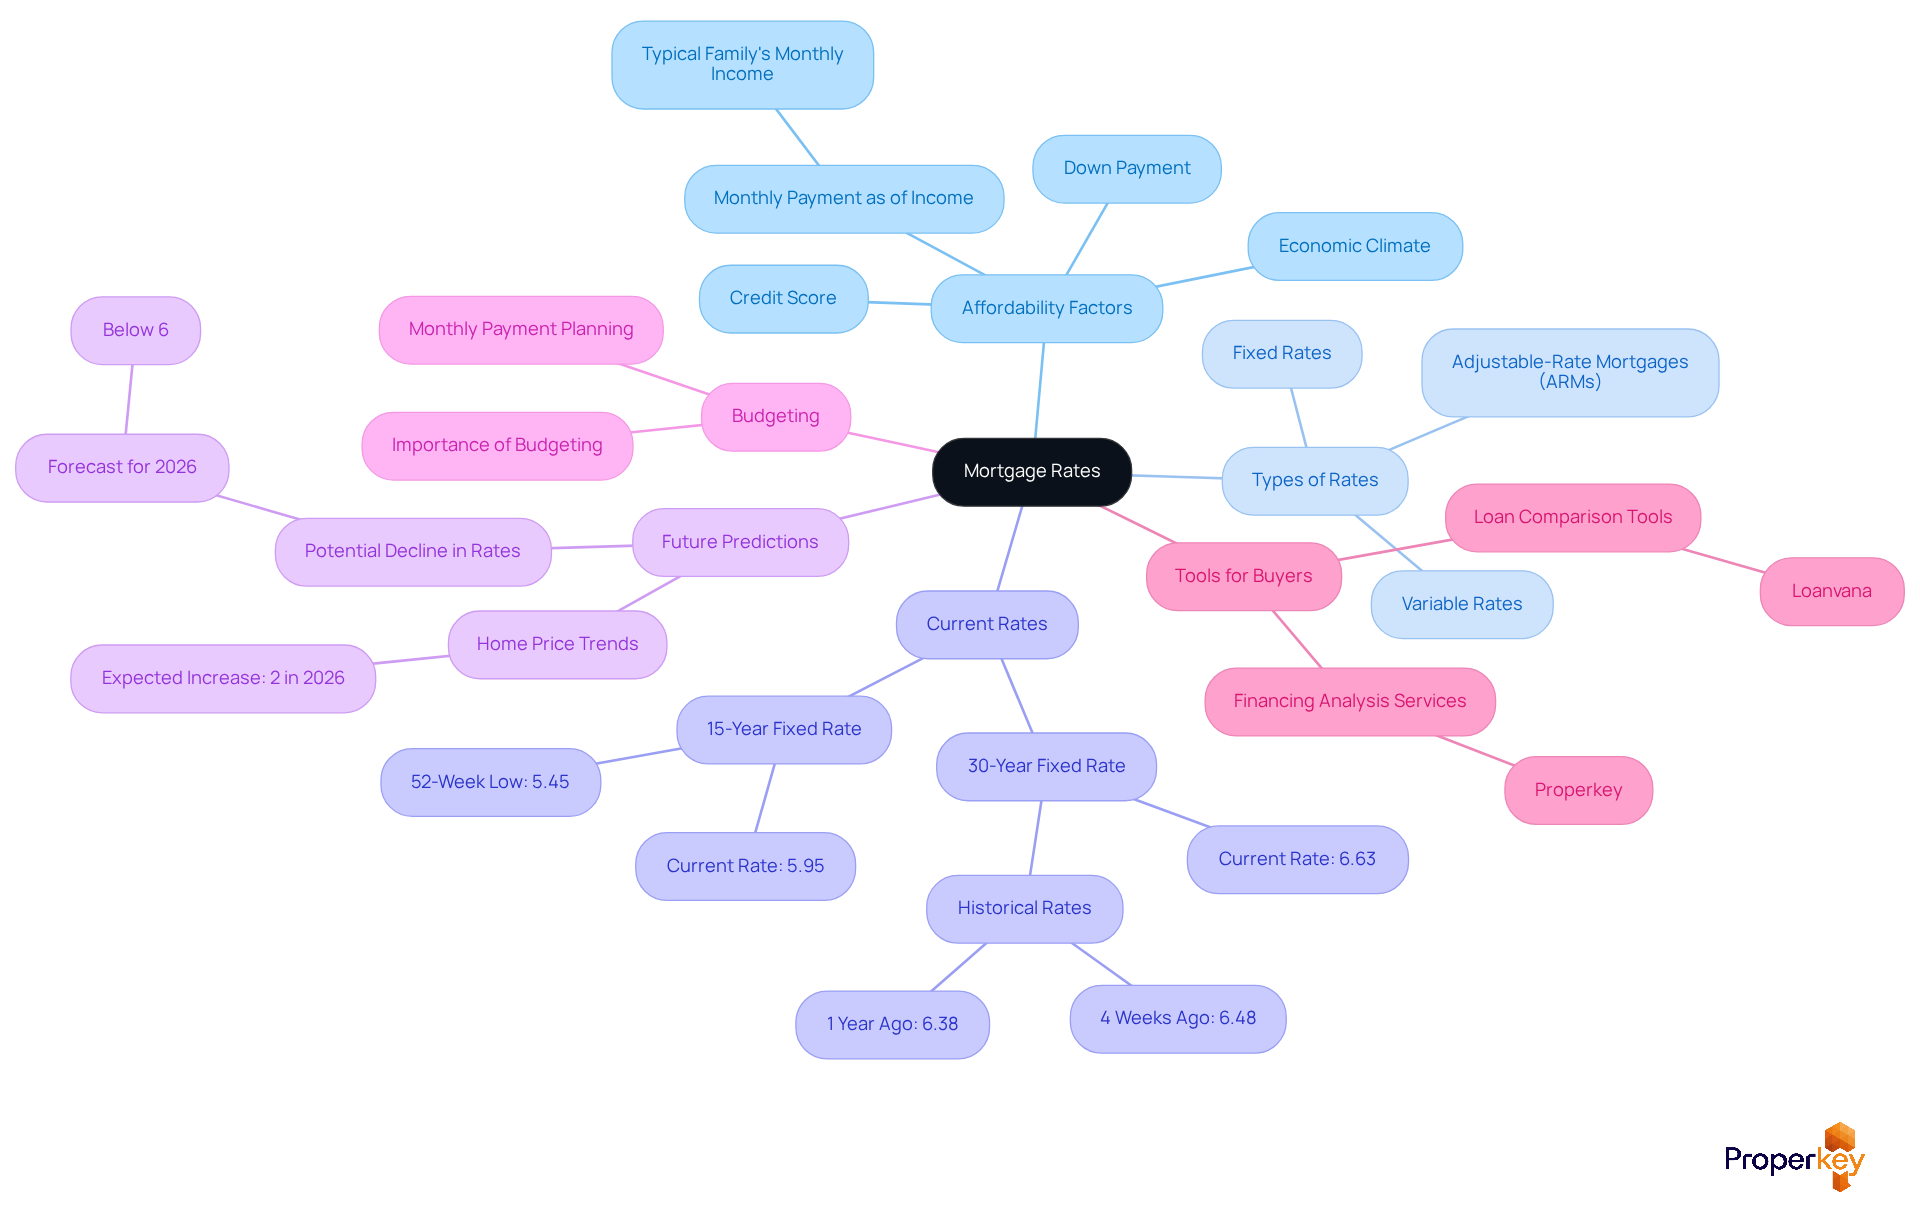
Understanding what makes a mortgage affordable is crucial for home buyers, yet many find it daunting. Mortgage costs represent the price of borrowing money to purchase a home, and ensuring that the mortgage is affordable is typically expressed as a percentage of the loan amount. You might encounter fixed charges that stay the same or variable ones that change with the market. Your mortgage amount depends on factors like your credit score, down payment size, and the economic climate. For instance, the current average interest rate for a 30-year fixed loan is around 6.63%, while the 15-year rate is approximately 5.95%.
Navigating the complexities of mortgage costs can feel like a maze for many buyers. Changes in the Federal Reserve's interest rates can significantly impact loan costs, affecting monthly payments for borrowers. As inflation eases, experts predict that mortgage costs may gradually decline, making it easier for buyers to find mortgage affordable options, potentially dropping below 6% by 2026. This potential decline in costs could make homeownership more accessible by making mortgage affordable for more families. It's essential for buyers to understand how these figures work to effectively plan their financial obligations.
Typically, the monthly principal and interest payment accounts for about 25% of a typical family's monthly income, highlighting the importance of careful budgeting to make the mortgage affordable when considering home purchases. To assist buyers, Properkey offers a complimentary financing analysis service, enabling them to explore their options before committing. Additionally, tools like Loanvana's financing solution allow buyers to apply once and compare hundreds of loan options side-by-side from various providers. This streamlines the decision-making process and ensures they obtain the best offers available. With the right tools and knowledge, buyers can confidently navigate their mortgage options and secure their dream home.
Identify Factors Influencing Mortgage Rates
Understanding the factors that influence mortgage rates is essential for any buyer navigating the complexities of the housing market. Here are several key elements to consider:
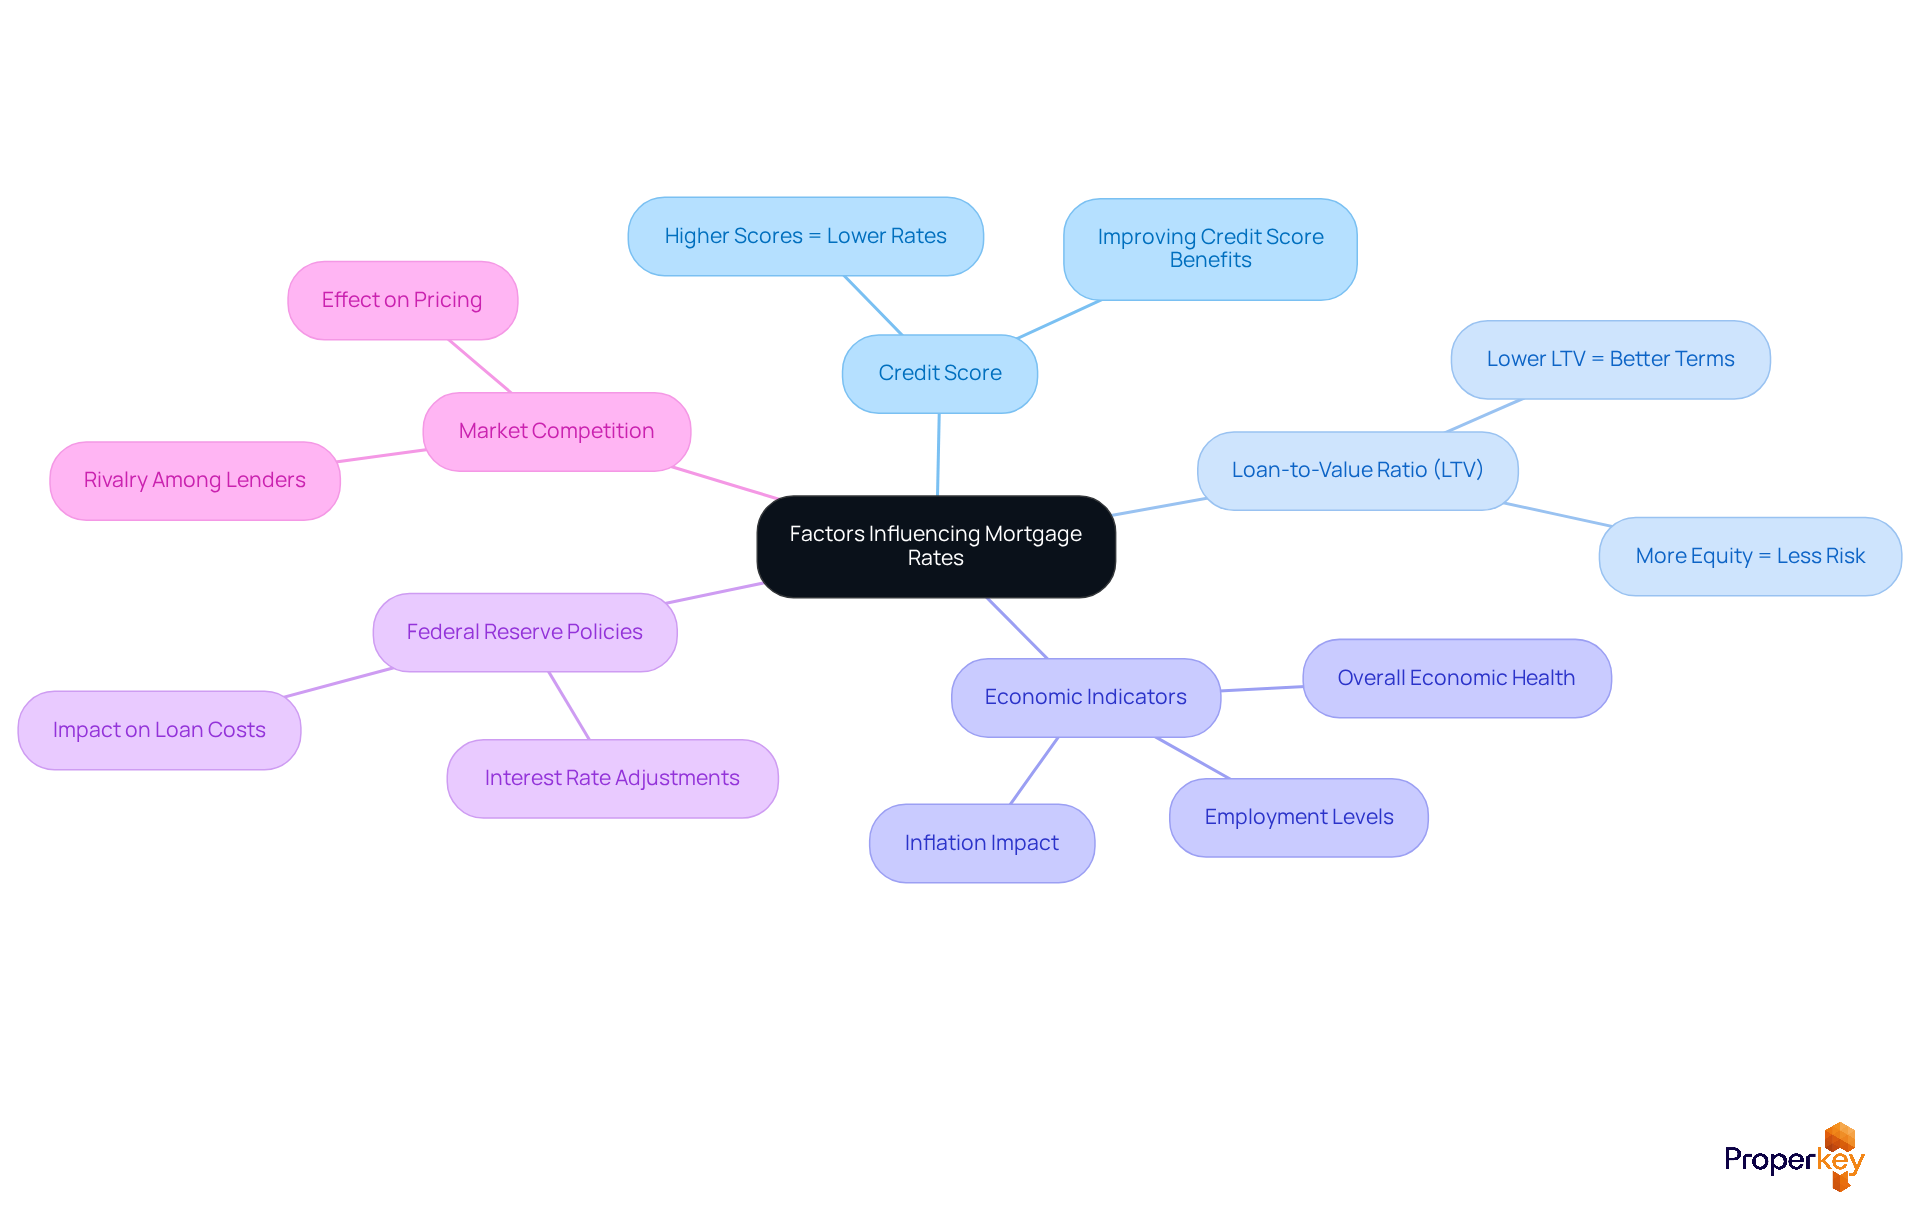
- Credit Score: A higher credit score typically results in lower interest rates, as lenders perceive borrowers with strong credit histories as less risky. For example, enhancing your credit score can greatly reduce your home loan interest, making it easier to achieve a mortgage affordable and homeownership more budget-friendly. Experts suggest that improving your credit score can lead to better mortgage terms, as lenders view higher scores as lower risk.
- Loan-to-Value Ratio (LTV): A lower LTV, which signifies more equity in the home, can result in improved terms. Lenders often reward borrowers who invest more upfront, reducing their perceived risk. For instance, a lower LTV can assist in obtaining a more advantageous interest level, which can make the mortgage affordable.
- Economic Indicators: Factors such as inflation, employment levels, and overall economic health can cause variations in loan costs. High inflation frequently results in higher borrowing expenses, as lenders modify charges to reduce risk. Currently, inflation remains high, which is a major element affecting loan costs.
- Federal Reserve Policies: Adjustments in the federal funds interest directly influence home loan costs. When the Fed increases interest levels to tackle inflation, loan costs generally align, which impacts how mortgage affordable it is for prospective purchasers. Experts predict that a 0.25% drop in rates by 2026 could create new opportunities for buyers.
- Market Competition: The number of financial institutions and the demand for mortgages can also affect prices. Heightened rivalry among lenders frequently leads to reduced costs, aiding borrowers in finding the best offer. Jeff Judge, a financial advisor, warns that waiting for lower prices can be a gamble in today’s market, especially in a constrained inventory environment where missed opportunities can be costly.
Understanding these factors is vital for making informed decisions in California's housing market. They can significantly impact how mortgage affordable your buying capacity is. As of Q2 2023, the average 30-year fixed loan percentage was 5.87%, and experts anticipate percentages to remain around 6% to 6.4% in 2026, emphasizing the significance of staying updated on these trends.
Outline Strategies to Secure the Best Mortgage Rates
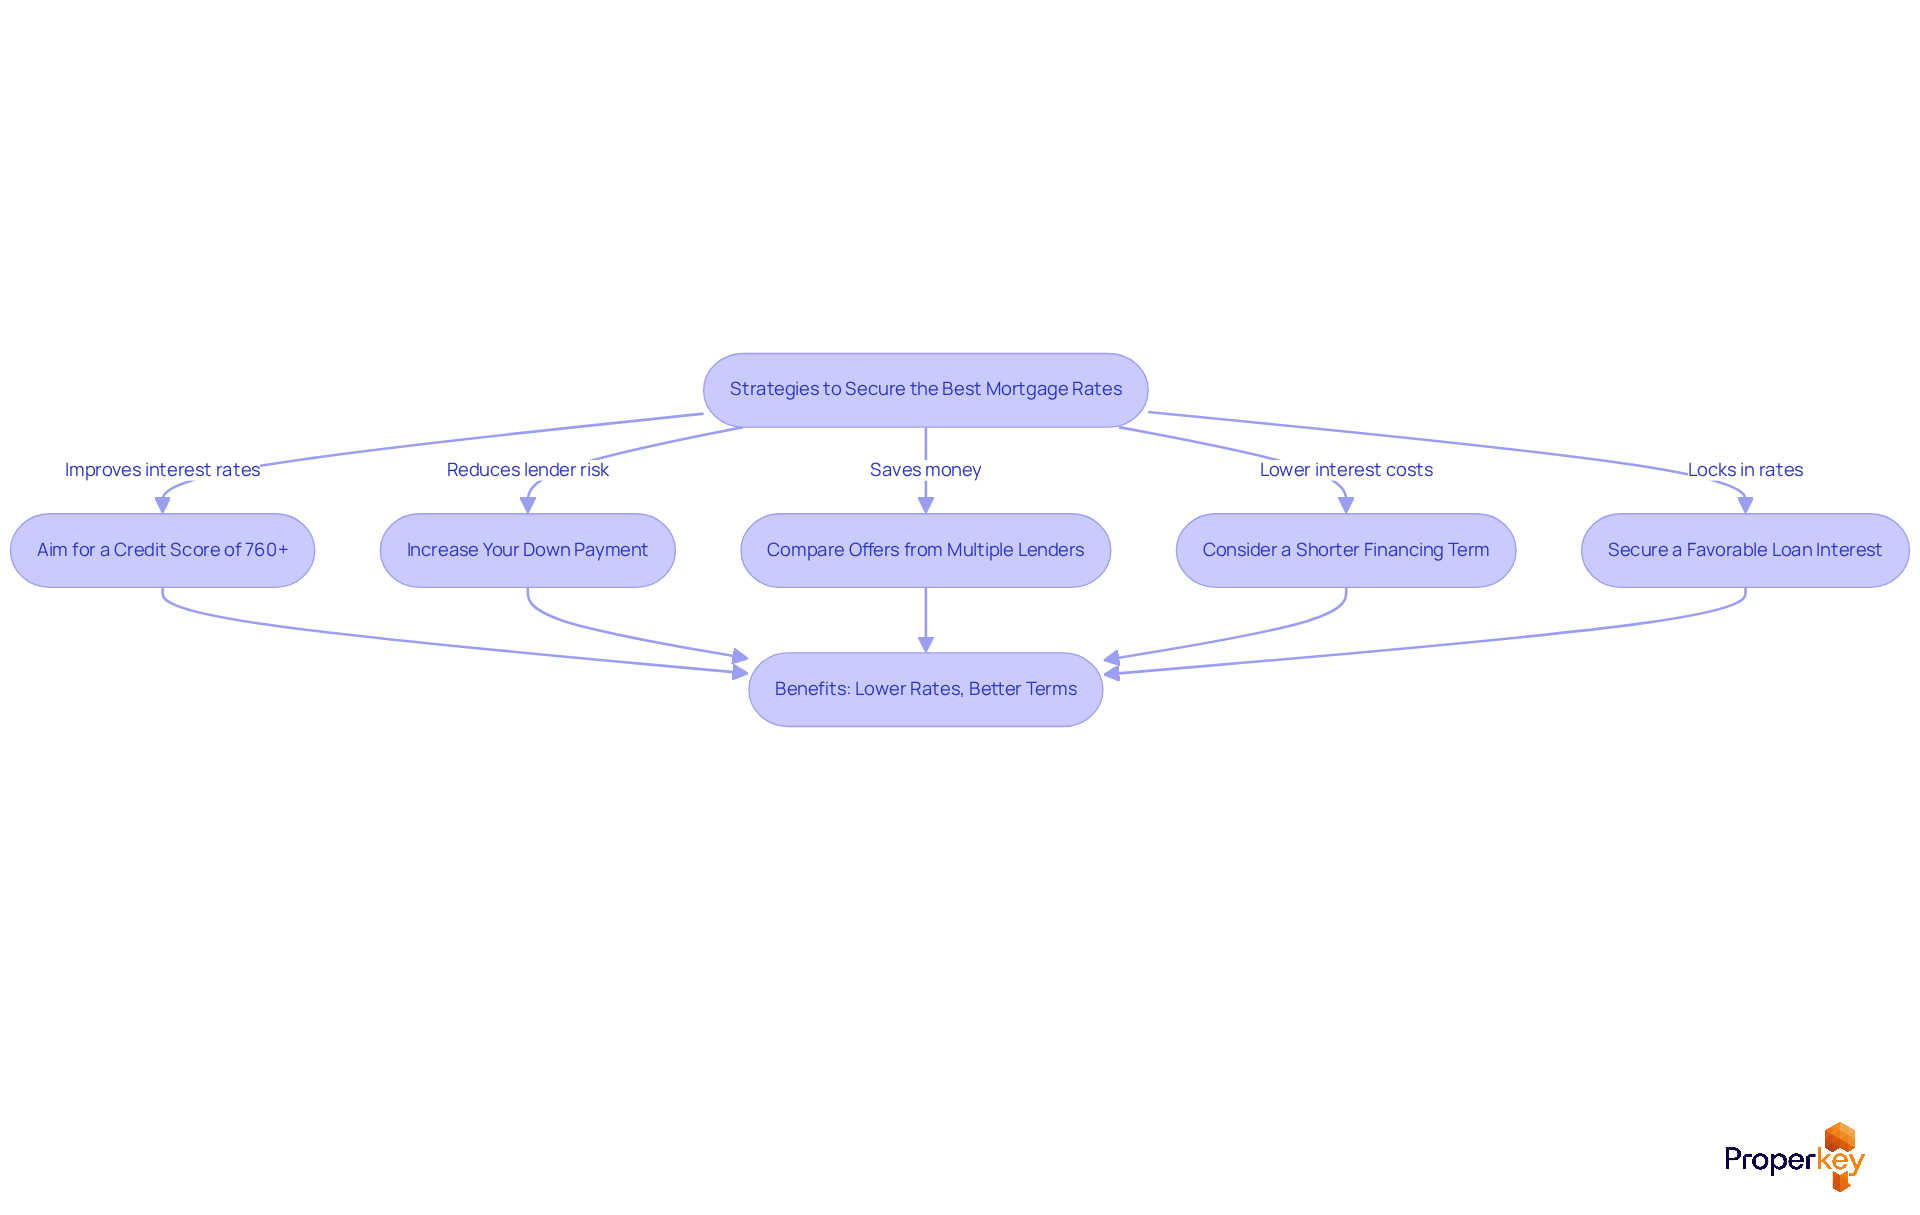
Navigating the mortgage landscape can be daunting, especially when trying to secure the most affordable mortgage. To secure the best interest rates, aim for a credit score of 760 or higher. Focus on paying down existing debts and ensuring timely payments. Even improving your score by just a few points can potentially save you thousands over the life of your loan. Avoid opening new credit lines before applying for a home loan, as this can negatively impact your score.
Increasing your down payment is another effective strategy. A larger down payment not only lowers the lender's risk but also results in more advantageous loan terms. For instance, a down payment of 20% or more can help you avoid private mortgage insurance (PMI), which typically ranges from 0.5% to 1.5% of the loan amount each year, further reducing your monthly payments.
Don’t settle for the first mortgage offer you receive. Borrowers who compare offers from at least three institutions can save an average of $1,500 over the life of their financing, according to the Consumer Financial Protection Bureau. With Loanvana's financing tool, you can apply once and compare hundreds of financing options side-by-side from various providers, making it easier to find the best offer. Negotiating with lenders can also yield better terms.
Consider a shorter financing term. While monthly payments may be higher with a 15-year fixed arrangement, these options typically come with lower interest rates compared to 30-year alternatives. This can lead to substantial savings on interest over the life of the loan, making it a smart choice for long-term homeowners.
If you discover a favorable loan interest, think about securing it. This shields you from possible fee increases while you complete your loan application. Timing your price lock with your closing schedule can help you secure the best deal without risking higher costs later. By implementing these strategies, you can make your mortgage affordable, allowing you to save significantly over the life of your loan and ensuring a more secure financial future.
Analyze Current Trends in Mortgage Affordability
Navigating the complexities of making a mortgage affordable in late 2026 presents significant challenges for home sellers and buyers alike.
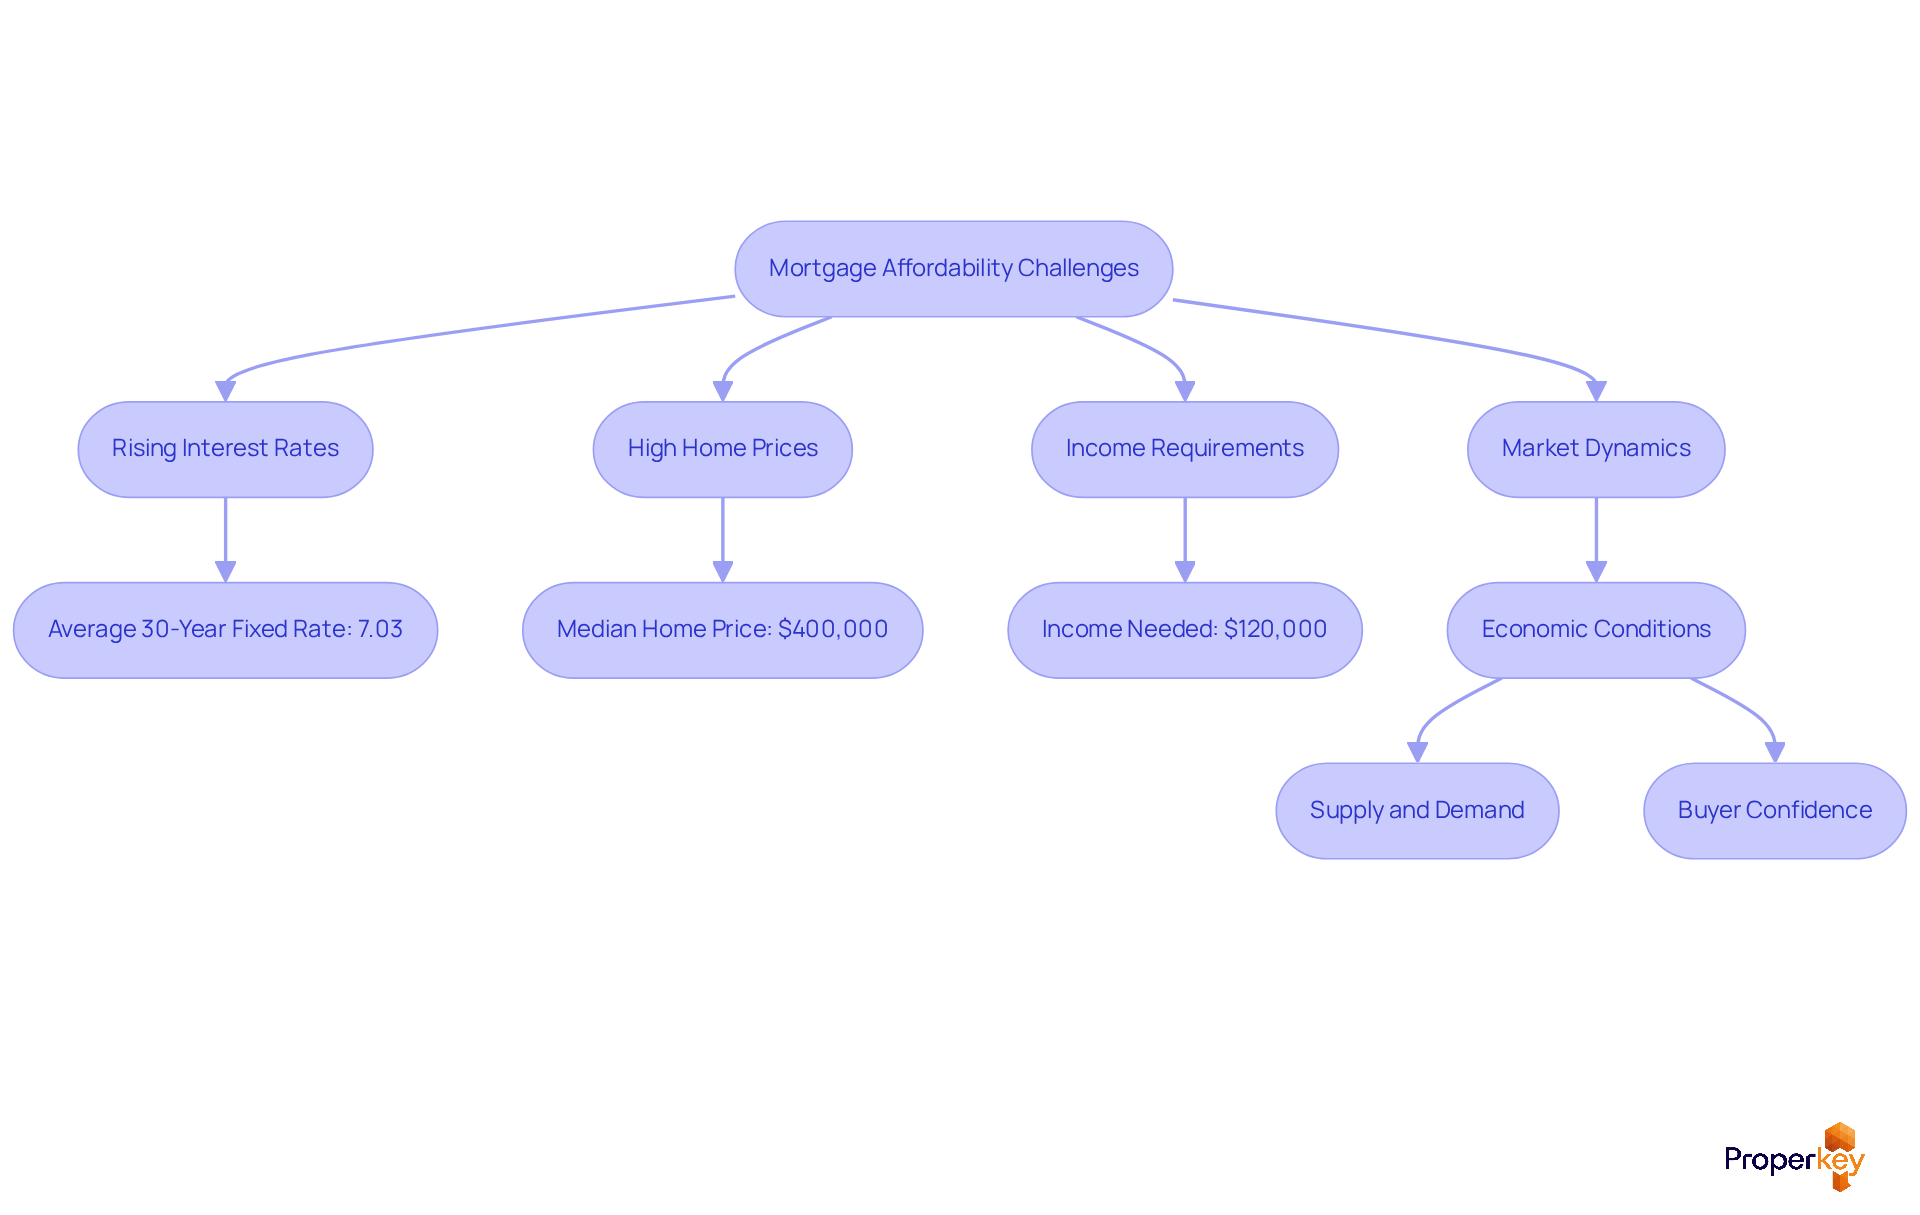
As interest rates rise, the average 30-year fixed mortgage rate hovers around 7.03%. This increase significantly impacts monthly payments, making homeownership less accessible for many buyers. Coupled with high home prices, where the median exceeds $400,000, potential homeowners now need an income of over $120,000 to manage typical mortgage payments comfortably. These payments have surged from $1,700 in early 2020 to approximately $3,100 by late 2025.
While wages are projected to grow by more than 3.6% in 2026, this increase often lags behind the rising costs of housing, which are expected to outpace inflation projected above 3%. As housing costs continue to outpace income growth, many buyers may find themselves priced out of the market.
On the supply side, increased inventory - expected to grow by 8.9% - is providing buyers with more options. However, this remains about 12% below pre-2020 averages, and overall demand continues to exert upward pressure on prices, particularly in competitive markets.
Economic conditions, including inflation and varying employment levels, are also influencing buyer confidence and overall affordability. The rental market is shifting, with vacancy rates increasing from 5.9% in 2022 to 7.3% in early 2026, indicating a more balanced rental landscape that may offer temporary relief to renters.
Grasping these dynamics is essential for navigating mortgage affordable options in today’s market. Take advantage of Loanvana's financing solution to streamline your home-buying process and discover the best loan options available today!
Conclusion
Navigating the complexities of mortgage affordability can feel overwhelming for many prospective home buyers, but understanding it is crucial for securing a home within their financial means. By understanding mortgage rates and the factors that influence them, buyers can navigate the housing market with greater confidence. Strategies for obtaining the best terms are also essential.
Key insights from this article highlight the importance of:
- Credit scores
- Loan-to-value ratios
- Economic indicators in determining mortgage rates
Additionally, strategies such as:
- Increasing down payments
- Comparing multiple offers
- Considering shorter loan terms
can significantly enhance affordability. As the housing market evolves, staying informed about current trends and utilizing tools like Properkey's financing analysis can empower buyers to make informed decisions.
The path to homeownership isn’t just about finding the right house; it’s about making informed choices every step of the way. By embracing these practices, buyers not only enhance their chances of securing favorable mortgage terms but also pave the way for a more secure financial future in an unpredictable market.
Frequently Asked Questions
What are mortgage rates and how do they affect home buyers?
Mortgage rates represent the cost of borrowing money to purchase a home, typically expressed as a percentage of the loan amount. They can be fixed, remaining the same throughout the loan term, or variable, changing with the market.
What factors influence the mortgage amount a buyer can secure?
The mortgage amount depends on several factors, including the buyer's credit score, the size of the down payment, and the current economic climate.
What are the current average interest rates for fixed loans?
The current average interest rate for a 30-year fixed loan is around 6.63%, while the 15-year rate is approximately 5.95%.
How do changes in the Federal Reserve's interest rates impact mortgage costs?
Changes in the Federal Reserve's interest rates can significantly affect loan costs, which in turn impacts the monthly payments for borrowers.
What is the prediction for mortgage costs in the coming years?
Experts predict that as inflation eases, mortgage costs may gradually decline, potentially dropping below 6% by 2026, making homeownership more accessible for families.
How much of a typical family's monthly income goes towards mortgage payments?
Typically, the monthly principal and interest payment accounts for about 25% of a typical family's monthly income.
What services does Properkey offer to assist home buyers?
Properkey offers a complimentary financing analysis service that helps buyers explore their options before committing to a mortgage.
What tools can help buyers compare loan options?
Tools like Loanvana's financing solution allow buyers to apply once and compare hundreds of loan options side-by-side from various providers, streamlining the decision-making process.
List of Sources
- Explain How Mortgage Rates Work
- Mortgage Rates Retreat, Still Near One-Year Peak | Bankrate (https://bankrate.com/mortgages/analysis/mortgage-rates-august-5-2026)
- 2026 Mortgage Rate Forecast: When Will Rates Go Down? (https://money.usnews.com/loans/mortgages/mortgage-rate-forecast)
- Will mortgage rates drop below 6% in 2026? (https://cbsnews.com/news/will-mortgage-rates-drop-below-6-2026)
- Will Mortgage Rates Go Down in 2026? | Morgan Stanley (https://morganstanley.com/insights/articles/mortgage-rates-forecast-2025-2026-will-mortgage-rates-go-down)
- Will Mortgage Rates Drop Further in 2026? What Experts Predict (https://midflorida.com/resources/insights-and-blogs/insights/mortgage/will-mortgage-rates-drop-further-in-2026-what-experts-predict)
- Identify Factors Influencing Mortgage Rates
- Can mortgage rates fall without another Fed rate cut? Here's what experts think (https://cbsnews.com/news/can-mortgage-rates-fall-without-fed-rate-cut-what-experts-think)
- The impact of today’s interest rates on the housing market | U.S. Bank (https://usbank.com/investing/financial-perspectives/investing-insights/interest-rates-impact-on-housing-market.html)
- Mortgage interest rates forecast for 2026 (https://rocketmortgage.com/learn/mortgage-interest-rates-forecast)
- Mortgage rate predictions for the next five years: What you can expect through 2031 (https://finance.yahoo.com/personal-finance/mortgages/article/mortgage-rate-predictions-for-the-next-five-years-what-you-can-expect-through-2031-195826935.html)
- 2026 Mortgage Rate Forecast: When Will Rates Go Down? (https://money.usnews.com/loans/mortgages/mortgage-rate-forecast)
- Outline Strategies to Secure the Best Mortgage Rates
- Average Mortgage Rates by Credit Score (https://experian.com/blogs/ask-experian/average-mortgage-rates-by-credit-score)
- How to Improve Your Credit Score to Qualify for a Mortgage (https://newrez.com/blog/self-help-articles/how-to-improve-your-credit-score-to-qualify-for-a-mortgage)
- How to Get the Best Mortgage Rate in 2026: 9 Strategies That Actually Move the Needle (https://amerisave.com/learn/how-to-get-the-best-mortgage-rate-in-strategies-that-actually-move-the-needle)
- Tips for Increasing Your Credit Score Before You Buy A Home - Needham Bank (https://needhambank.com/resources/tips-for-increasing-your-credit-score-before-you-buy-a-home)
- Your credit score is essential to obtain a good mortgage — here's how to boost your score before you apply for a loan (https://cnbc.com/select/how-to-boost-credit-score-before-you-apply-to-mortgage)
- Analyze Current Trends in Mortgage Affordability
- 2026 Mortgage Industry Outlook: Key Trends Impacting Home Ownership (https://fnbo.com/insights/mortgage/2026/2026-mortgage-industry-outlook-key-trends-impacting-home-ownership)
- Housing Forecast 2026: Mortgage Rates Remain Above 6%, but Affordability Improves Modestly (https://realtor.com/news/trends/housing-forecast-2026-mortgage-rates-affordability-improves)
- Ten Takeaways from the 2026 State of the Nation’s Housing (https://jchs.harvard.edu/blog/ten-takeaways-2026-state-nations-housing)



