Master the Income Needed for a $130K Mortgage in 4 Simple Steps

Introduction
Navigating the complexities of mortgage income requirements can feel overwhelming, especially in today’s competitive housing market. With rising home prices and stringent lending criteria, potential buyers face a daunting task. They must navigate a maze of financial metrics to determine their affordability. This guide breaks down the essential steps to master the income needed for a $130K mortgage, empowering you to make informed decisions about your home-buying journey.
Many potential buyers find themselves struggling to meet the financial requirements. This lack of clarity can lead to missed opportunities in a competitive market.
Understand Mortgage Affordability Basics
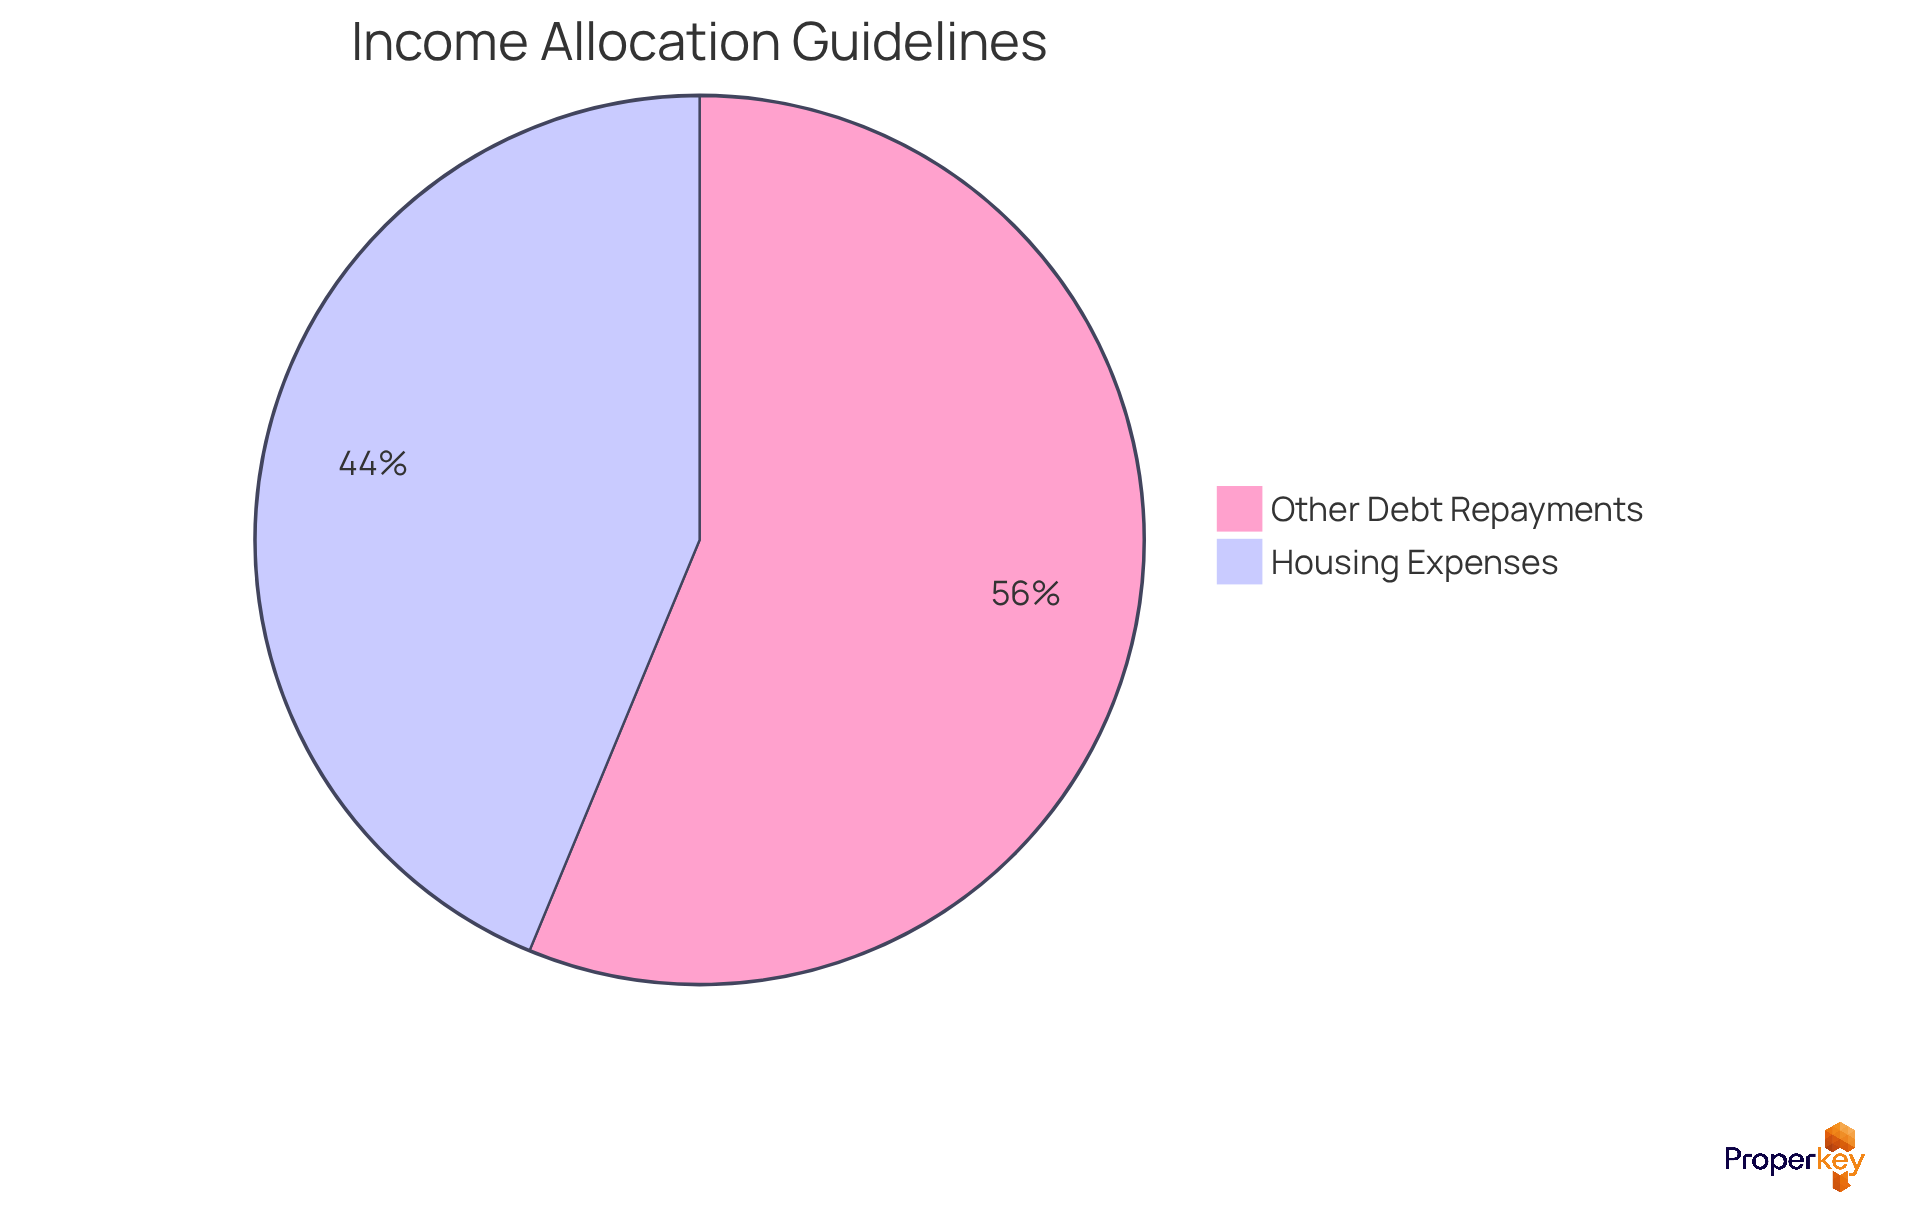
Navigating the complexities of mortgage affordability is crucial for anyone looking to understand the income needed for a 130k mortgage. Mortgage affordability is about how much of your income you can spend on housing without risking your financial health. Generally, it’s wise to keep your monthly housing costs below 28% of your gross income. This includes not just the loan payment, but also property taxes, homeowner's insurance, and any relevant homeowners association (HOA) fees.
Furthermore, lenders often apply the 28/36 guideline, which means that no more than 28% of your gross earnings should go towards housing expenses, and no more than 36% should be directed towards overall debt repayments, including credit cards and other loans. Understanding these ratios will help you evaluate your financial readiness for a loan and determine how much you can afford to borrow.
Key Points:
- Gross Monthly Income: This is your income before taxes and deductions.
- Housing Expenses: Include loan installments, property taxes, insurance, and HOA fees.
- Debt-to-Income Ratio (DTI): A metric of your regular debt obligations relative to your gross regular earnings, essential for lenders in evaluating your mortgage qualification.
With only 22% of households able to afford a median-priced home in California, many are left grappling with financial uncertainty. For instance, a minimum annual income of $204,800 is required to qualify for a median-priced home, underscoring the financial challenges many face in the current market. Additionally, the projected regular cost for a two-bedroom residence in California is approximately $4,600, considerably greater than the anticipated rent of $2,700. Grasping these affordability metrics is essential for navigating today’s challenging housing landscape.
Calculate Required Income for a $130K Mortgage
Let’s break down how to determine the income needed for a $130K mortgage:
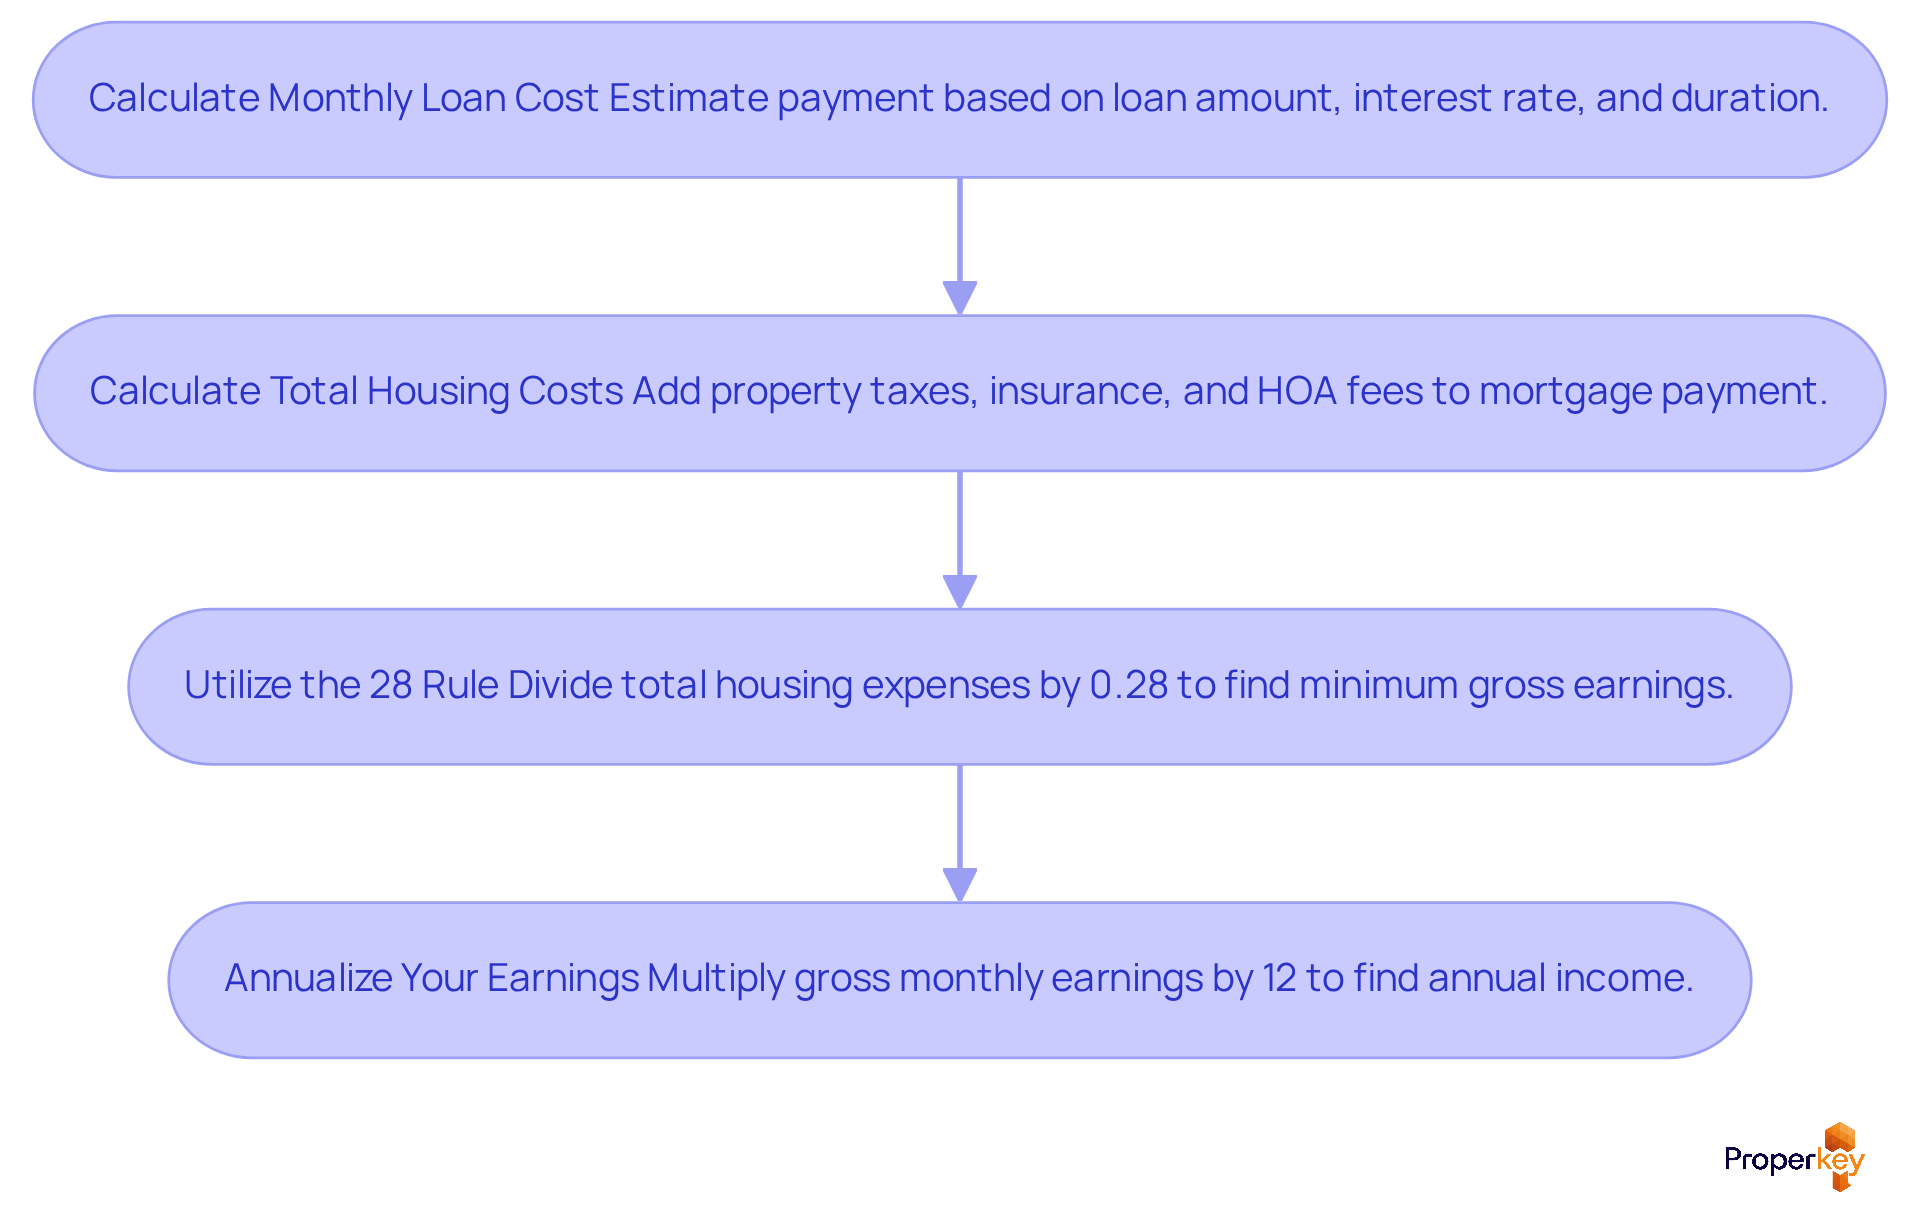
- Calculate Your Monthly Loan Cost: Use a loan calculator to estimate your regular payment based on the loan amount, interest rate, and loan duration. For instance, with a 6.48% interest rate on a 30-year fixed loan, your recurring charge would be roughly $822.
- Calculate Total Housing Costs: Add estimated property taxes, homeowner's insurance, and any HOA fees to your mortgage payment. For example, if your property taxes are $200 per month and insurance is $100 per month, your total housing cost would be $822 + $200 + $100 = $1,122.
- Utilize the 28% Rule: To determine the minimum gross earnings required, divide your total housing expenses by 0.28. Using our example: $1,122 / 0.28 = approximately $4,007. This indicates that the income needed for a 130k mortgage would be about $4,007 to comfortably afford it.
- Annualize Your Earnings: Multiply your gross earnings for the month by 12 to determine your necessary yearly earnings. In this case, $4,007 x 12 = $48,084.
Example Calculation:
- Monthly Mortgage Payment: $822
- Property Taxes: $200
- Homeowner's Insurance: $100
- Total Monthly Housing Cost: $1,122
- Required Gross Monthly Income: $4,007
- Required Annual Income: $48,084
Local Market Context:
In California, where median home prices are expected to remain near or above $900,000 in 2026, grasping these calculations is essential for potential homebuyers navigating today’s market. Additionally, the required monthly income based on a 43% debt-to-income ratio for a $250,000 FHA loan is approximately $5,513, highlighting the financial landscape for buyers in the region. FHA loans can offer options for first-time homebuyers with reduced down payments, making homeownership more attainable.
Streamlined Financing Solutions:
For those looking to explore their options further, Properkey offers a Free Loan Analysis to help you understand your refinancing possibilities and home purchase qualifications. With Loanvana, you can compare hundreds of loans at once, ensuring you find the best rates available. Using these resources can empower you to make informed choices regarding your loan contributions and financing alternatives.
Case Study Reference:
For further insights, consider the "FHA Loan Affordability Insights" case study, which emphasizes the importance of understanding mortgage affordability before engaging with a loan officer. Utilizing loan calculators can assist borrowers in preparing for conversations with lenders, resulting in more informed choices about their payment obligations.
Explore Factors Affecting Mortgage Income Requirements
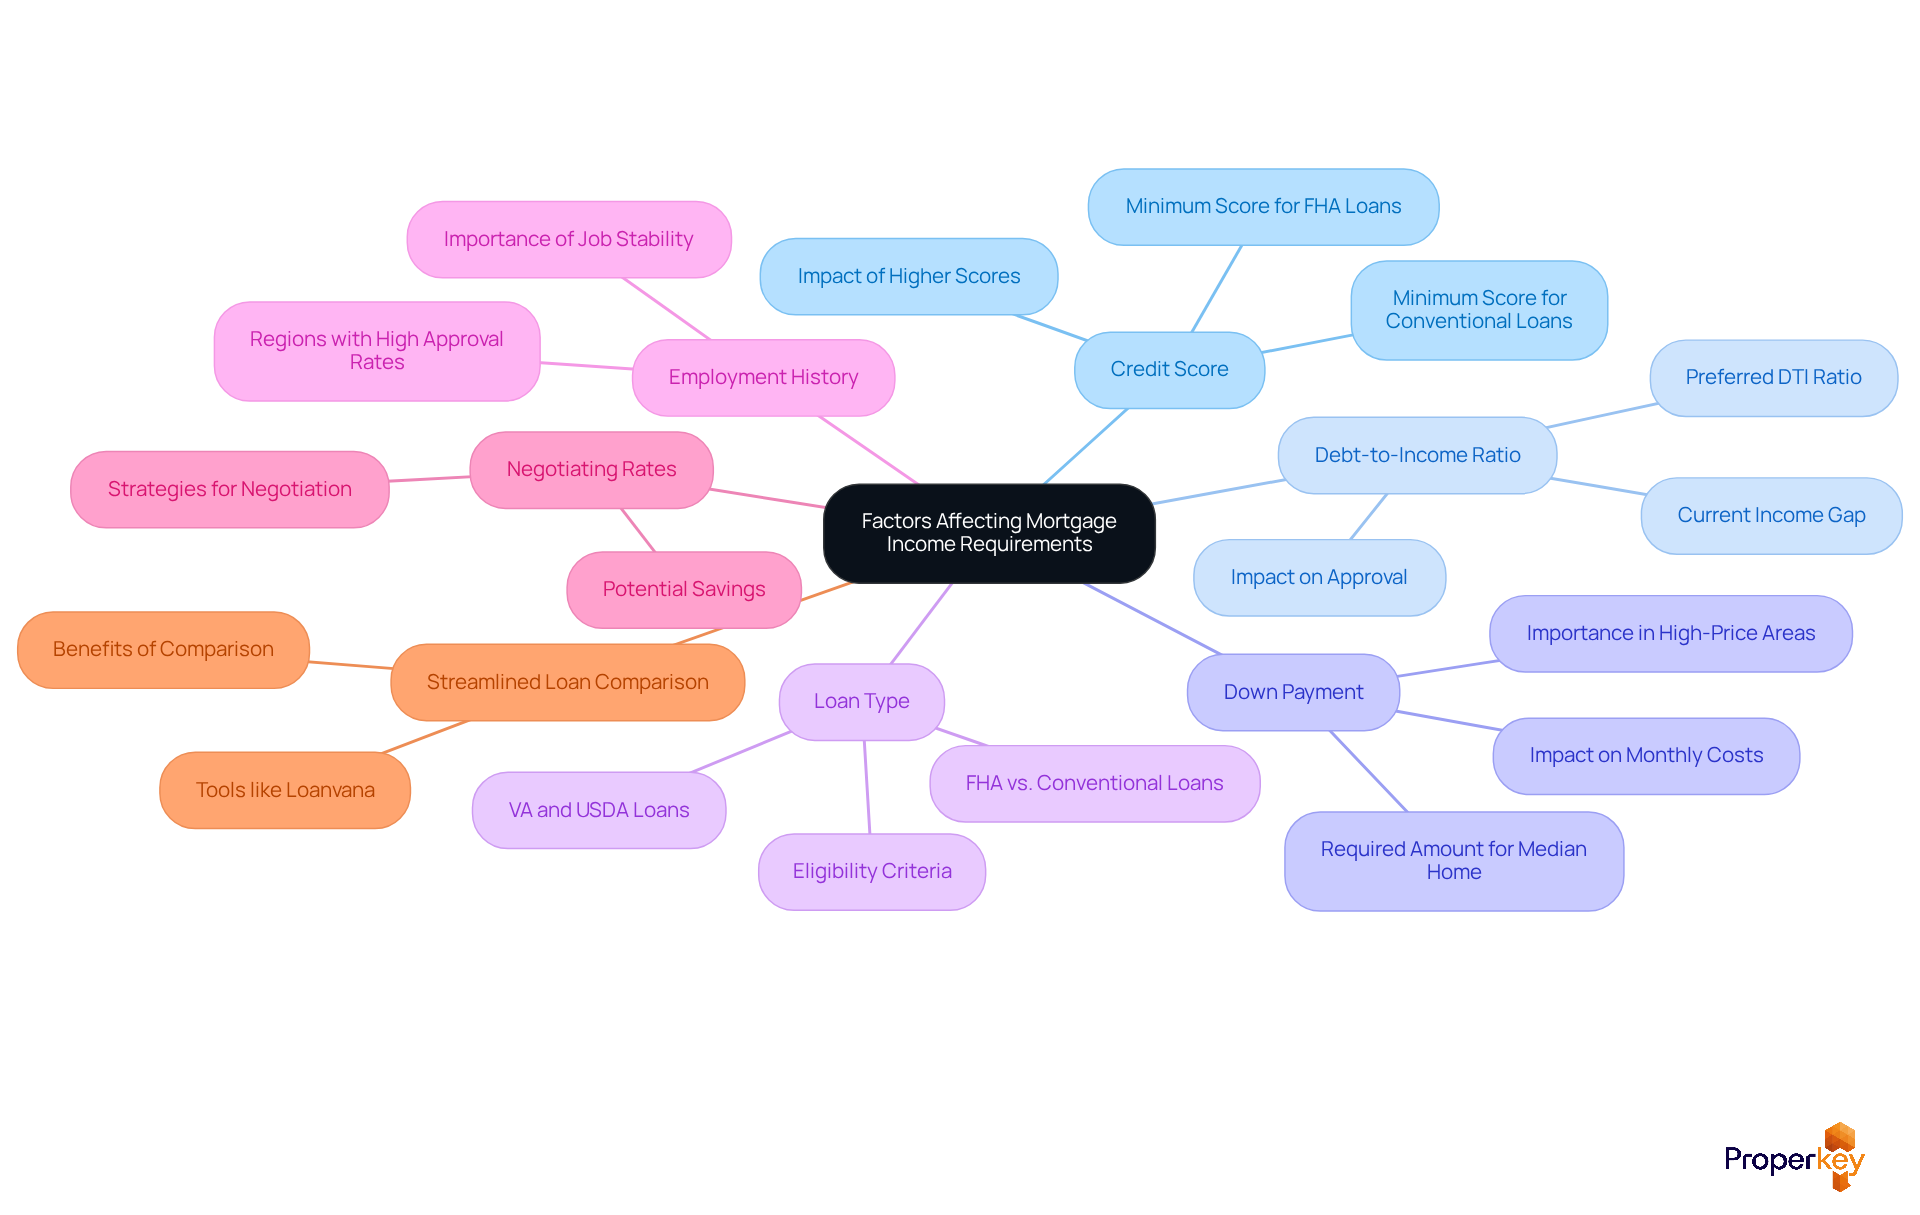
Navigating the mortgage qualification process can feel overwhelming, especially when income requirements seem out of reach for many homebuyers. Understanding the income required to qualify for a mortgage involves several key factors that can significantly impact your eligibility:
- Credit Score: Most lenders look for a minimum credit score, which can really impact your chances of approval. A higher credit score can lead to more advantageous loan conditions, including reduced interest rates. Those scoring above 740 often qualify for the best rates available. For conventional loans, the minimum credit score is generally 620, while FHA loans require a minimum of 580.
- Debt-to-Income Ratio (DTI): This ratio measures your total monthly debt payments against your gross monthly income. A lower DTI indicates better financial health and improves your chances of loan approval. Most lenders prefer a DTI of 36% or lower, which is particularly relevant in the competitive markets of California and Nevada. Currently, the typical household earns about $22,200 less than the income needed for a 130k mortgage, creating a significant barrier to homeownership. This underscores the importance of managing your DTI.
- Down Payment: The amount you put down upfront can influence your mortgage terms. A larger initial deposit decreases the total loan amount and may reduce your monthly installments, positively impacting your DTI. In California, where home prices are high, saving for a larger deposit can significantly enhance your purchasing power. As of June 2026, the income needed for a 130k mortgage is $109,796 annually for Americans to afford the median-priced home, making a substantial down payment even more essential.
- Loan Type: Various types of financing, such as FHA, VA, and conventional loans, come with differing income requirements and eligibility criteria. Getting to know these differences can assist you in choosing the most appropriate loan for your financial situation. Understanding the specific requirements for each loan type can empower you to make informed decisions.
- Employment History: Lenders are more likely to approve those with a solid job history, which speaks volumes about your reliability. A steady job history not only boosts your credibility but also increases your likelihood of obtaining financing, particularly in regions such as Idaho and Nevada, where job stability can be a crucial element in the approval process.
- Negotiating Loan Rates: It is advisable to negotiate loan rates, as doing so can lead to significant savings over the life of the loan. Many borrowers are unaware that they can seek lower rates, which can make a substantial difference in their overall financial commitment.
- Streamlined Loan Comparison: Utilizing tools like Loanvana allows buyers to apply once and compare hundreds of loan options side-by-side from multiple lenders. This streamlines the financing process by offering real-time interest rates and assisting you in locating the best rates accessible, making it simpler to navigate the loan landscape.
Summary of Factors:
- Credit Score: Higher scores lead to better rates.
- DTI: Lower ratios are preferred for approval.
- Initial Deposit: Larger initial deposits can reduce monthly costs and enhance eligibility.
- Loan Type: Different loans have distinct requirements.
- Employment History: Stability is essential for obtaining a loan.
- Negotiating Rates: Seeking lower rates can save money.
- Streamlined Loan Comparison: Tools like Loanvana can help find the best financing options.
Understanding these factors not only prepares you for the mortgage process but also positions you to seize opportunities in the housing market that others might overlook.
Utilize Tools and Resources for Accurate Calculations
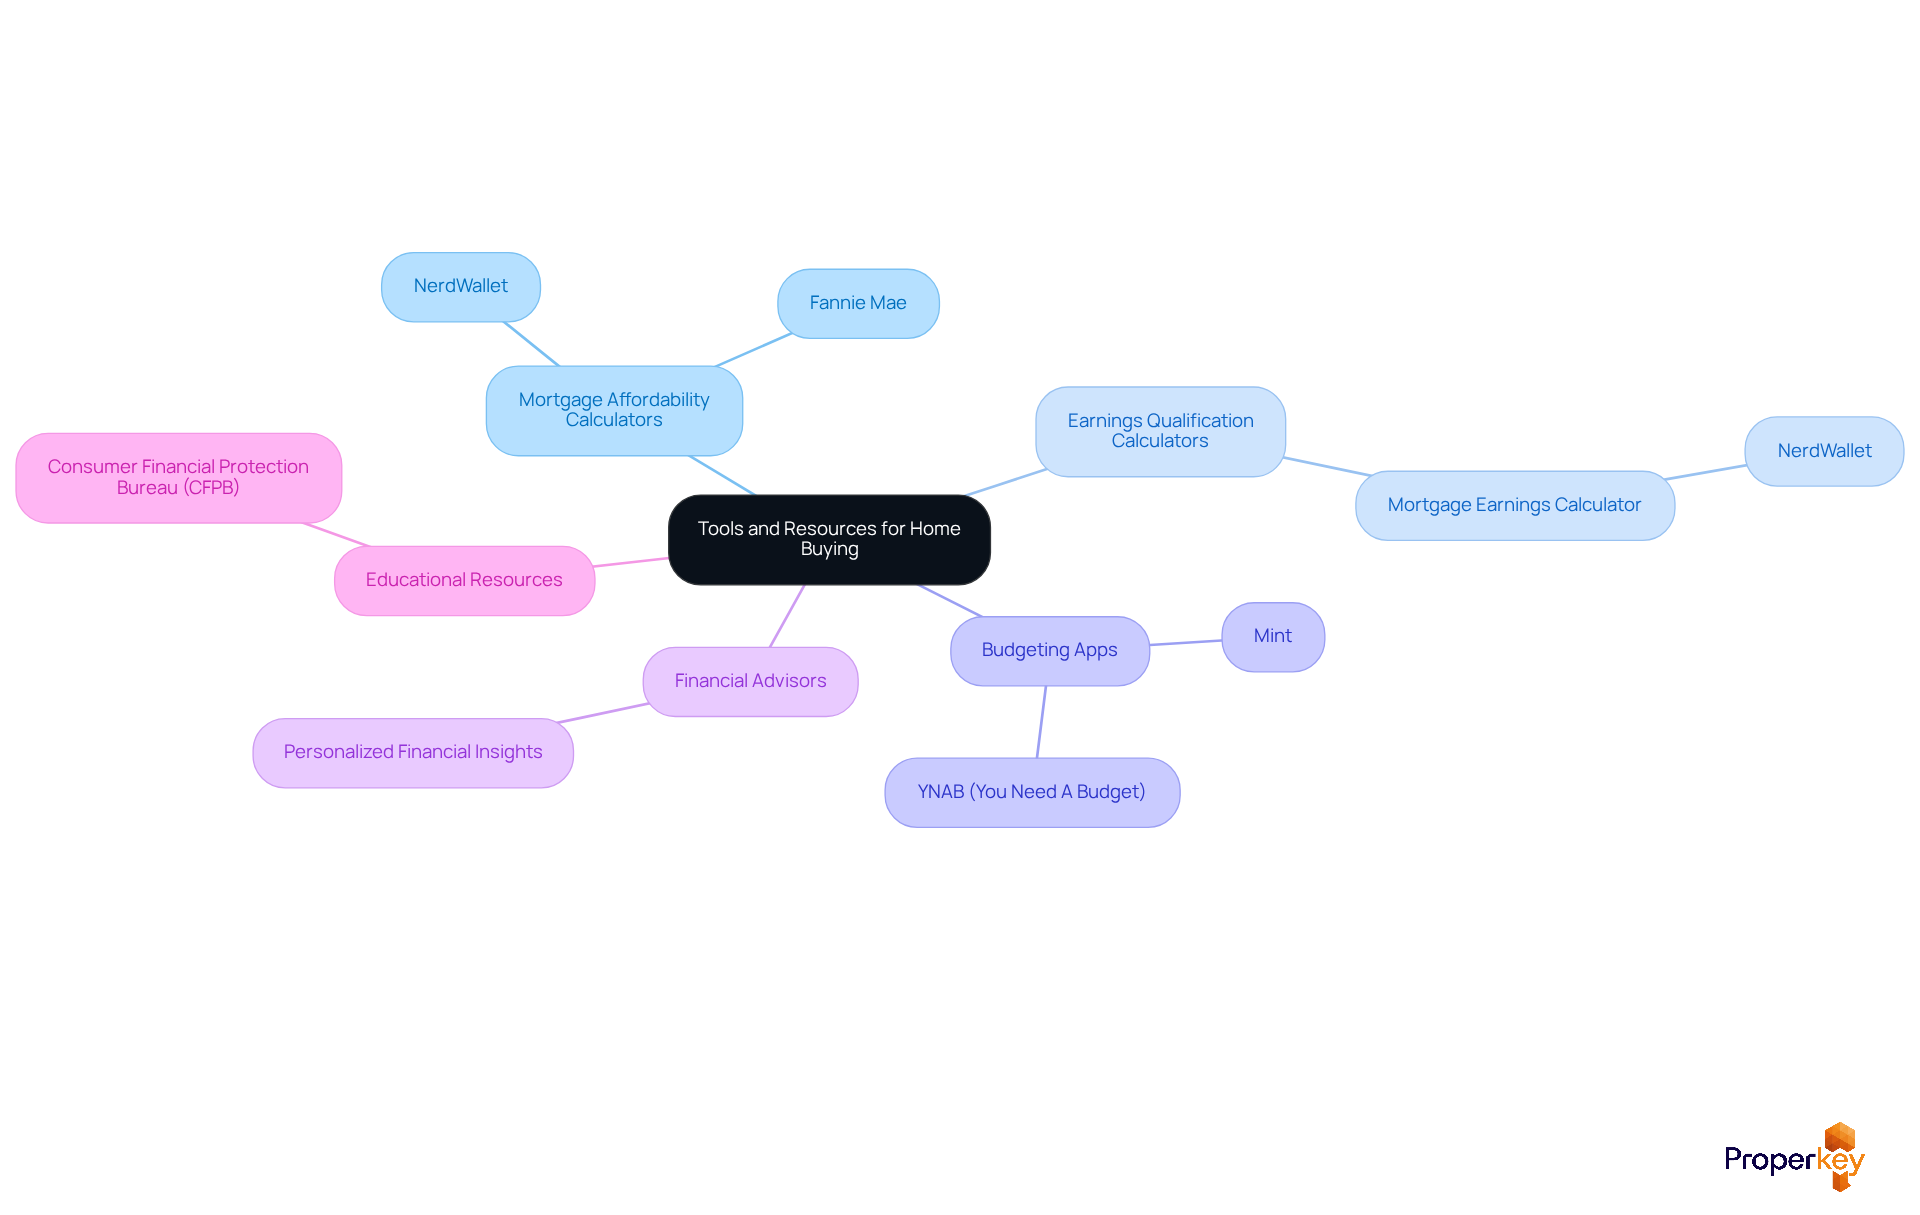
Are you feeling overwhelmed by the financial complexities of buying a home? To ensure accurate calculations and informed decision-making, consider utilizing the following tools and resources:
- Mortgage Affordability Calculators: Platforms such as NerdWallet and Fannie Mae offer calculators that help estimate how much house you can afford based on your earnings, debts, and down payment. These tools are particularly useful for understanding your financial capacity in the current market.
- Earnings Qualification Calculators: Tools like the Mortgage Earnings Calculator from NerdWallet can assist in calculating the income needed for a 130k mortgage. This helps align your financial objectives with your home-buying dreams.
- Budgeting Apps: Budgeting apps like Mint or YNAB (You Need A Budget) are great for keeping tabs on your income and expenses, making it easier to manage your finances as you prepare for homeownership in California, Idaho, or Nevada.
- Financial Advisors: Talking to a financial advisor can give you tailored insights that fit your unique financial situation. Their expertise ensures you’re well-prepared for the financing process and can navigate the complexities of home purchasing.
- Educational Resources: Websites like the Consumer Financial Protection Bureau (CFPB) offer valuable information on mortgages, budgeting, and financial literacy. These resources empower you to make informed decisions as you embark on your home-buying journey.
Important Considerations:
- Understanding Expenses: It's essential to consider both one-time and ongoing expenses when determining how much money you need to buy a house. This includes costs like closing fees, maintenance, and property taxes.
- The 28/36 Rule: A widely accepted guideline suggests that housing expenses should not exceed 28% of your gross monthly income, and total debt payments should not exceed 36%. This rule can help you gauge your affordability.
- Current Trends: In 2026, 37% of homebuyers plan to purchase a home with someone other than a spouse or partner, indicating a trend towards co-buying arrangements that can enhance purchasing power.
Embrace these tools and take control of your financial future in the real estate market.
Conclusion
Navigating the complexities of the housing market can be daunting, especially when it comes to understanding the income required for a $130K mortgage. Mastering the calculations and factors that influence mortgage affordability empowers individuals to make informed decisions that align with their financial capabilities and homeownership goals.
The article outlines a clear four-step process to determine the required income for a $130K mortgage. It emphasizes the importance of:
- Calculating monthly housing costs
- Applying the 28% rule
- Considering various factors such as credit score, debt-to-income ratio, and down payment
These insights shed light on the financial landscape and the real challenges many face on the path to homeownership, particularly in competitive markets like California, Idaho, and Nevada.
Ultimately, using tools and resources like mortgage calculators, budgeting apps, and financial advisors empowers potential buyers to take control of their financial futures. By grasping mortgage affordability and utilizing available resources, individuals can confidently navigate the home-buying process, ensuring they’re prepared to make sound financial decisions that lead to successful homeownership.
Frequently Asked Questions
What is mortgage affordability?
Mortgage affordability refers to how much of your income you can spend on housing without jeopardizing your financial health. It is generally recommended to keep monthly housing costs below 28% of your gross income.
What costs are included in monthly housing expenses?
Monthly housing expenses include loan payments, property taxes, homeowner's insurance, and any relevant homeowners association (HOA) fees.
What is the 28/36 guideline?
The 28/36 guideline suggests that no more than 28% of your gross income should go towards housing expenses, and no more than 36% should be allocated to overall debt repayments, including credit cards and other loans.
Why is understanding the debt-to-income ratio (DTI) important?
The debt-to-income ratio (DTI) is important because it measures your regular debt obligations relative to your gross income, which lenders use to evaluate your mortgage qualification.
What is the minimum annual income required to qualify for a median-priced home in California?
A minimum annual income of $204,800 is required to qualify for a median-priced home in California.
How does the cost of a two-bedroom residence in California compare to rent?
The projected regular cost for a two-bedroom residence in California is approximately $4,600, which is significantly higher than the anticipated rent of $2,700.
What percentage of households can afford a median-priced home in California?
Only 22% of households are able to afford a median-priced home in California, highlighting the financial challenges many face in the current market.
List of Sources
- Understand Mortgage Affordability Basics
- California Housing Affordability Hits Four-Year High In Q1 2026 (https://nationalmortgageprofessional.com/news/california-housing-affordability-hits-four-year-high-q1-2026)
- California Housing Affordability Tracker (2nd Quarter 2026) [EconTax Blog] (https://lao.ca.gov/LAOEconTax/Article/Detail/793)
- Ten Takeaways from the 2026 State of the Nation’s Housing (https://jchs.harvard.edu/blog/ten-takeaways-2026-state-nations-housing)
- How Much House Can I Afford in Nevada? 2026 Guide (https://nevadarealestategroup.com/blog/how-much-house-can-i-afford-in-nevada)
- What It Would Take To Make the Housing Market Affordable Again in 2026 (https://realtor.com/news/trends/home-prices-mortgage-rate-affordability)
- Calculate Required Income for a $130K Mortgage
- FHA Mortgage Calculator - How Much Can I Afford? (https://fha.com/calculator_afford)
- How Much House Can I Afford If I Make $130,000? | Homebuyer.com Free Mortgage Tools (https://homebuyer.com/tools/how-much-house-can-i-afford/if-i-earn-130k)
- The Income Needed to Afford Typical American Home Holds Steady Near Record High of $110,000 (https://redfin.com/news/affordability-homebuying-2026)
- Income needed to buy a home | LBC Mortgage (https://lbcmortgage.com/blog/income-needed-buy-home)
- New report reveals the income needed to afford a typical American home in 2026 (https://ktvb.com/article/news/nation-world/income-needed-to-buy-home-2026-redfin-report/507-589c056a-bf47-4002-a6eb-2609d4fe5da3)
- Explore Factors Affecting Mortgage Income Requirements
- New report reveals the income needed to afford a typical American home in 2026 (https://cbs8.com/article/news/nation-world/income-needed-to-buy-home-2026-redfin-report/507-589c056a-bf47-4002-a6eb-2609d4fe5da3)
- Mortgage Income Requirements | How to Qualify in [current_year] (https://themortgagereports.com/85149/income-requirements-for-home-loan-guidelines)
- This is the salary needed to afford a typical US home in 2026 (https://finance.yahoo.com/real-estate/articles/salary-needed-afford-typical-us-201247284.html)
- Utilize Tools and Resources for Accurate Calculations
- How Much House Can I Afford? Affordability Calculator - NerdWallet (https://nerdwallet.com/mortgages/calculators/how-much-house-can-i-afford)
- Housing market predictions for 2026: What buyers, renters, and homeowners can expect (https://finance.yahoo.com/personal-finance/mortgages/article/housing-market-predictions-2026-165905235.html)
- Faced With Affordability Challenges, 2026 Homebuyers Get Creative (https://money.usnews.com/loans/mortgages/articles/2026-homebuyer-survey)
- Mortgage Affordability Calculator | Fannie Mae (https://yourhome.fanniemae.com/calculators-tools/mortgage-affordability-calculator)