Master the Mortgage Clause: Key Components and Common Pitfalls

Introduction
Are you aware that a simple oversight in understanding mortgagee clauses could jeopardize your home investment? Navigating homeownership can be tricky, especially when it comes to understanding mortgagee clauses, which play a pivotal role in protecting both lenders and homeowners. This crucial provision not only safeguards the financial interests of creditors but also ensures that homeowners can navigate claims and repairs with greater ease.
Many homeowners find themselves confused by the intricacies of mortgagee clauses, risking their financial security. Failing to understand these elements can lead to costly mistakes that jeopardize your investment. Understanding these key elements is not just beneficial; it’s essential for safeguarding your financial future.
Define the Mortgagee Clause: Significance and Functionality
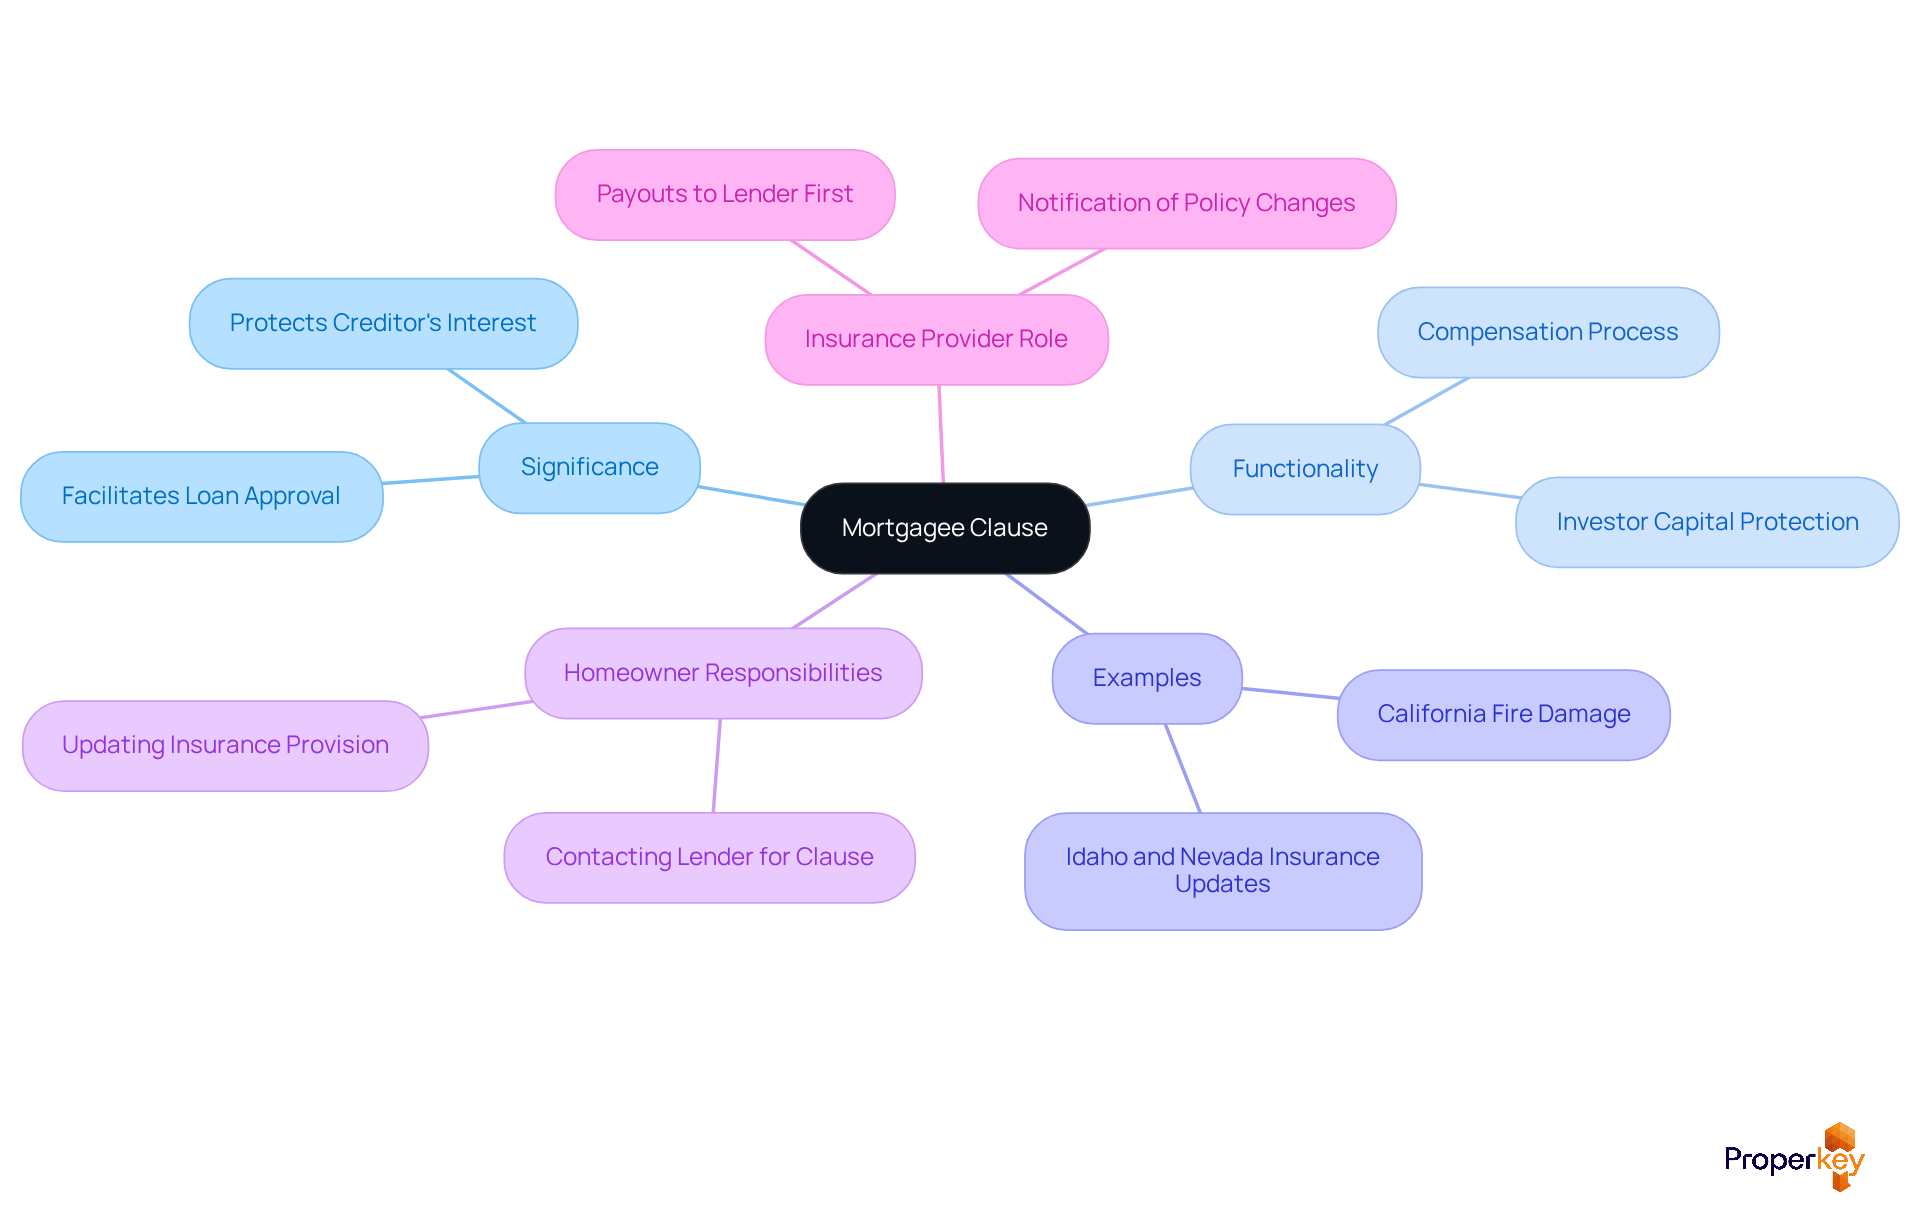
Navigating the complexities of homeownership requires understanding critical elements like the mortgagee provision, which can significantly impact your financial security. A mortgagee provision is an essential element in a homeowner's policy that protects the financial interest of the creditor in the property. This provision guarantees that in the case of damage or destruction, the coverage provider compensates the creditor before any payments are made to the homeowner. The importance of this provision is highlighted by its function in safeguarding the investor's capital, ensuring they are prioritized for compensation payouts. This is crucial for keeping the creditor's security intact, especially when facing major losses from disasters like fires or floods.
For example, in California, if a home experiences fire damage, the mortgage provision specifies that the insurance payment goes directly to the bank, enabling them to settle the remaining mortgage amount or retain funds for essential repairs. This process protects the investor's capital and keeps the property as collateral for the loan.
Statistics indicate that most financial institutions demand a loan provision as a requirement for mortgage approval, highlighting its significance in the borrowing process. Without this provision, securing a loan can become a daunting challenge for homeowners, as lenders hesitate to approve financing without adequate protection against potential losses.
Furthermore, homeowners in Idaho and Nevada need to be attentive in confirming that their insurance provision is accurately recorded and refreshed with their insurer, particularly if they refinance or switch financial institutions. Maintaining this provision up to date helps prevent coverage problems and guarantees that the financial interests of the creditor are consistently safeguarded. Grasping the lender's provision is essential for homeowners, as it not only protects the creditor's investment but also aids in smoother claims and repairs, ultimately benefiting both parties involved in the loan agreement.
At Properkey, we offer customizable home protection plans tailored to your needs and budget, ensuring you have the right coverage, including the essential lender provision. Our dedicated local agents are here to guide you through the process, helping you understand how these provisions work within your overall insurance strategy. By ensuring your mortgagee provision is in place, you not only protect your investment but also pave the way for a smoother homeownership experience.
Identify the Components of a Mortgagee Clause: Essential Elements Explained
Navigating the complexities of the mortgage clause list can be daunting for home sellers, yet understanding it is crucial for protecting your investment. A mortgagee clause typically includes several key components that are essential for safeguarding the lender's financial interest in the property:
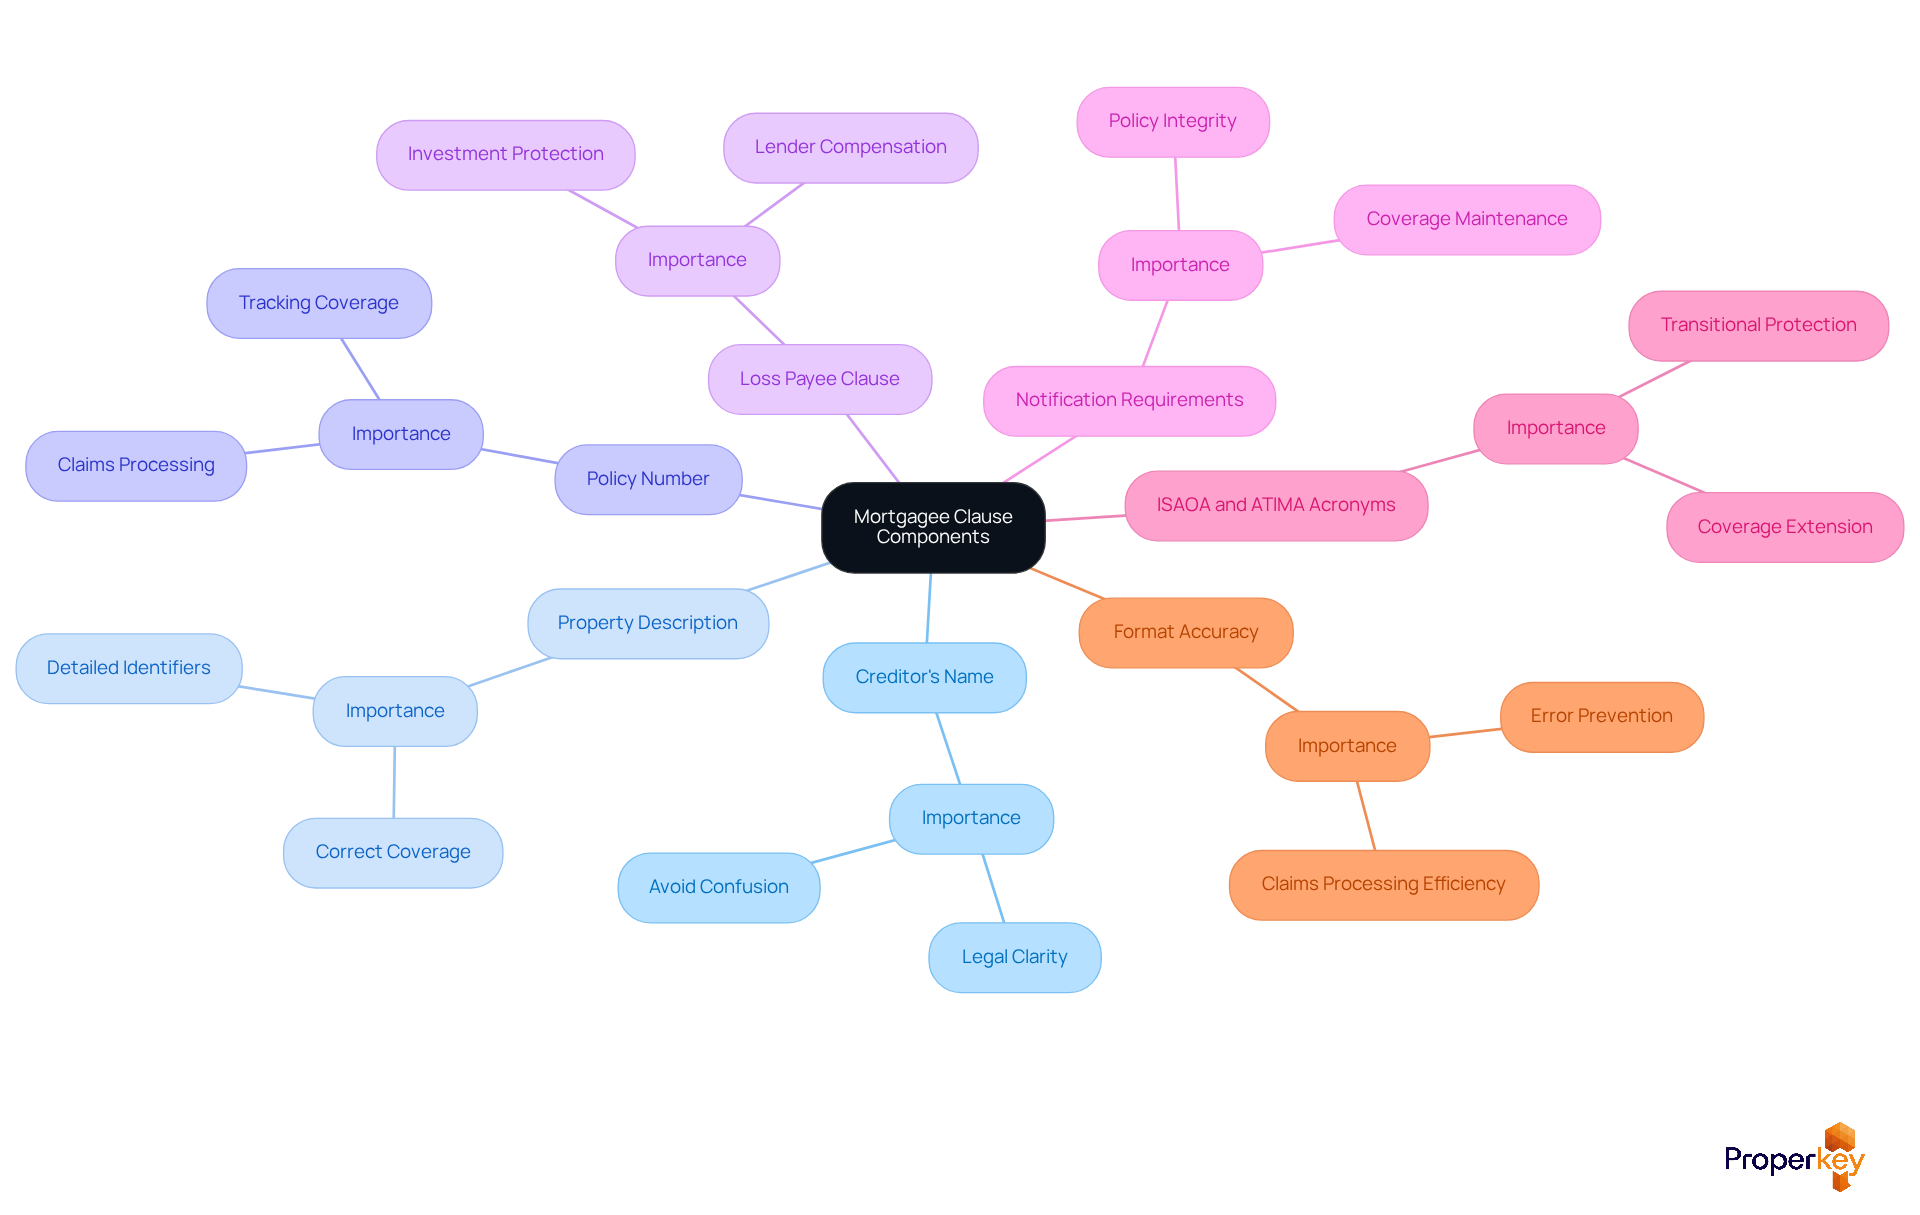
- Creditor's Name: The complete legal name of the creditor or mortgagee must be clearly stated to avoid any confusion regarding who holds the mortgage.
- Property Description: A detailed description of the property being insured, including the address and any relevant identifiers, ensures that the correct property is covered.
- Policy Number: The specific policy number associated with the homeowner's coverage is crucial for tracking and processing claims.
- Loss Payee Clause: This indicates that the creditor will be compensated first in the event of a claim, safeguarding their investment.
- Notification Requirements: The provision should indicate that the creditor must be informed of any modifications to the insurance policy, including cancellations or non-renewals, to uphold coverage integrity.
- ISAOA and ATIMA Acronyms: The inclusion of ISAOA (Its Successors and/or Assigns) and ATIMA (As Their Interests May Appear) is vital, as these terms provide transitional protection, allowing coverage to extend to successors and assigns.
- Format Accuracy: It is important to ensure that the mortgagee clause is formatted correctly, as errors in the creditor's name, address, or other details can lead to complications and delays in claims processing.
By ensuring your mortgage clause list is comprehensive and accurate, you not only protect your lender but also secure your own peace of mind in the selling process.
Avoid Common Mistakes: Ensuring Accuracy in Mortgagee Clauses
Homeowners often overlook critical details in their mortgagee clauses, leading to costly mistakes:
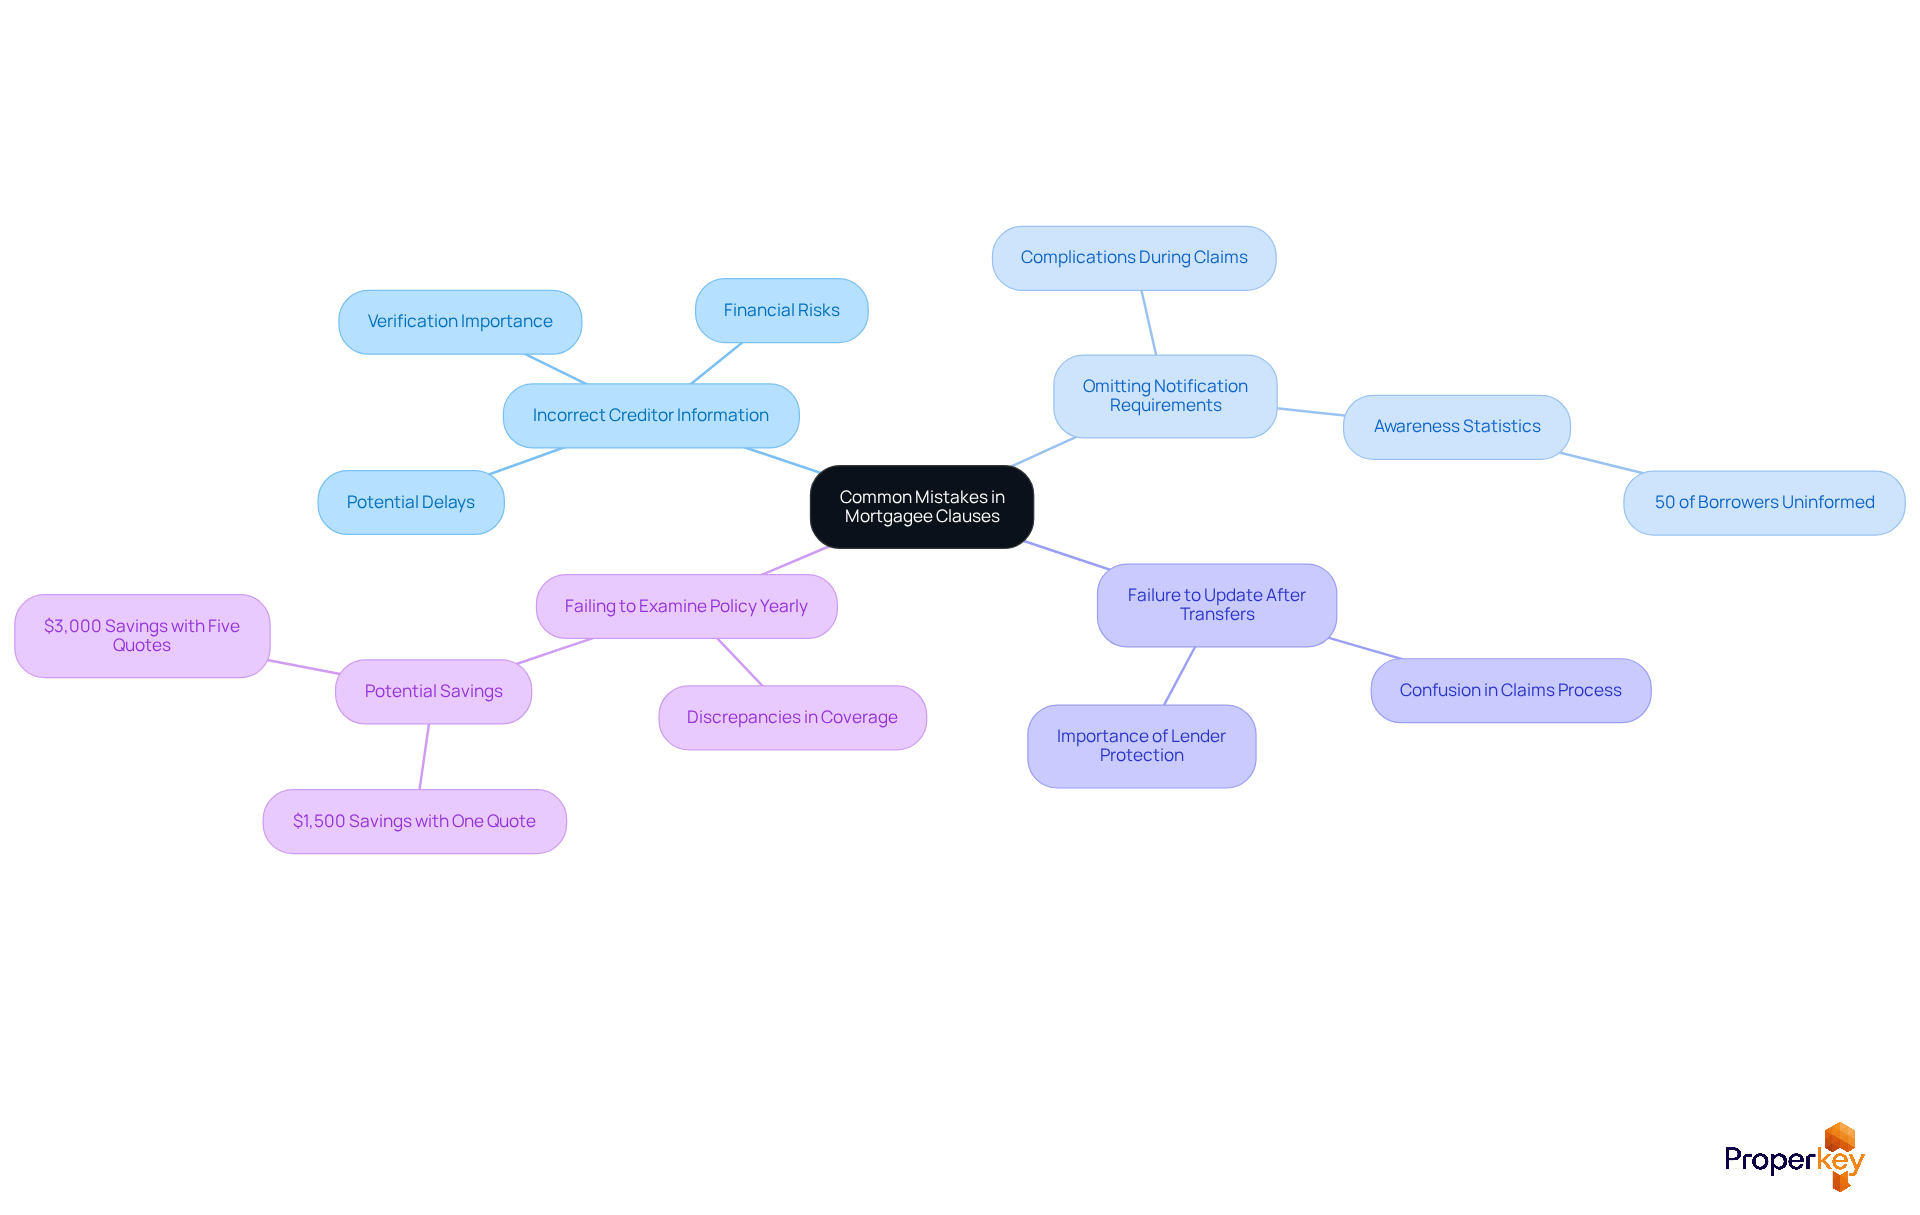
- Incorrect Creditor Information: Always verify that the creditor's name and address are accurate. Mistakes can slow down claims and put your financial recovery at risk if your property gets damaged. As noted, "Your mortgage could be the largest loan you'll ever obtain, and tiny errors can cost you thousands of dollars or delay your sale longer than you'd like."
- Omitting Notification Requirements: The provision should specify the need to inform the creditor about any alterations to the policy. Failing to do so can create complications during claims. Nearly 50% of borrowers never look for a better mortgage rate, which highlights the importance of staying informed about your mortgage details.
- Failure to Update After Transfers: If the mortgage is sold or transferred, it is essential to revise the mortgage provision to reflect the new financial institution's information. Neglecting this step can result in confusion and hinder the claims process. A mortgage clause list that features a lender protection provision is crucial to guarantee the creditor can reclaim its financial stake from compensation payouts if the property is damaged.
- Failing to Examine Policy Yearly: Consistently assessing the coverage agreement guarantees that the mortgagee provision stays precise and current. This practice helps avoid discrepancies that could affect claims. Borrowers could save an average of $1,500 over the life of a loan by obtaining one additional quote, emphasizing the need for thorough research and review.
In the context of VA loans, HUD guidelines, and USDA development information, understanding these common mistakes becomes even more critical. Utilizing resources from the VA Portal and HUD can provide homeowners with essential insights into their mortgage terms and insurance requirements. Neglecting these details could jeopardize your financial security and complicate your claims process.
Understand the Implications: Mortgagee Clause in Real Estate Transactions
Navigating the complexities of lender provisions is crucial for home sellers in states like California, Idaho, and Nevada. Here are the key implications:
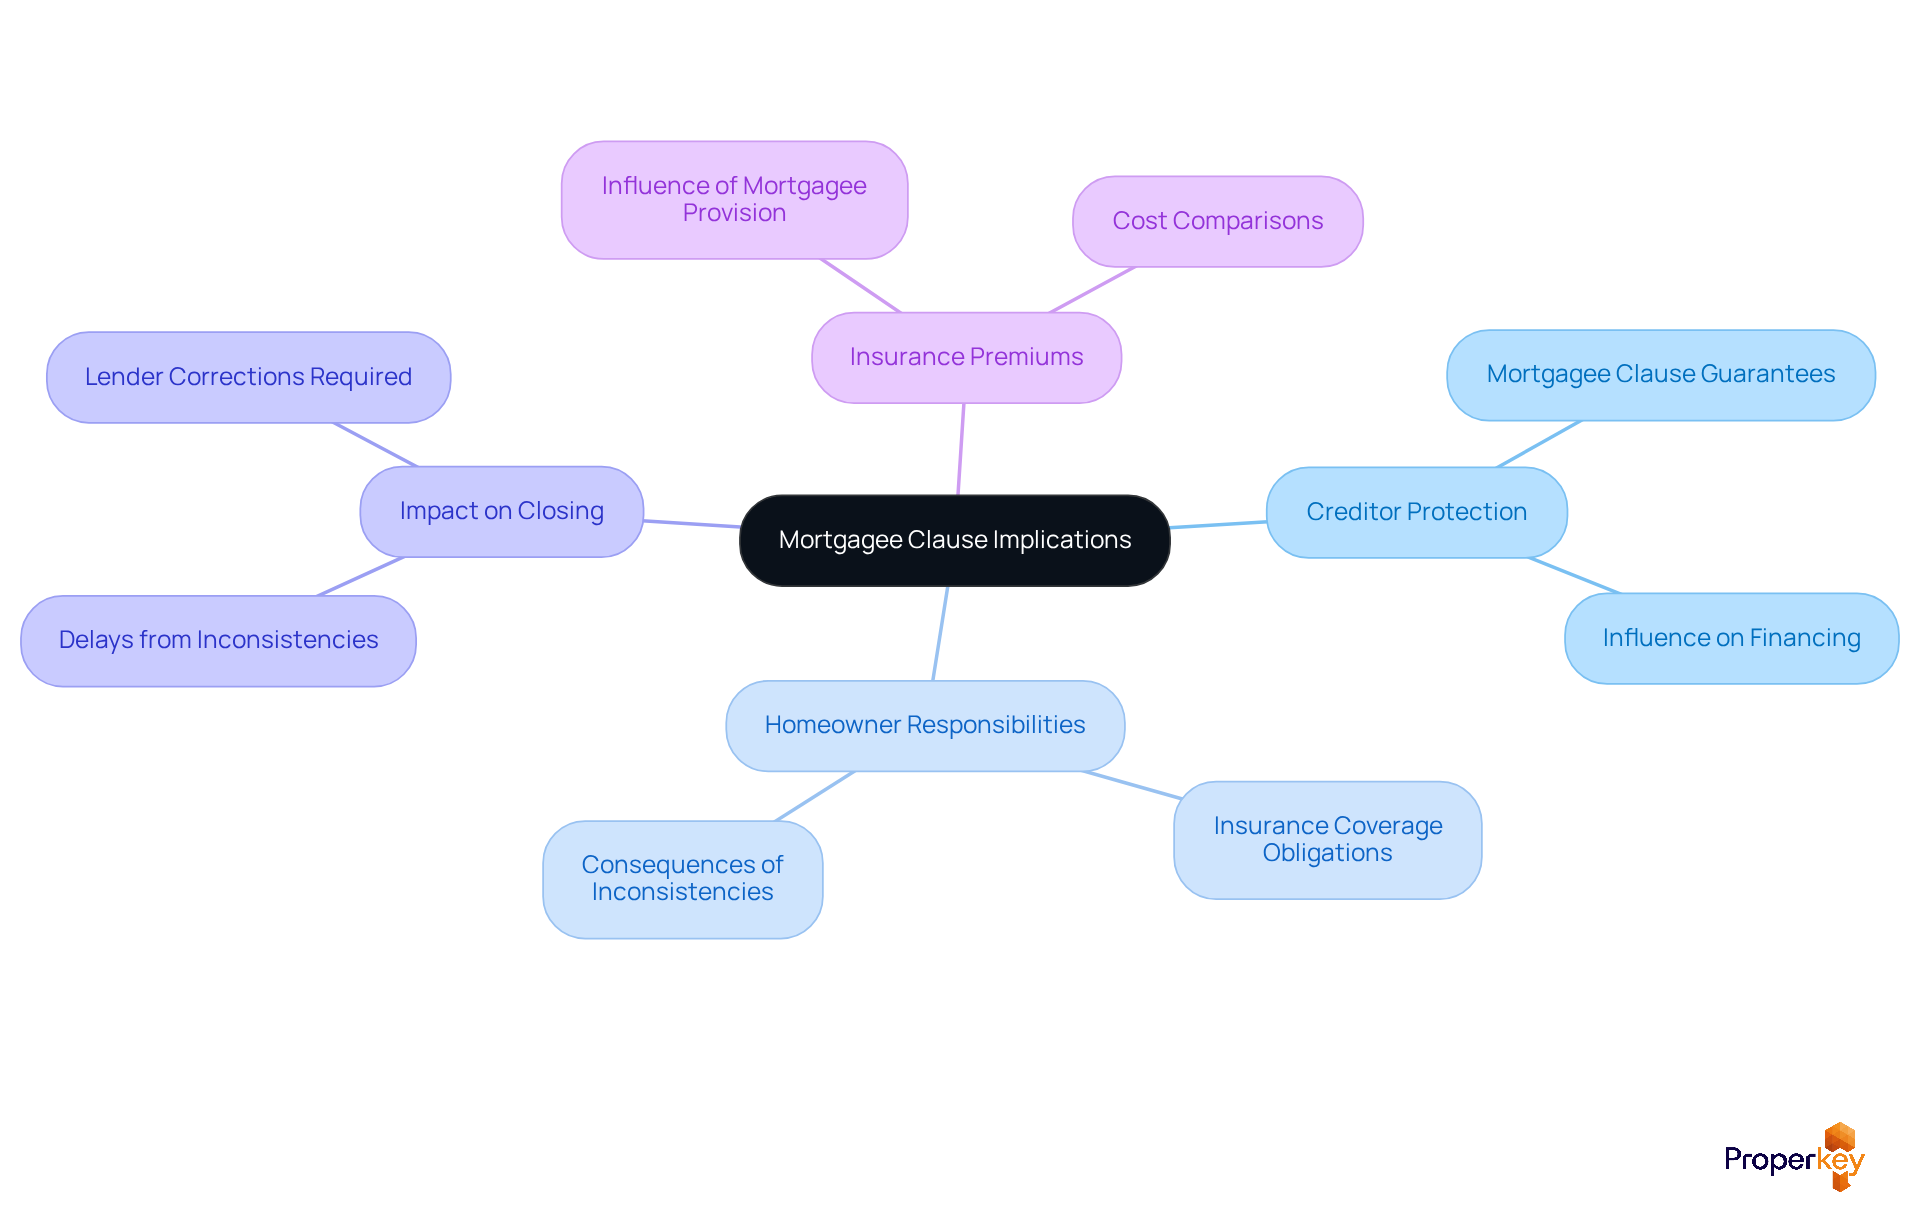
- Creditor Protection: The mortgagee clause guarantees that creditors are reimbursed for their investment in the property. This protection is vital, as it influences lenders' willingness to finance a property, especially in competitive markets where risk assessment is critical.
- Homeowner Responsibilities: Homeowners must be aware of their obligations regarding insurance coverage. A precise lender provision is crucial; any inconsistencies can result in issues during claims handling, possibly leaving homeowners exposed in case of property damage.
- Impact on Closing: Delays in closing can arise from inconsistencies in the lender's provision, causing frustration for all parties involved. Lenders often require corrections before finalizing transactions, which can extend the timeline.
- Insurance Premiums: The existence of a mortgagee provision can influence coverage costs. Insurers assess the risk linked to the property and the lender's criteria, which may result in increased expenses if the provision is not adequately aligned with the coverage policy.
Understanding these implications helps homeowners, buyers, and investors navigate the complexities of mortgage agreements and coverage policies more effectively. For example, in California, an erroneous loan agreement provision can result in the imposition of force-placed insurance, which is considerably pricier than typical coverage, costing homeowners thousands each year. Furthermore, case studies indicate that lenders are more inclined to approve loans when the loan provision is properly formatted and current, emphasizing the significance of keeping precise documentation throughout the transaction process. Utilizing Properkey's services can help ensure that all aspects of the mortgage process, including the mortgagee clause, are handled efficiently, providing peace of mind to homeowners and buyers alike. Understanding these implications can save homeowners from costly mistakes and ensure a smoother transaction process.
Conclusion
Navigating the complexities of the mortgagee clause is crucial for homeowners and investors aiming to protect their financial interests. This provision not only safeguards the financial interests of creditors but also plays a pivotal role in ensuring a smooth homeownership experience. By grasping the significance of the mortgagee clause, individuals can better navigate the complexities of real estate transactions and protect their investments.
Key components of a mortgagee clause, such as accurate creditor information, detailed property descriptions, and notification requirements, are crucial for avoiding common pitfalls. Homeowners must remain vigilant in maintaining and updating these details to prevent costly mistakes that could jeopardize their financial security. Additionally, recognizing the implications of the mortgagee clause in real estate transactions can help streamline the closing process and mitigate potential delays.
By mastering the mortgagee clause, homeowners not only safeguard their investments but also position themselves for success in the real estate market. Prioritizing accuracy and staying proactive in managing mortgage details enhances the homeownership experience and ensures preparedness for any challenges that may arise. Embracing these insights not only protects financial interests but also fosters a more secure and confident approach to real estate dealings.
Frequently Asked Questions
What is a mortgagee clause?
A mortgagee clause is an essential element in a homeowner's policy that protects the financial interest of the creditor in the property. It ensures that in the event of damage or destruction, the insurance provider compensates the creditor before any payments are made to the homeowner.
Why is the mortgagee clause important?
The mortgagee clause is important because it safeguards the investor's capital by prioritizing them for compensation payouts in case of major losses, such as those from disasters like fires or floods. This helps keep the creditor's security intact.
How does the mortgagee clause function in practice?
For example, if a home in California experiences fire damage, the mortgage provision specifies that the insurance payment goes directly to the bank. This allows the bank to settle the remaining mortgage amount or retain funds for necessary repairs, protecting the investor's capital.
Do financial institutions require a mortgagee clause for loan approval?
Yes, most financial institutions demand a mortgagee clause as a requirement for mortgage approval. Without this provision, securing a loan can be challenging for homeowners, as lenders are hesitant to approve financing without adequate protection against potential losses.
What should homeowners in Idaho and Nevada do regarding their mortgagee clause?
Homeowners in Idaho and Nevada should ensure that their mortgagee clause is accurately recorded and updated with their insurer, especially if they refinance or switch financial institutions. Keeping this provision up to date helps prevent coverage problems and ensures the creditor's financial interests are consistently protected.
How does understanding the mortgagee clause benefit homeowners?
Understanding the mortgagee clause is essential for homeowners as it not only protects the creditor's investment but also facilitates smoother claims and repairs, ultimately benefiting both parties involved in the loan agreement.
How can Properkey assist homeowners with mortgagee clauses?
Properkey offers customizable home protection plans that include the essential mortgagee clause. Their dedicated local agents guide homeowners through the process, helping them understand how these provisions work within their overall insurance strategy.
List of Sources
- Define the Mortgagee Clause: Significance and Functionality
- Mortgagee Clause: What It Means for Your Lender Protection (https://investopedia.com/mortgagee-clause-definition-5221668)
- Mortgagee Clause: Definition, How It Works, and Importance (https://mrei.co.uk/post/mortgagee-clause-definition-how-it-works-and-importance)
- What Is A Mortgagee Clause? | Bankrate (https://bankrate.com/mortgages/mortgagee-clause)
- Mortgagee Clause: Definition and How it Works | Chase (https://chase.com/personal/mortgage/education/financing-a-home/what-is-a-mortgagee-clause)
- What is a mortgagee clause? (https://rocketmortgage.com/learn/mortgagee-clause)
- Identify the Components of a Mortgagee Clause: Essential Elements Explained
- Mortgagee Clause: Definition and How it Works | Chase (https://chase.com/personal/mortgage/education/financing-a-home/what-is-a-mortgagee-clause)
- Mortgagee Clause: The Broker's Guide for 2026 | AD Mortgage (https://admortgage.com/blog/mortgagee-clause)
- What Is A Mortgagee Clause? | Bankrate (https://bankrate.com/mortgages/mortgagee-clause)
- Mortgagee Clause: What It Means for Your Lender Protection (https://investopedia.com/mortgagee-clause-definition-5221668)
- What is a Mortgagee Clause | Property Insurance | Citizens (https://citizensbank.com/learning/mortgagee-clause.aspx)
- Avoid Common Mistakes: Ensuring Accuracy in Mortgagee Clauses
- Five Mortgage Mistakes to Avoid as a First-Time Homebuyer | GNM (https://greaternevadamortgage.com/mortgage-resources/five-mortgage-mistakes-to-avoid-as-a-first-time-home-buyer)
- Mortgagee Clause: The Broker's Guide for 2026 | AD Mortgage (https://admortgage.com/blog/mortgagee-clause)
- 6 Common Mortgage Mistakes & How to Avoid Them – Alliant (https://alliantcreditunion.org/money-mentor/steering-clear-of-the-most-common-mortgage-mistakes)
- Mortgagee Clause: What It Means for Your Lender Protection (https://investopedia.com/mortgagee-clause-definition-5221668)
- Understand the Implications: Mortgagee Clause in Real Estate Transactions
- Industry News (https://alta.org/news-and-publications/industry-news)
- National Mortgage Database (NMDB®) Aggregate Statistics | FHFA (https://fhfa.gov/data/nmdb)
- Mortgagee Clause in Texas: What It Is and Why It Matters | Herring Bank (https://herringbank.com/learn/mortgagee-clause-texas)
- Mortgagee Clause: What It Means for Your Lender Protection (https://investopedia.com/mortgagee-clause-definition-5221668)
- Press Release: Homebuyers Used Private Mortgage Insurance to Purchase Homes in a Challenging Real Estate Market - USMI (https://usmi.org/press-release-homebuyers-used-private-mortgage-insurance-to-purchase-homes-in-a-challenging-real-estate-market)