Master Your Mortgage Percentage of Income for Smart Home Buying
Introduction
Navigating the complexities of home buying requires a firm grasp of mortgage percentages, especially in California's competitive market. This percentage dictates how much of a buyer's income is allocated to housing and plays a pivotal role in ensuring long-term financial stability. With rising home prices and fluctuating interest rates, prospective homeowners must confront the challenge of balancing affordability with their aspirations for homeownership.
How can buyers effectively master this critical aspect of their financial planning to avoid the pitfalls of over-leveraging?
Define Mortgage Percentage of Income and Its Importance
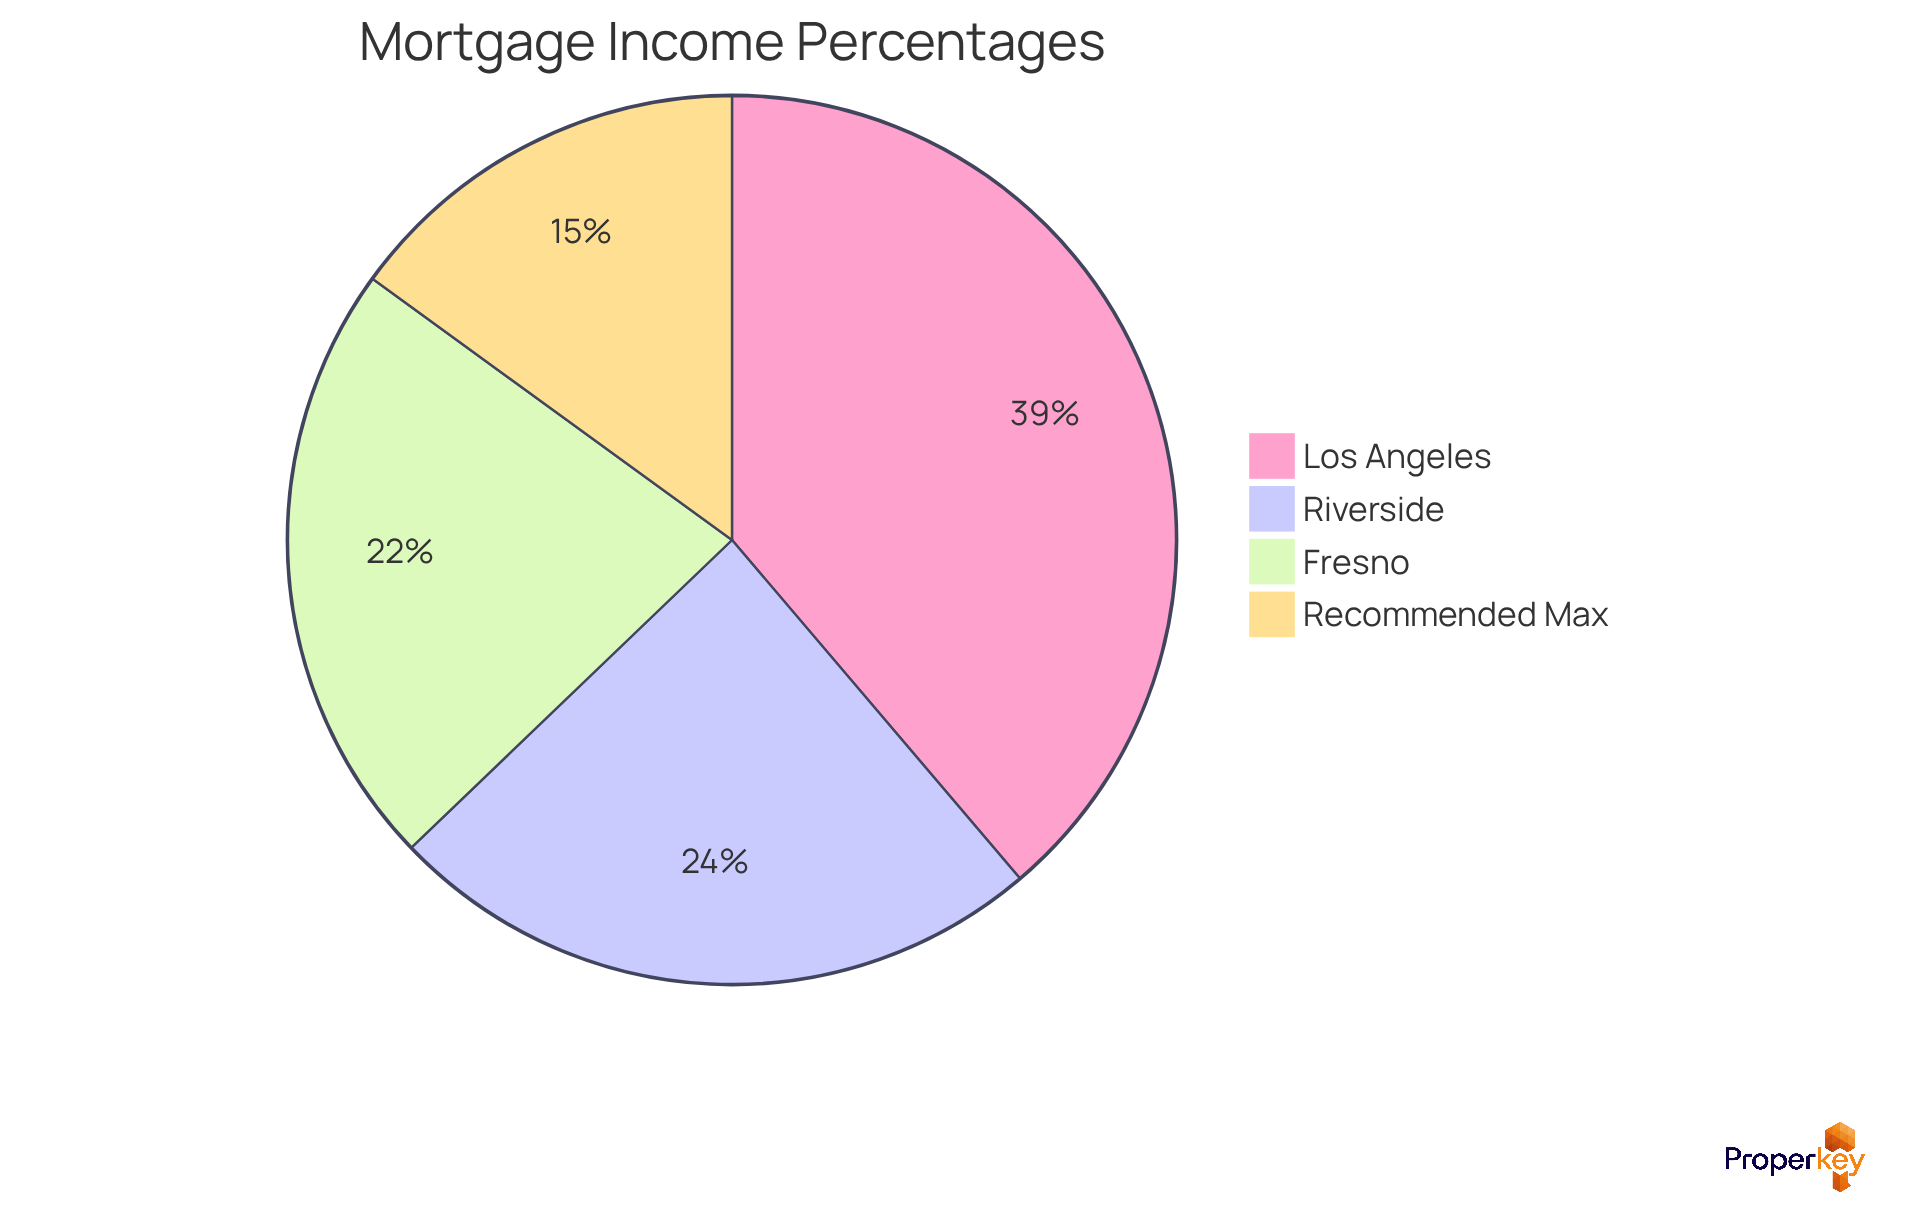
In California's soaring real estate market, understanding loan percentages is more critical than ever for prospective homebuyers. The mortgage percentage of income reflects the portion of a borrower's gross monthly earnings that is allocated to loan installments. Financial specialists typically recommend that the mortgage percentage of income should not exceed 28% of total earnings. This guideline is vital in California, given the state's housing costs far exceed the national average. Following this standard aids in guaranteeing that homeowners can handle their loan obligations comfortably while still covering other necessary living costs.
In California's competitive real estate market, where the median home price is approximately $697,000, many buyers find themselves allocating a significant part of their earnings on housing. This often leads to financial strain and tough choices for many families. For example, in the Los Angeles-Long Beach-Anaheim region, homeowners dedicate around 72.4% of their earnings to housing costs, emphasizing the economic pressure many encounter. This highlights why the 28% rule is essential; it helps prevent over-leveraging by ensuring that the mortgage percentage of income stays within a safe limit, reducing the risk of foreclosure.
Case studies show that in areas such as Riverside-San Bernardino-Ontario, homeowners allocate approximately 44.9% of their earnings towards their mortgage percentage of income, indicating a considerable financial strain. On the other hand, Fresno residents manage to keep their housing payments at 41.4% of income, suggesting a more balanced approach to homeownership.
Expert opinions reinforce the necessity of understanding these percentages. A mortgage specialist emphasizes that an affordable mortgage allows individuals to cover monthly housing costs while still leaving room for savings and emergencies. Therefore, potential buyers should carefully assess their monetary situations and consider all housing expenses, including property taxes and insurance, to determine what is truly affordable. This way, they can make smart choices that support their financial well-being in the long run.
Additionally, utilizing Loanvana's financing tool can greatly assist buyers in this process. By applying once, they can compare hundreds of loan options side-by-side from multiple lenders, ensuring they find the best rates and terms that align with their financial capabilities.
Calculate Your Mortgage Percentage of Income
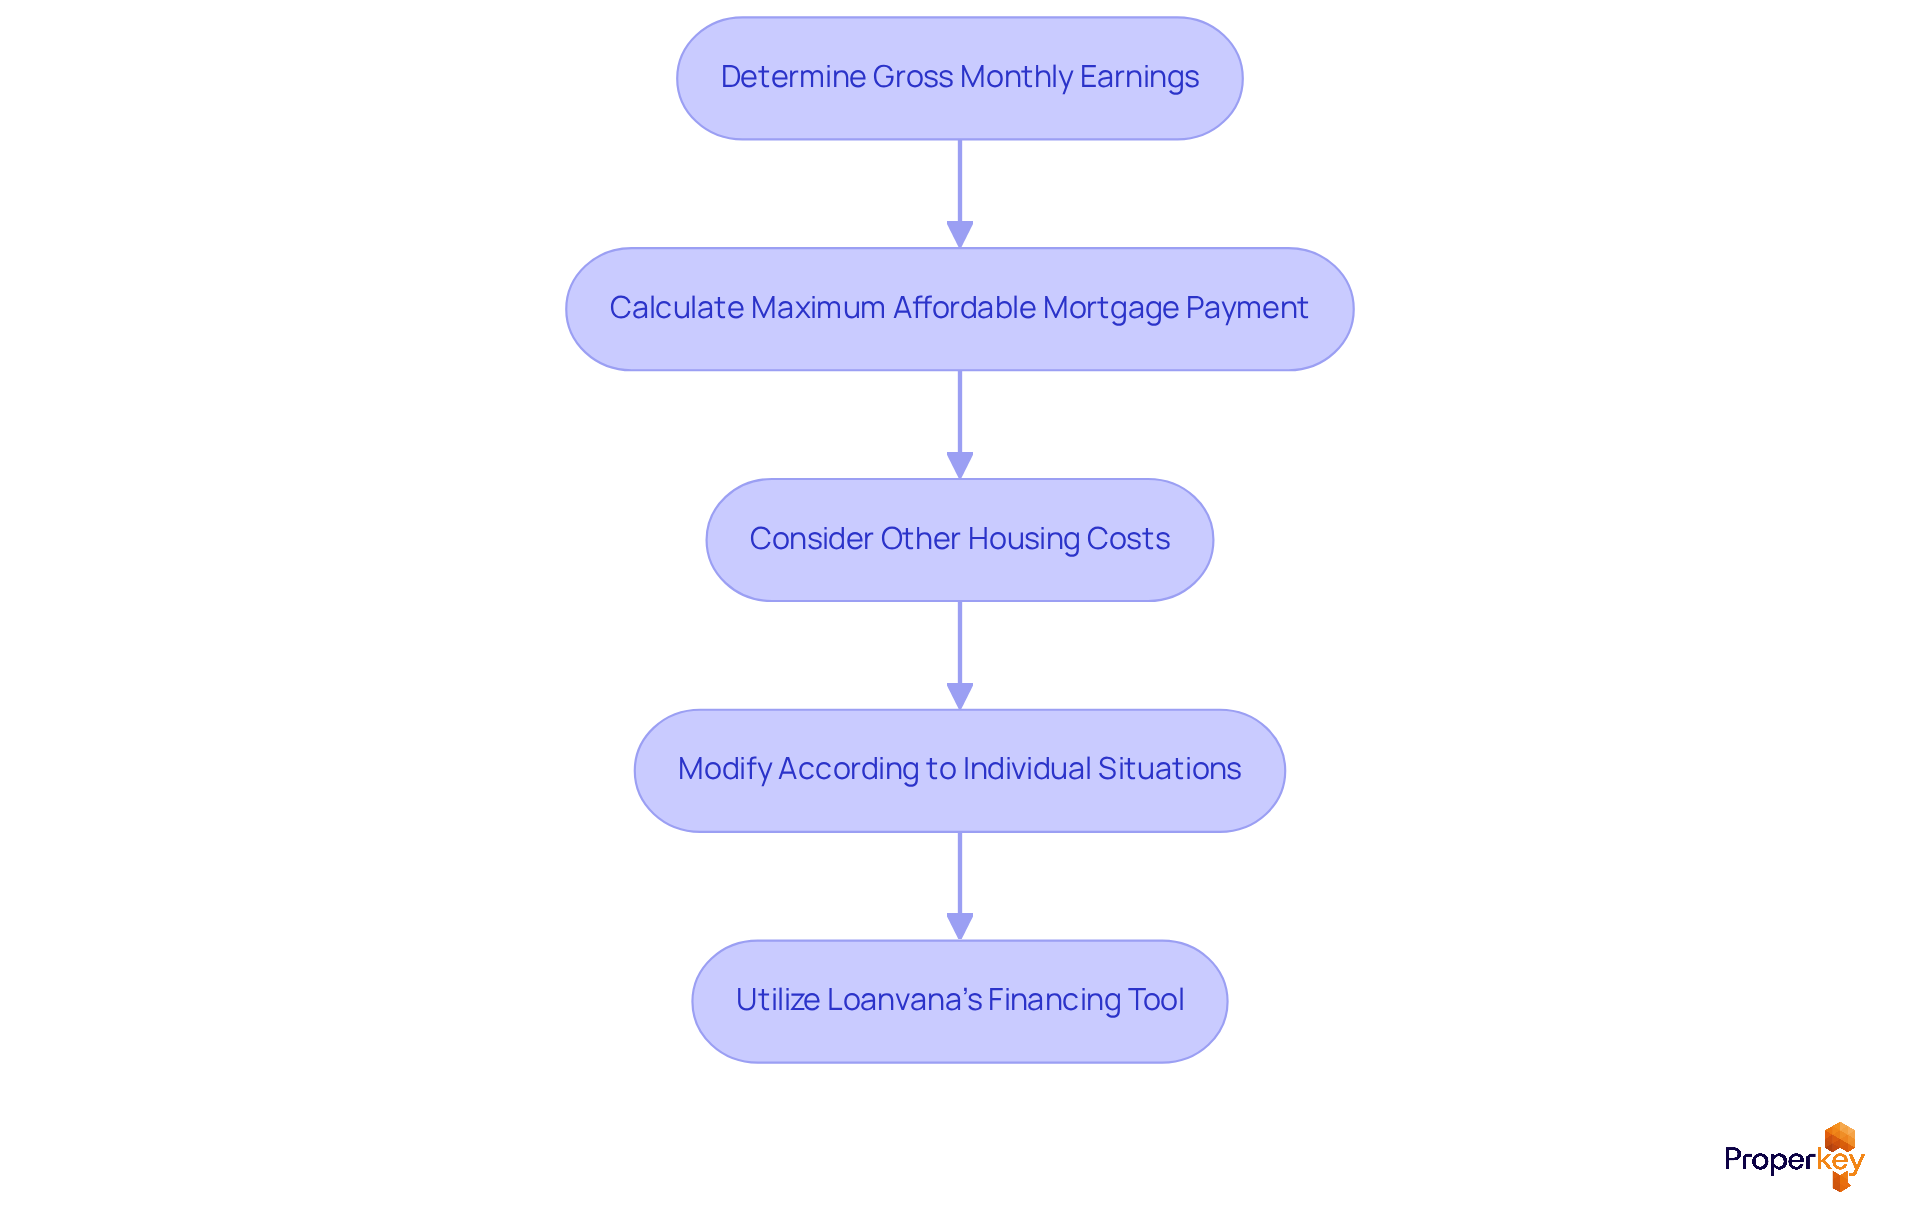
Understanding the mortgage percentage of income that should be allocated to your mortgage is crucial for financial stability. To calculate your mortgage percentage of income, follow these steps:
- Determine Your Gross Monthly Earnings: This is your total earnings before taxes and deductions. For example, if your yearly salary is $80,000, your gross monthly earnings would be roughly $6,667.
- Calculate Your Maximum Affordable Mortgage Payment: Multiply your gross monthly income by 0.28 (or 28%). Using the previous example, $6,667 x 0.28 = $1,867. Aim to keep your monthly loan payment around $1,867 to maintain a manageable mortgage percentage of income.
- Consider Other Housing Costs: Remember, your loan payment is just one piece of the housing puzzle. Include property taxes, homeowners insurance, and any homeowners association (HOA) fees in your calculations to get a complete picture of your total housing costs. In California, homeowners typically pay an effective property tax rate of about 1.1% to 1.25% of their home's purchase price. The typical housing cost in California is in the mid-$4,000s, which emphasizes the significance of planning for these extra expenses.
- Modify According to Individual Situations: If you have significant debts like student loans or credit cards, consider lowering your target percentage to maintain financial flexibility. If your total monthly debts are substantial, think about adjusting your target housing payment to ensure your mortgage percentage of income remains within a comfortable financial range. Furthermore, be mindful that elevated debt-to-income ratios can influence your loan approval prospects, so it's prudent to keep your total monthly debt commitments under 36% of your gross monthly income. Managing multiple debts can complicate your ability to afford a mortgage.
- Utilize Loanvana's Financing Tool: To simplify your loan comparison process, consider using Loanvana's financing tool, which allows you to apply once and compare hundreds of financing options side-by-side from multiple lenders. This tool provides real-time interest rates and tailored options, helping you find the best rates and terms suited to your financial situation. By incorporating this tool into your calculations, you can make more informed choices regarding your loan affordability. By leveraging tools like Loanvana, you can navigate the mortgage landscape with confidence and clarity.
Navigate Challenges in Assessing Mortgage Affordability
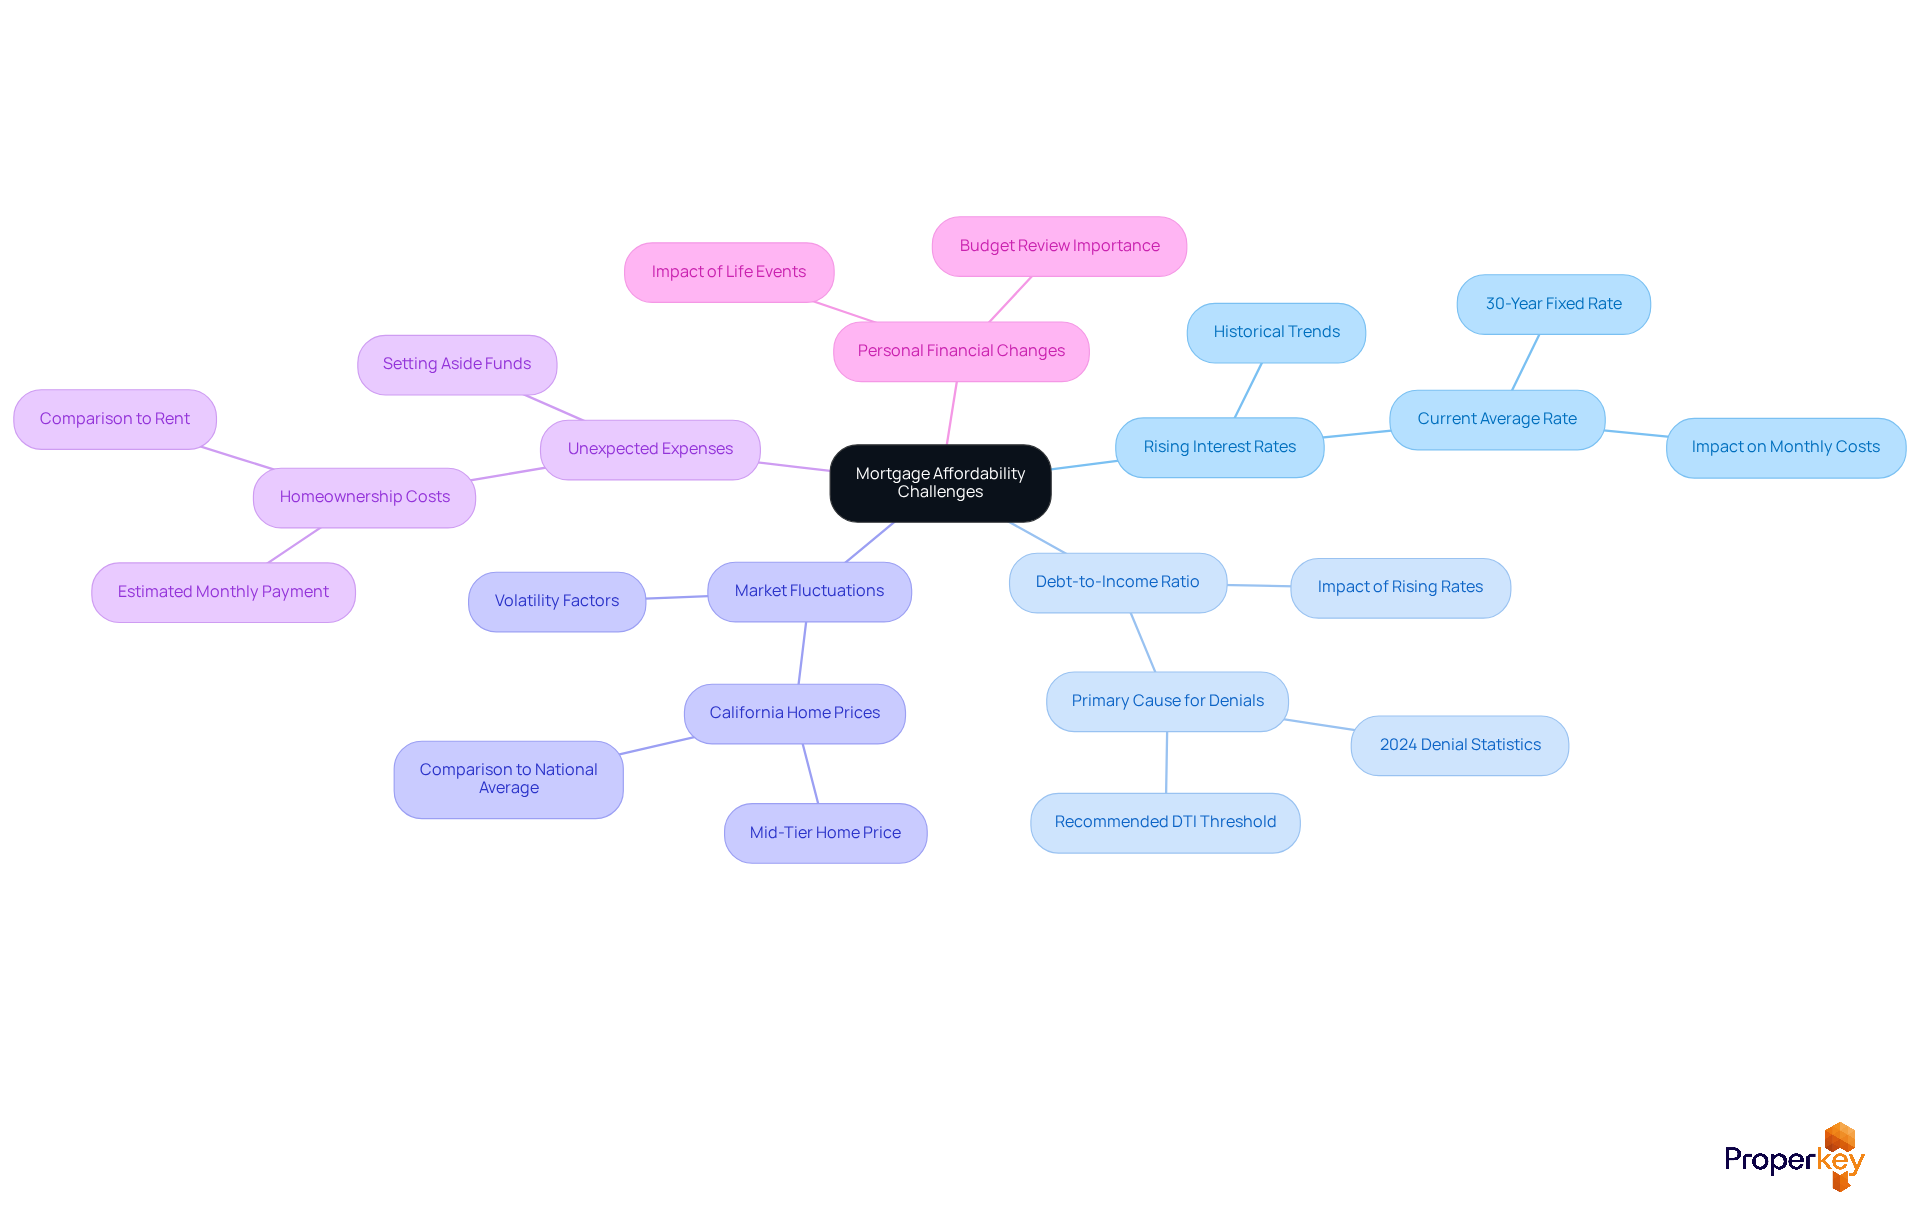
Navigating the mortgage percentage of income in California is no small feat, especially given the current economic challenges. Here are some key factors to consider:
- Rising Interest Rates: As of September 2026, the average rate for a 30-year fixed-rate loan stands at 6.69%, based on the most recent data available as of August 6, 2026. Increased interest rates can significantly raise monthly costs. It’s essential for purchasers to stay informed about current rates and consider securing advantageous terms when possible.
- Debt-to-Income Ratio (DTI): The DTI ratio is a critical metric that lenders use to evaluate affordability. In 2024, DTI was the primary cause for loan denials, accounting for 35% of cases. In contrast, credit history was responsible for 29%. Striving for a DTI of 36% or less, which includes your housing costs and other debts, is recommended. If your DTI exceeds this threshold, it may be wise to reduce existing debts before applying for a mortgage.
- Market Fluctuations: The California real estate market is known for its volatility. Mid-tier home prices are approximately $775,000, more than double the typical mid-tier home price in the U.S. Understanding local market trends is essential for assessing how they may influence home prices and your purchasing power.
- Unexpected Expenses: Homeownership often comes with unforeseen costs, such as repairs and maintenance. For instance, the estimated monthly payment for a two-bedroom home in June 2026 is about $4,600, significantly higher than the $2,700 average rent for a similar property. It's crucial to set aside some funds for these unexpected costs to avoid financial stress.
- Personal Financial Changes: Life events, such as job changes or family growth, can impact your financial situation. Consistently reviewing your budget and loan affordability is essential as situations change. For example, a standard household earning $69,000 would need to set aside approximately 36% of their monthly earnings, which reflects the mortgage percentage of income required to cover the median home loan payment, emphasizing the persistent affordability crisis in California.
To navigate these challenges, careful planning and awareness of the economic landscape are essential. In California, homeownership is becoming more complex and costly. Without a solid plan, the dream of homeownership in California may slip further out of reach.
Understand the Impact on Financial Health and Homeownership
Are you aware that the mortgage percentage of income can significantly impact your financial future in California?
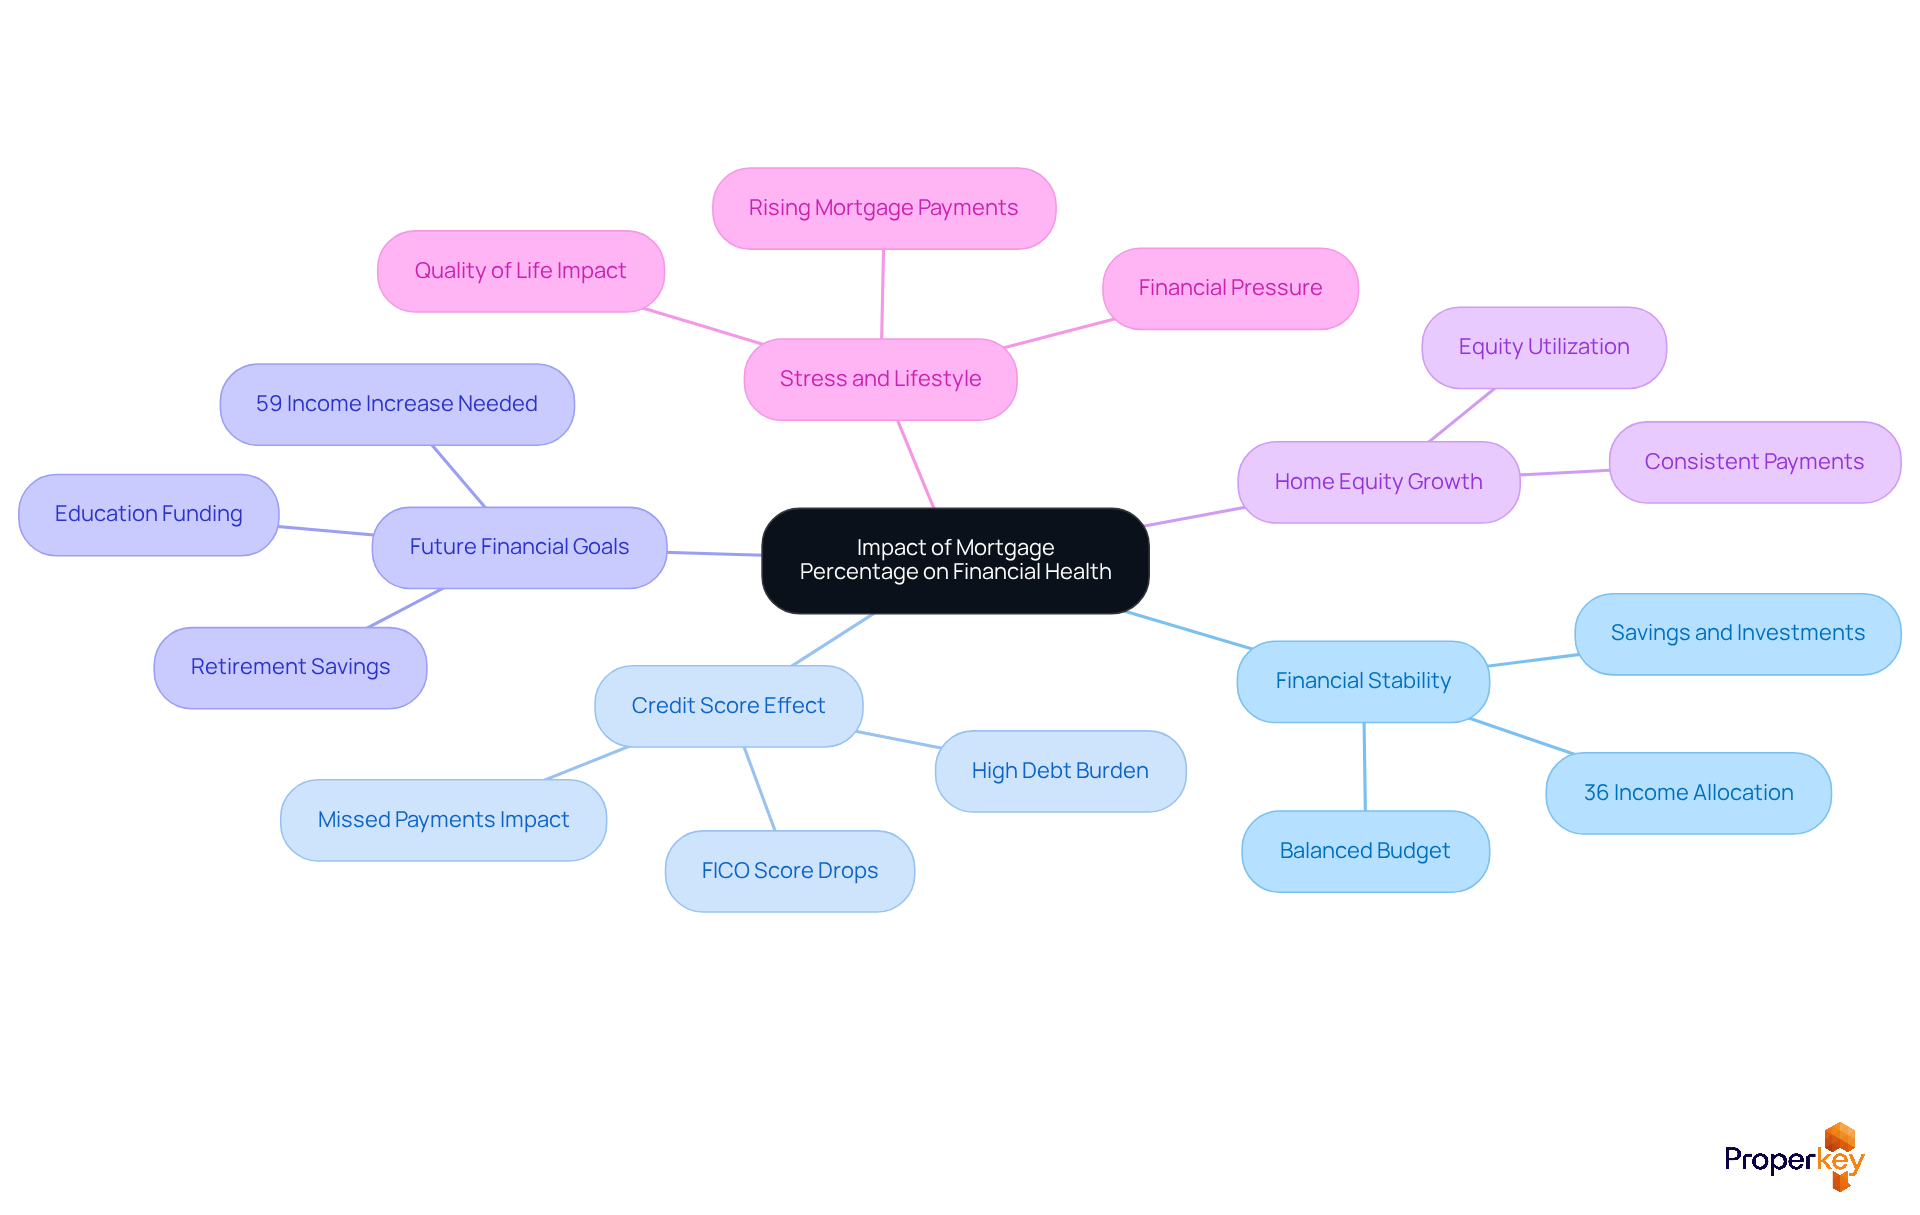
- Financial Stability: Following suggested loan percentages helps maintain a balanced budget, allowing for savings and investments in various aspects of life. For instance, a standard household earning $69,000 would need to allocate about 36% of their income to afford the median home loan cost, which can strain other financial obligations. With Loanvana's financing tool, you can apply just once and see hundreds of loan options from various lenders side-by-side, helping you find the best rates that suit your budget.
- Credit Score Effect: A high loan percentage can lead to missed payments, negatively impacting credit scores. Research shows that borrowers with initially high FICO scores may see drops due to increased debt burdens. Keeping loan installments manageable is crucial for sustaining a healthy credit profile.
- Future Financial Goals: Allocating excessive earnings to a home loan can hinder savings for retirement, education, or other financial objectives. Households should ensure their loan contributions allow for investments in these essential areas, as the average household would need to boost their income by 59% to sustain a budget of 25% for housing costs on a median-priced home.
- Home Equity Growth: A manageable loan payment facilitates consistent payments, contributing to equity growth over time. This equity can be utilized for future investments or monetary needs, providing a safety net in fluctuating markets.
- Stress and Lifestyle: Financial pressure from an excessively heavy loan can lead to stress and affect overall quality of life. Counties in California have seen significant increases in mortgage payments, highlighting the importance of maintaining a sustainable mortgage percentage of income to avoid financial distress. Ignoring these guidelines could jeopardize not just your financial stability but your overall quality of life as well.
Conclusion
Navigating the complexities of home buying in high-cost areas like California requires a solid understanding of mortgage percentages. Keeping mortgage payments below 28% of gross monthly income is crucial for maintaining financial stability while managing housing costs. This approach safeguards against over-leveraging. It also allows for a balanced budget that accommodates essential living expenses.
Here are key insights on calculating and assessing mortgage affordability:
- Determining gross monthly earnings
- Factoring in additional housing costs
- Adjusting for personal financial situations
The discussion also highlighted the challenges posed by rising interest rates and fluctuating market conditions. Navigating the current housing market can feel overwhelming, especially with rising interest rates and unpredictable conditions. Maintaining a healthy debt-to-income ratio is essential. Utilizing tools like Loanvana can empower buyers to make informed decisions by comparing various loan options tailored to their financial needs.
Failing to prioritize mortgage affordability can lead to financial strain and hinder personal goals. Mastering the mortgage percentage of income isn’t just about getting a home; it’s about building long-term financial health and reaching your personal goals. By prioritizing affordability and planning for unexpected expenses, you can navigate the housing market with confidence. By embracing these principles, you can secure not just a home, but a stable financial future that aligns with your aspirations.
Frequently Asked Questions
What is the mortgage percentage of income?
The mortgage percentage of income reflects the portion of a borrower's gross monthly earnings that is allocated to loan installments.
What is the recommended mortgage percentage of income for homebuyers?
Financial specialists typically recommend that the mortgage percentage of income should not exceed 28% of total earnings.
Why is the 28% rule important in California?
The 28% rule is vital in California due to the state's housing costs, which far exceed the national average. It helps ensure that homeowners can manage their loan obligations comfortably while covering other necessary living costs.
What is the median home price in California?
The median home price in California is approximately $697,000.
How much of their earnings do homeowners in the Los Angeles-Long Beach-Anaheim region allocate to housing costs?
Homeowners in the Los Angeles-Long Beach-Anaheim region dedicate around 72.4% of their earnings to housing costs.
What percentage of income do homeowners in Riverside-San Bernardino-Ontario allocate towards their mortgage?
Homeowners in Riverside-San Bernardino-Ontario allocate approximately 44.9% of their earnings towards their mortgage percentage of income.
How do Fresno residents manage their housing payments compared to other regions?
Fresno residents manage to keep their housing payments at 41.4% of income, suggesting a more balanced approach to homeownership compared to other regions.
What do experts say about affordable mortgages?
Experts emphasize that an affordable mortgage allows individuals to cover monthly housing costs while still leaving room for savings and emergencies.
What should potential buyers consider when assessing their financial situation?
Potential buyers should carefully assess their monetary situations and consider all housing expenses, including property taxes and insurance, to determine what is truly affordable.
How can buyers find the best loan options?
Buyers can utilize Loanvana's financing tool to compare hundreds of loan options side-by-side from multiple lenders, ensuring they find the best rates and terms that align with their financial capabilities.
List of Sources
- Define Mortgage Percentage of Income and Its Importance
- Mapped: California Metros Where Homebuyers Have To Fork Out Biggest Share of Income To Afford a Mortgage (https://realtor.com/news/trends/california-metros-homeowners-income-mortgage-payments)
- Californians spend ‘almost half their income’ on a home. See 10 priciest spots (https://sacbee.com/news/california/article314607236.html)
- What’s the average mortgage payment in Idaho? (https://rocketmortgage.com/learn/average-mortgage-payment-idaho)
- Beyond the 28% Rule: What Percentage of Your Income Should Go to Your Mortgage in 2026? | Hudson Valley Credit Union (https://hvcu.org/learning-center/beyond-the-28-rule)
- What Percentage of Your Income Should Go to Mortgage? | Chase (https://chase.com/personal/mortgage/education/financing-a-home/what-percentage-income-towards-mortgage)
- Calculate Your Mortgage Percentage of Income
- What Percentage of My Income Should Go Toward a Mortgage? - Preferred Rate (https://preferredrate.com/blog/what-percentage-of-my-income-should-go-toward-a-mortgage)
- What Is the Average Mortgage Payment in California in 2026? (https://amerisave.com/learn/what-is-the-average-mortgage-payment-in-california-in)
- What Percentage of Your Income Should Go to Mortgage? | Chase (https://chase.com/personal/mortgage/education/financing-a-home/what-percentage-income-towards-mortgage)
- Beyond the 28% Rule: What Percentage of Your Income Should Go to Your Mortgage in 2026? | Hudson Valley Credit Union (https://hvcu.org/learning-center/beyond-the-28-rule)
- Homebuying and Mortgage Statistics - NerdWallet (https://nerdwallet.com/mortgages/learn/home-buying-mortgage-data)
- Navigate Challenges in Assessing Mortgage Affordability
- Renters Reassess Homeownership as Affordability Challenges Persist (https://arbor.com/blog/renters-reassess-homeownership-as-affordability-challenges-persist)
- Failing the Threshold: The Impact of Rising Interest Rates on Mortgage Borrowing (https://stlouisfed.org/on-the-economy/2026/may/impact-rising-interest-rates-mortgage-borrowing)
- Mortgage Rates (https://freddiemac.com/pmms)
- California Housing Affordability Tracker (2nd Quarter 2026) [EconTax Blog] (https://lao.ca.gov/LAOEconTax/Article/Detail/793)
- Mortgage payments have nearly doubled in the past decade. These counties saw the biggest rise (https://kcra.com/article/mortgage-rates-impact-homeowners/68151086)
- Understand the Impact on Financial Health and Homeownership
- Data Spotlight: The Impact of Changing Mortgage Interest Rates | Consumer Financial Protection Bureau (https://consumerfinance.gov/data-research/research-reports/data-spotlight-the-impact-of-changing-mortgage-interest-rates)
- How Your Mortgage Affects Your Credit Score | Bankrate (https://bankrate.com/mortgages/how-mortgage-affects-credit-score)
- Mortgage payments have nearly doubled in the past decade. These counties saw the biggest rise (https://kcra.com/article/mortgage-rates-impact-homeowners/68151086)
- How mortgage payments impact your credit score (https://milliman.com/en/insight/how-mortgage-payments-impact-your-credit-score)