Secure Your Mortgage for a 1 Million Dollar Home in 6 Steps
Introduction
Many potential homeowners feel overwhelmed by the complexities of securing a mortgage for high-value properties. Understanding the steps to secure financing not only empowers you but also ensures you are well-prepared for the financial commitment ahead. What challenges might arise during this process, and how can you effectively overcome them to achieve your dream of homeownership? Let’s explore the essential steps to secure a mortgage for your dream home, ensuring you make informed and confident decisions.
Assess Your Financial Readiness and Credit Score
Navigating the complexities of selling your home can be daunting, especially when it comes to understanding your financial readiness.
- Check Your Credit Score: Start by obtaining your credit report from the major credit bureaus: Equifax, Experian, and TransUnion. Did you know that lenders often favor a credit score of at least 700 for advantageous loan rates? If your score falls short, consider strategies to improve it, such as paying down existing debts and correcting any inaccuracies on your report. As of August 2026, the average FICO Score in California is around 713, indicating a generally healthy credit landscape.
- Calculate Your Debt-to-Income Ratio (DTI): This ratio is crucial as it compares your monthly debt payments to your gross monthly income. Did you know that lenders often favor a debt-to-income ratio of 36% or lower? To calculate your DTI, divide your total monthly debt payments by your gross monthly income and multiply by 100. A lower DTI can enhance your mortgage eligibility.
- Assess your savings: It's crucial to have enough savings for a down payment, typically around 20% for a mortgage for a 1 million dollar home, which amounts to $200,000. Furthermore, allocate resources for closing expenses, which can vary from 2% to 5% of the borrowing amount. Having a strong savings cushion can significantly enhance your economic preparedness. Imagine facing unexpected financial strain during your home buying journey-adequate savings can help you avoid this pitfall.
- Evaluate Your Employment Stability: Lenders favor applicants with consistent income. Ideally, you should have at least two years of stable employment in the same field. If you are self-employed, be prepared to provide additional documentation, such as tax returns and profit-loss statements, to demonstrate your income stability.
- Evaluate Additional Monetary Responsibilities: Examine any other monetary commitments that may affect your capacity to make housing payments, such as student debts or vehicle payments. Comprehending your complete monetary situation will assist you in assessing your preparedness for a loan.
- Utilize Loanvana's Financing Tool: To simplify your mortgage process, consider using Loanvana's financing tool, which enables you to apply once and compare hundreds of financing options side-by-side from various lenders. This can help you find the best rates and terms tailored to your financial situation. Additionally, Properkey provides a complimentary financial analysis service to assist you in understanding your options before committing.
Taking these steps not only prepares you for a successful sale but also empowers you to make informed financial decisions that can shape your future.
Explore Mortgage Options for High-Value Homes
Navigating the complexities of jumbo financing can be daunting for many home sellers, especially when faced with high property values and strict lending criteria.
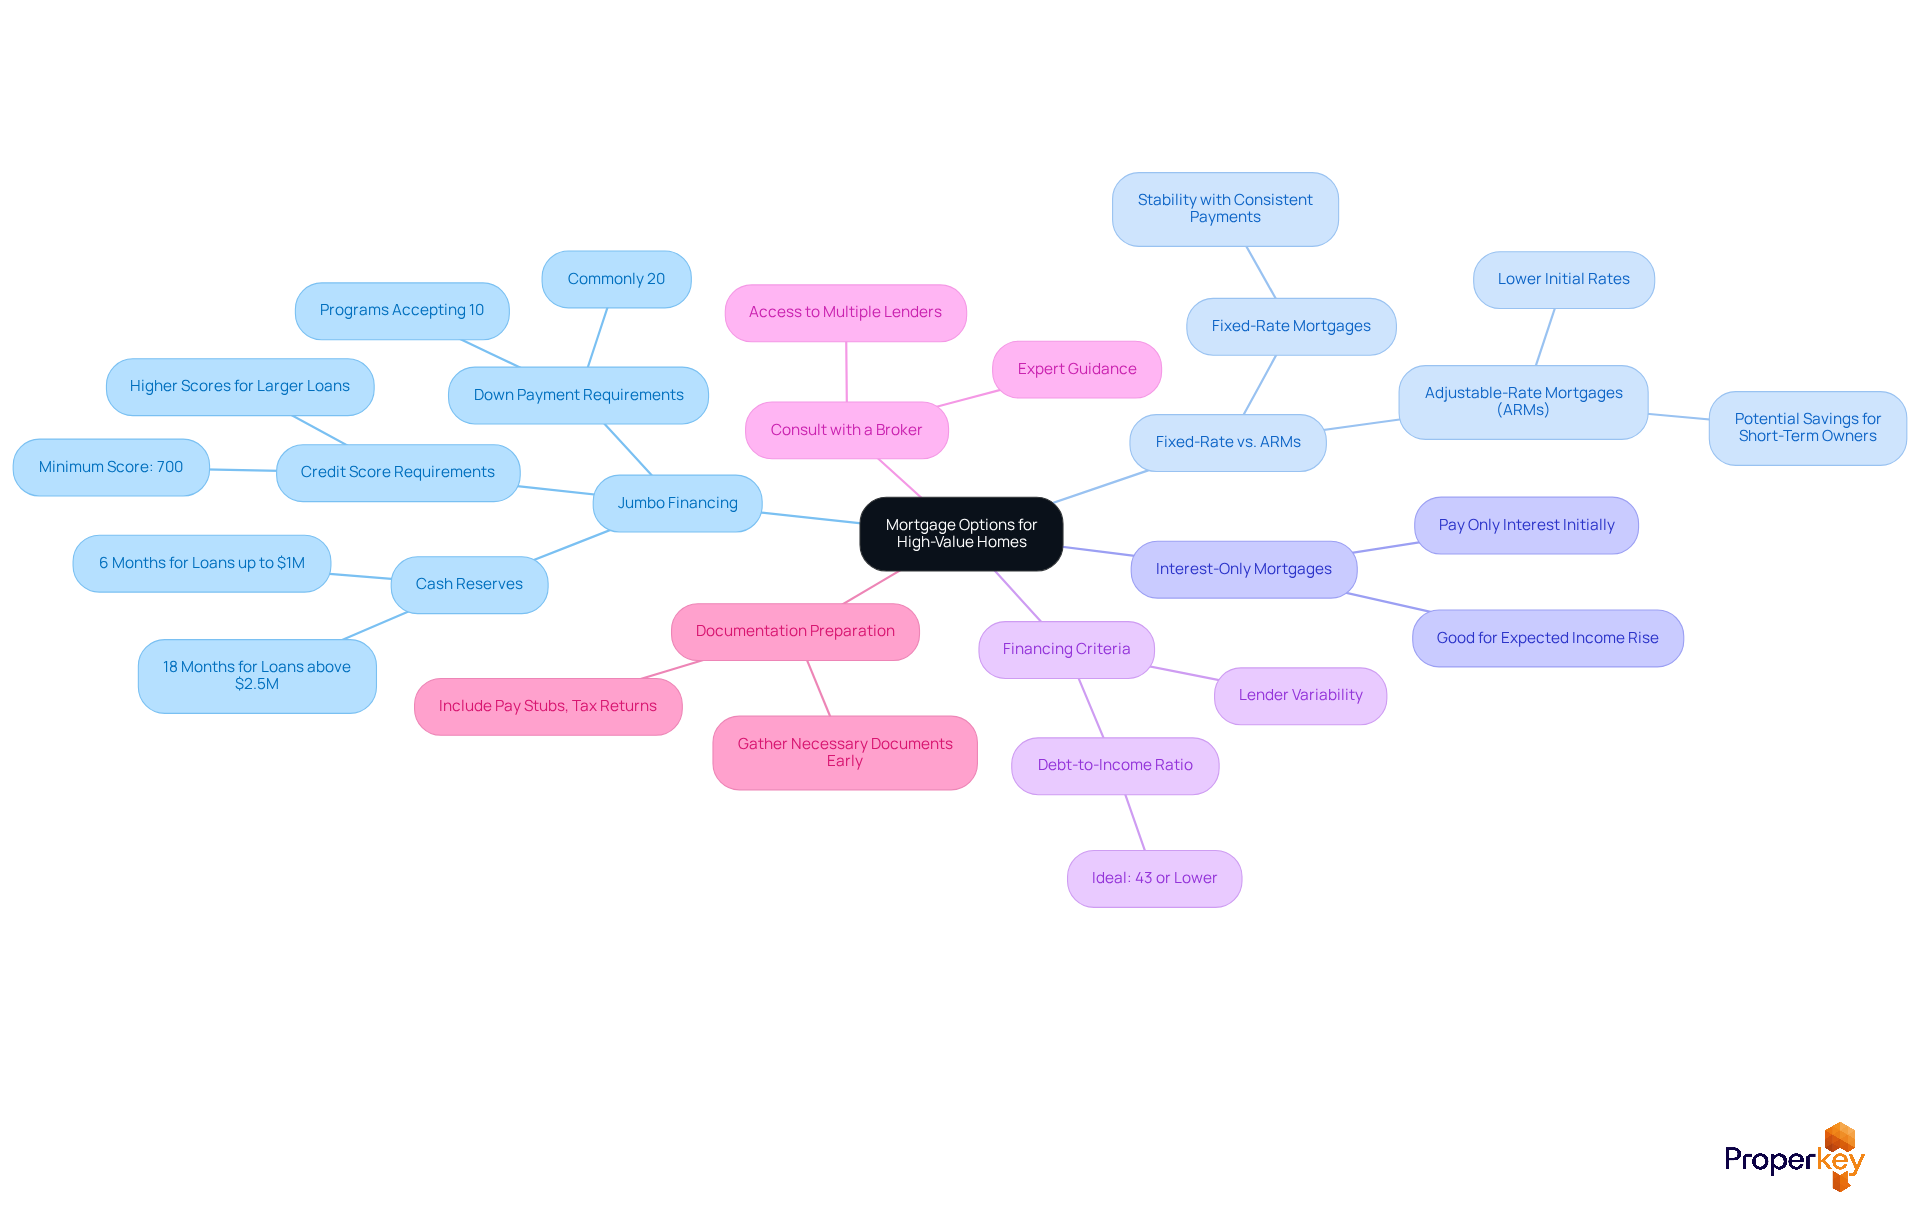
- Understand Jumbo Financing: Conventional mortgages usually have limits near $832,750 in California. This makes a mortgage for a 1 million dollar home crucial for properties valued at $1 million or higher. These products come with stricter credit standards. You’ll often need a minimum credit score of 700. Plus, be prepared for potentially higher interest rates due to the increased risk for lenders.
- Fixed-Rate vs. Adjustable-Rate Mortgages (ARMs): Fixed-rate mortgages provide stability with consistent monthly payments, ideal for long-term homeowners. But what if you could start with lower rates that fluctuate? ARMs offer just that, making them suitable for those planning to sell or refinance before the rate adjusts. Given the current competitive rates, ARMs can offer significant savings, especially for first-time buyers.
- Consider Interest-Only Mortgages: These financial products enable you to pay solely the interest for a preliminary period. This can be beneficial if you expect a rise in income or intend to sell the property before principal payments begin. This option can help manage cash flow during the early years of homeownership.
- Research Financing Criteria: Jumbo mortgage criteria differ by institution, with many anticipating a down payment of at least 20%. However, some programs now accept down payments as low as 10% for well-qualified borrowers. It's essential to evaluate providers to discover the best match for your monetary circumstances, particularly when looking for a mortgage for a 1 million dollar home, as some may present more advantageous conditions or reduced charges.
- Consult with a Mortgage Broker: Engaging a mortgage broker can simplify the process of securing a jumbo financing option. Brokers have access to various institutions and can assist you in navigating the intricacies of high-value home funding, ensuring you discover a product that matches your requirements and monetary objectives.
- Prepare for Documentation: To expedite the underwriting process, gather necessary documentation early, including recent pay stubs, tax returns, and asset statements. Lenders usually demand a comprehensive assessment of your monetary situation, particularly for jumbo loans, where the stakes are greater. Being proactive can help avoid delays and ensure a smoother approval process. Understanding these financing options can be the key to unlocking your dream home while ensuring financial stability.
Gather Required Documentation for Your Application
Navigating the mortgage application process can be daunting, especially when it comes to gathering the right documentation.
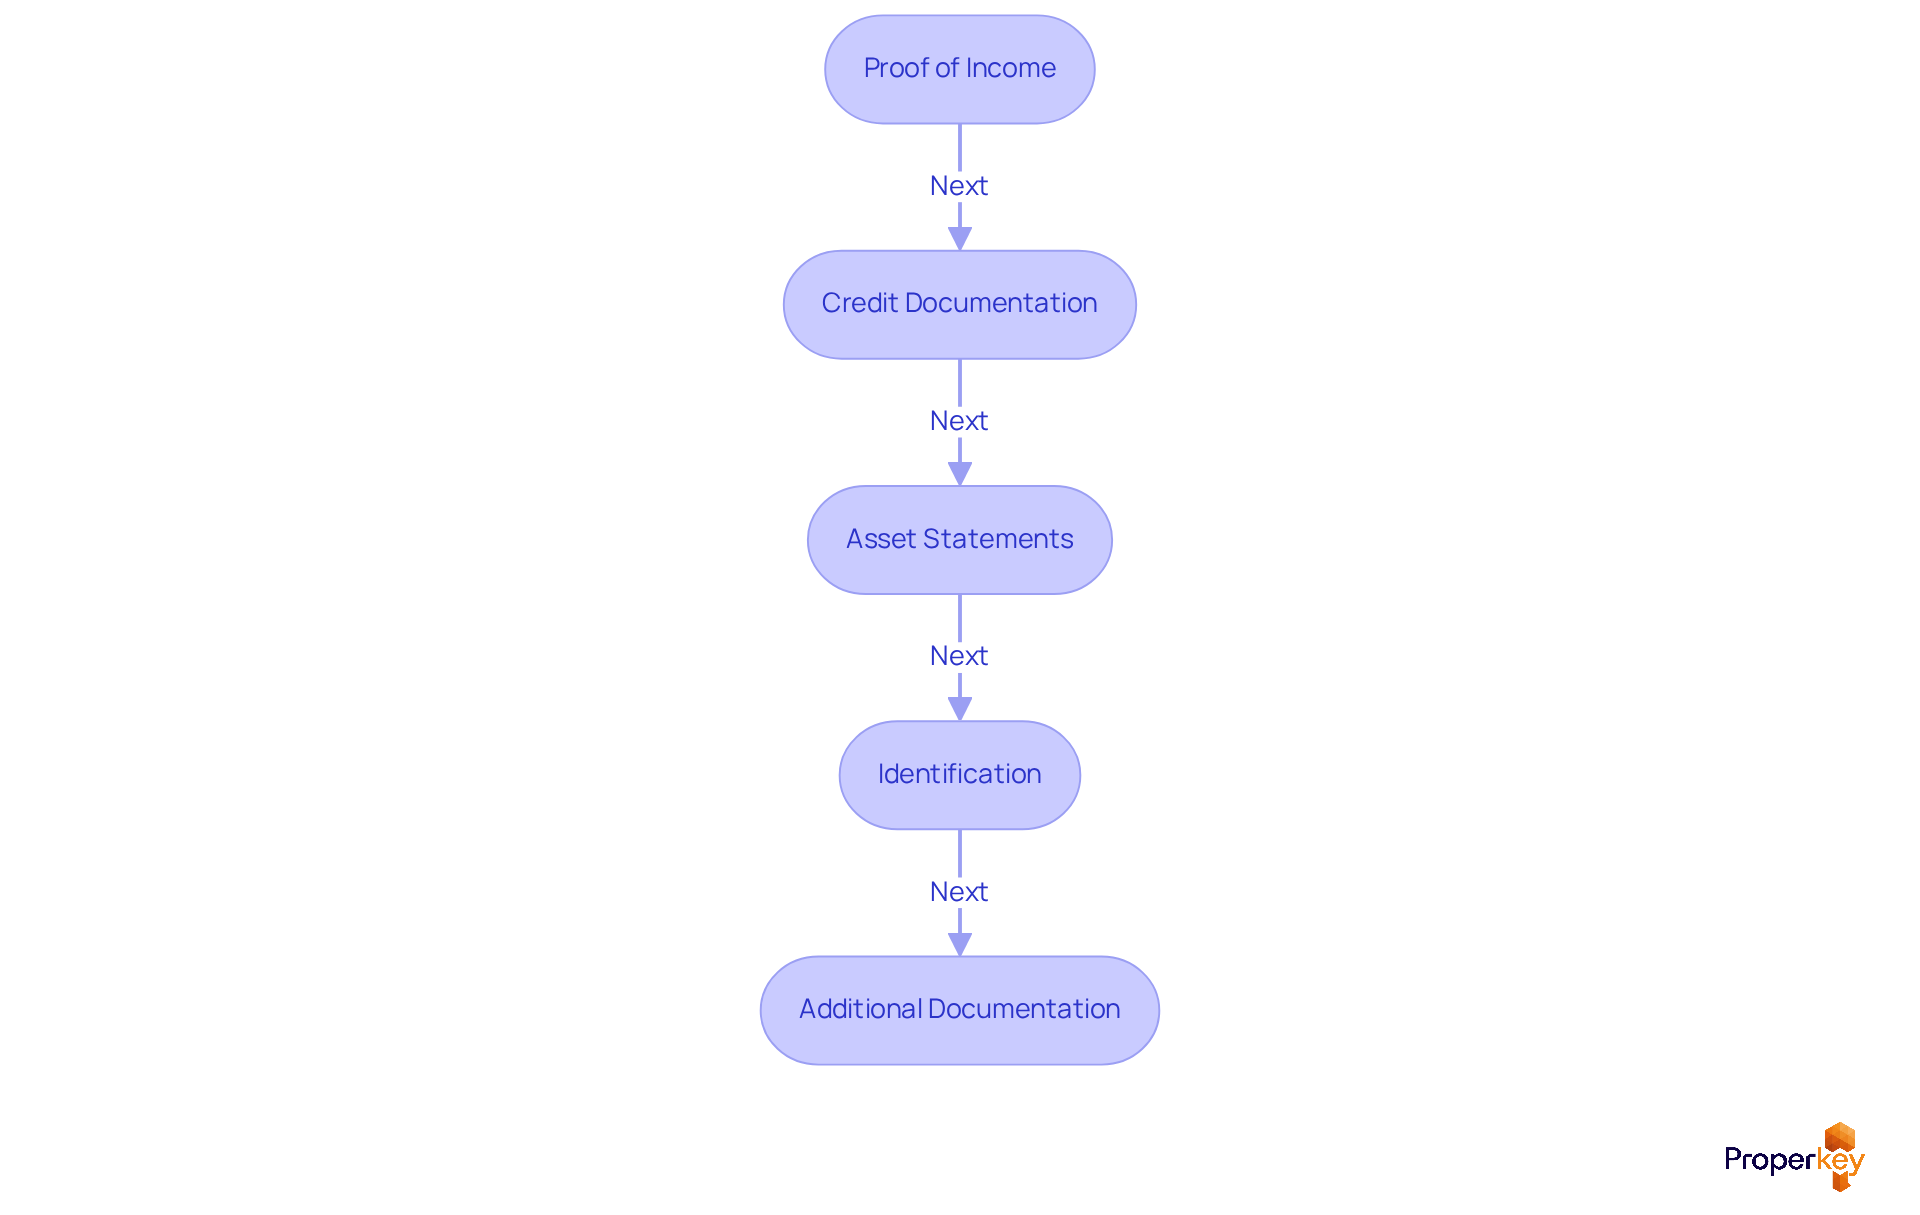
- Proof of Income: It’s crucial to provide thorough income documentation, as this helps financial institutions assess your economic stability and ability to repay the mortgage. Collect the most recent 30 days of pay stubs and W-2 forms for the past two years. If you’re self-employed, prepare profit and loss statements along with tax returns for the last two years.
- Credit Documentation: Have your credit report ready, as lenders will examine it during the application process. Keep in mind that they will conduct a hard credit check, which may temporarily lower your credit score. Be prepared to address any inconsistencies or negative notes that may appear on your report, as these can impact your loan approval.
- Asset Statements: Make sure to gather your bank statements from all accounts-checking, savings, and investments-for the last 60 days. This documentation is vital for demonstrating your financial stability and your ability to cover the down payment and closing costs associated with your loan. Lenders typically require these statements to evaluate your overall financial situation.
- Identification: Provide a government-issued photo ID, such as a driver’s license or passport, along with your Social Security number. This is necessary for verification purposes and to confirm your identity during the mortgage application process.
- Additional Documentation: Depending on your personal circumstances, you may need to submit additional documents. This could include divorce decrees, child support agreements, rental payment history, or gift letters if your down payment is funded by a family member. Being prepared with these documents can facilitate a smoother application process and help you avoid delays.
Furthermore, consider using Loanvana's financing tool, which enables you to apply once and compare hundreds of financing options side-by-side from various providers. This can simplify your financing process and help you secure the best rates available. Being well-prepared not only streamlines your application but also positions you for the best possible financing options available.
Submit Your Mortgage Application and Understand the Process
Choosing the right financial institution can be daunting, but it’s crucial for a smooth home buying experience.
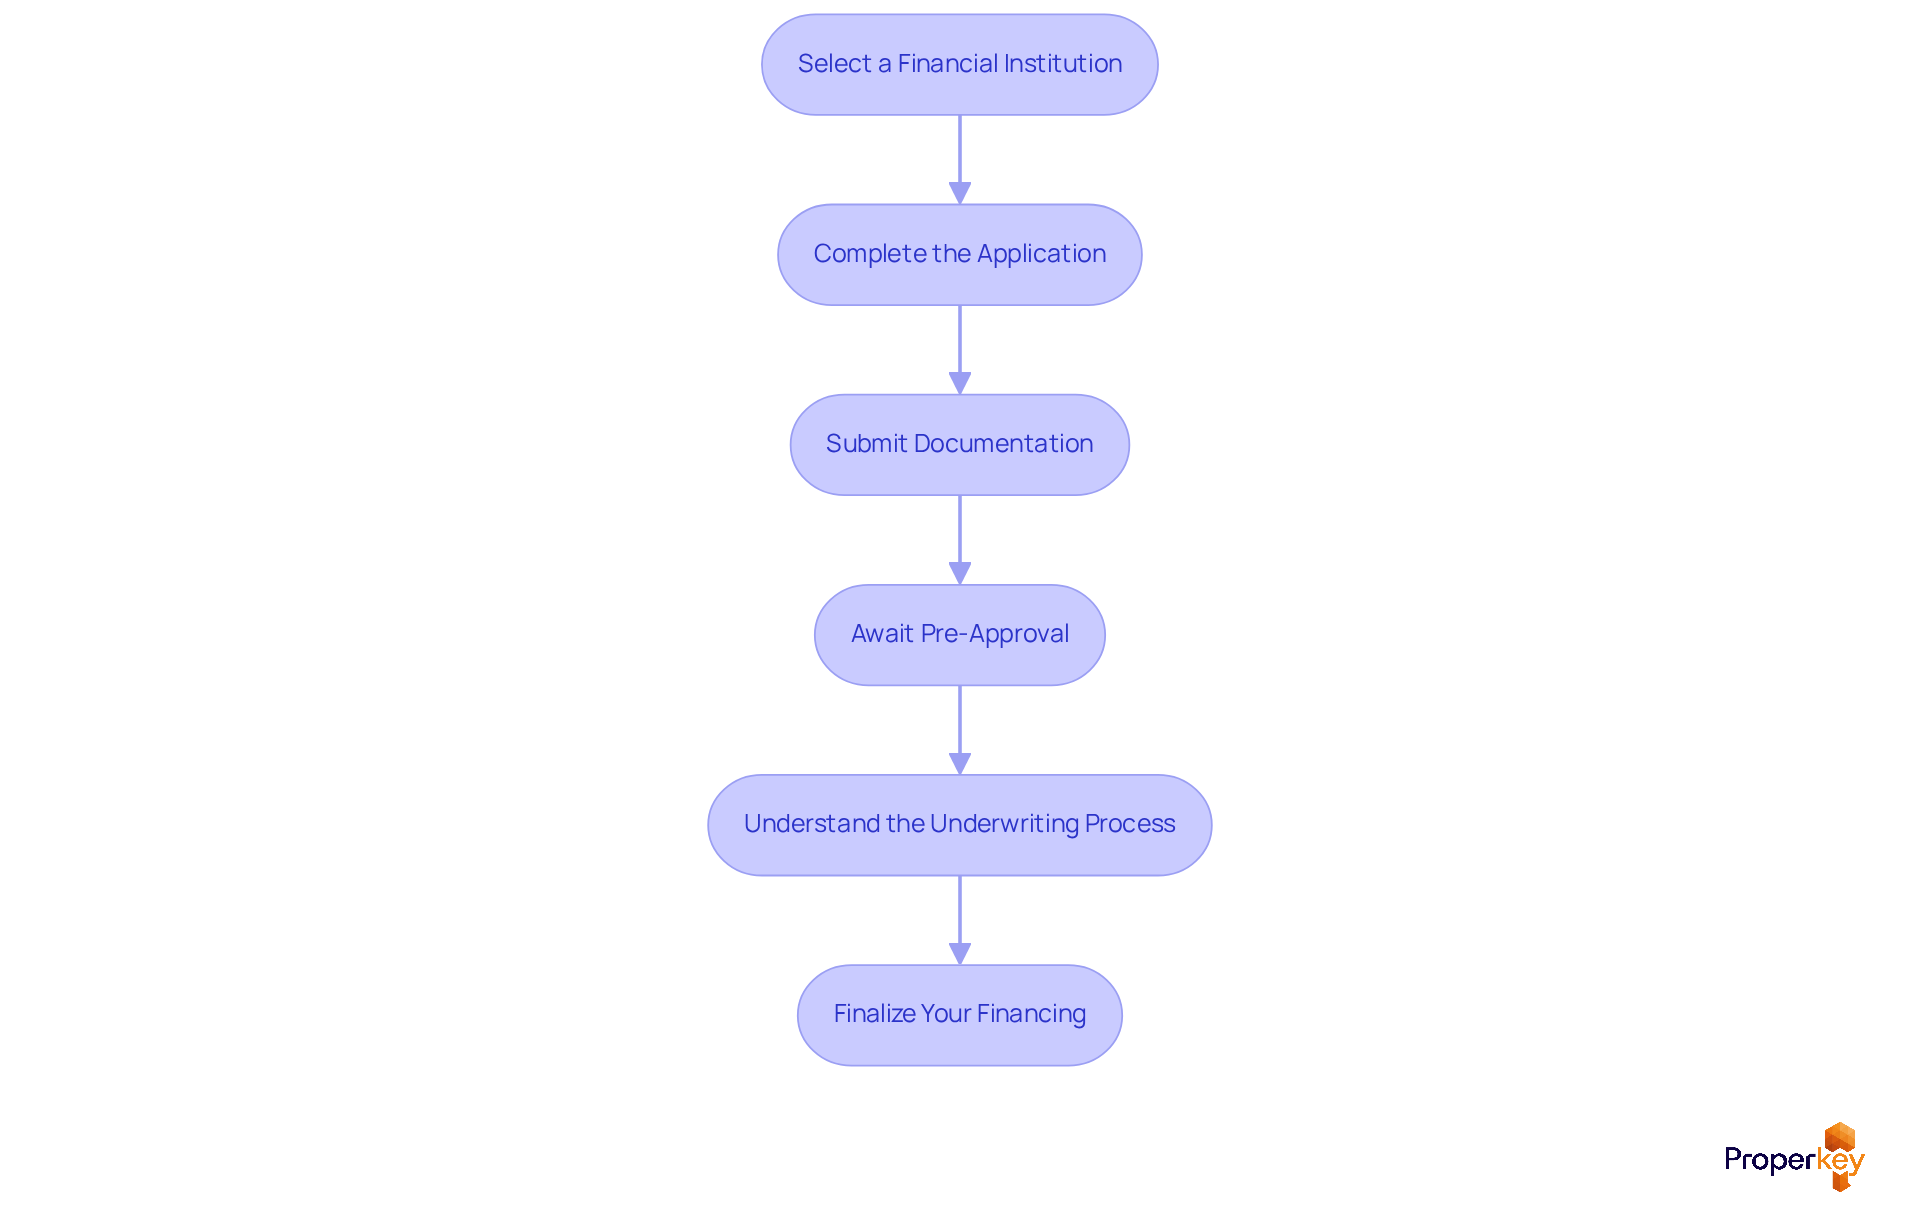
- Select a Financial Institution: Begin your journey by exploring lenders that focus on jumbo loans. Look for those with competitive rates and favorable terms. Assess customer service and the institution's reputation, as these factors can significantly influence your experience. For instance, opting for a lender with a solid history in California can simplify your financing process.
- Complete the Application: Accurately fill out the mortgage application form, providing comprehensive details about your monetary situation, employment history, and the property you intend to purchase. Getting this step right is key to showing lenders your true financial picture.
- Submit Documentation: Alongside your application, submit all necessary documentation, including recent pay stubs, tax returns, and bank statements. Ensuring that your paperwork is complete can help avoid delays in processing and keep your application on track.
- Await Pre-Approval: After submission, the financial institution will review your application and documentation. This process can take anywhere from a few days to a couple of weeks, depending on the efficiency of the financial institution. Be prepared for potential requests for additional information or clarification during this time.
- Understand the Underwriting Process: After pre-approval, your application moves to underwriting, where lenders evaluate your risk - this is where the real scrutiny begins. This stage may involve a home appraisal and further documentation requests. Understanding this process can help you anticipate what to expect and prepare accordingly.
- Finalize Your Financing: After underwriting, if approved, you will receive an offer detailing the terms. Review this carefully and ensure it aligns with your financial goals before proceeding to close the loan. In California, the whole financing process usually lasts 30 to 45 days from accepted offer to closing, so remaining organized is essential. Understanding these steps not only streamlines your financing journey but also empowers you to make informed decisions that align with your financial future.
Compare Mortgage Offers and Understand Terms
Navigating the mortgage landscape can feel daunting, especially when faced with a myriad of options and terms. Here’s how to simplify the process and ensure you’re making informed decisions:
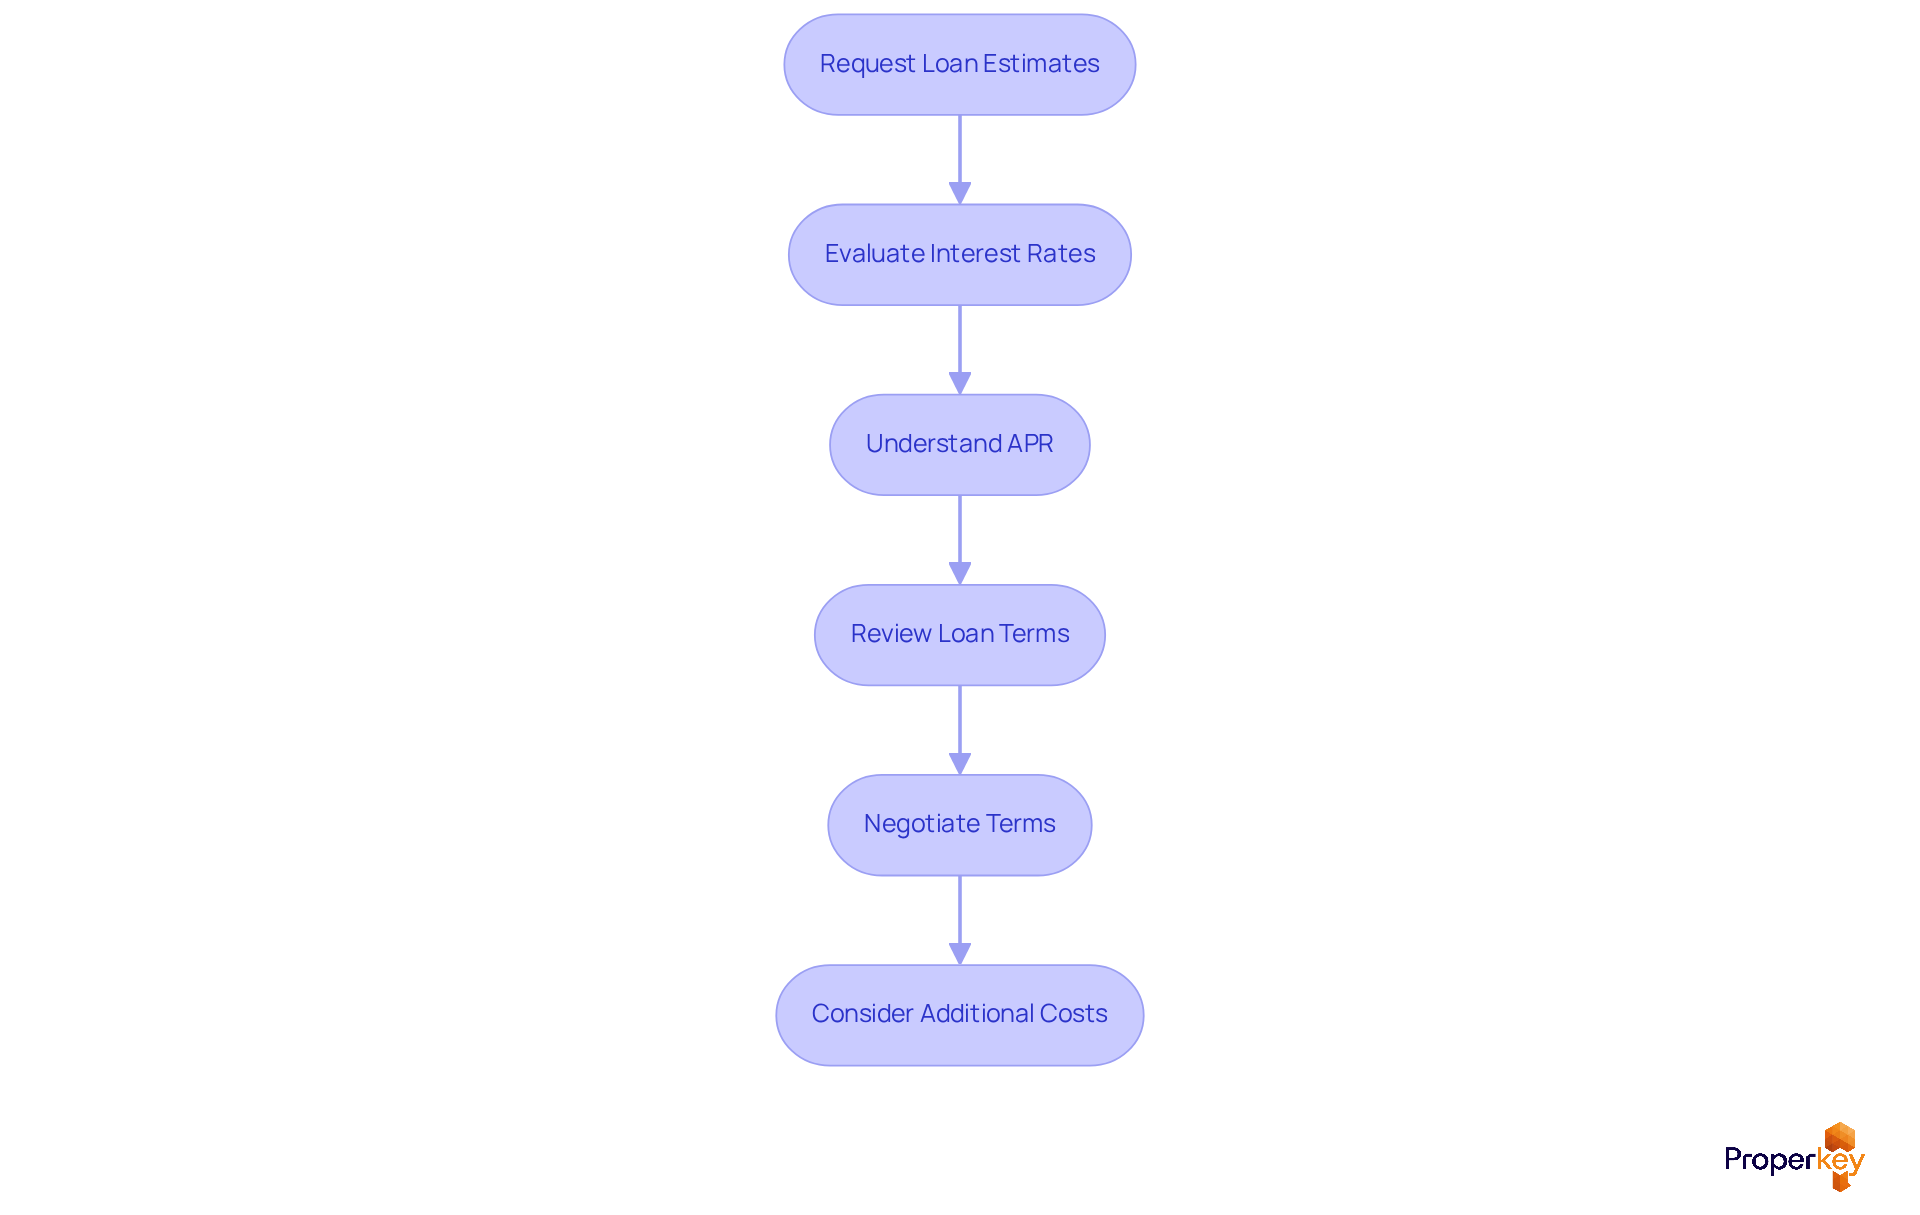
- Request Loan Estimates: After submitting your mortgage application, financial institutions will provide Loan Estimates that outline the mortgage terms, including interest rates, monthly payments, and closing costs. To ensure you get the best deal, request estimates from various financial institutions for comparison.
- Evaluate Interest Rates: Comparing interest rates from various lenders is essential; even a slight difference can lead to substantial savings over time. As of August 2026, the average interest rate for a 30-year fixed mortgage in California is around 6.70%, while a 15-year fixed mortgage averages 6.11%.
- Understand APR: The Annual Percentage Rate (APR) includes the interest rate as well as any fees or extra expenses related to the borrowing. This metric offers a more comprehensive view of the total cost, enabling improved comparisons.
- Review Loan Terms: Pay close attention to the loan term options (15, 20, or 30 years) and whether the mortgage is fixed or adjustable. These factors can significantly influence your monetary strategy and long-term objectives.
- Negotiate Terms: Feel free to engage with your lenders about your options. Ask about lowering fees or obtaining a better interest rate based on your economic profile and competing offers from other lenders. This proactive strategy can result in significant savings throughout the duration of your loan.
- Consider Additional Costs: Keep in mind that your monthly payment usually includes more than just principal and interest; taxes and insurance can add up quickly. Understanding these components is essential for accurate budgeting and financial planning.
By taking the time to understand these elements, you can position yourself for financial success in your home-selling journey.
Finalize Your Mortgage and Prepare for Closing
As you approach the final stages of selling your home, understanding the closing process is crucial to ensure a smooth transition.
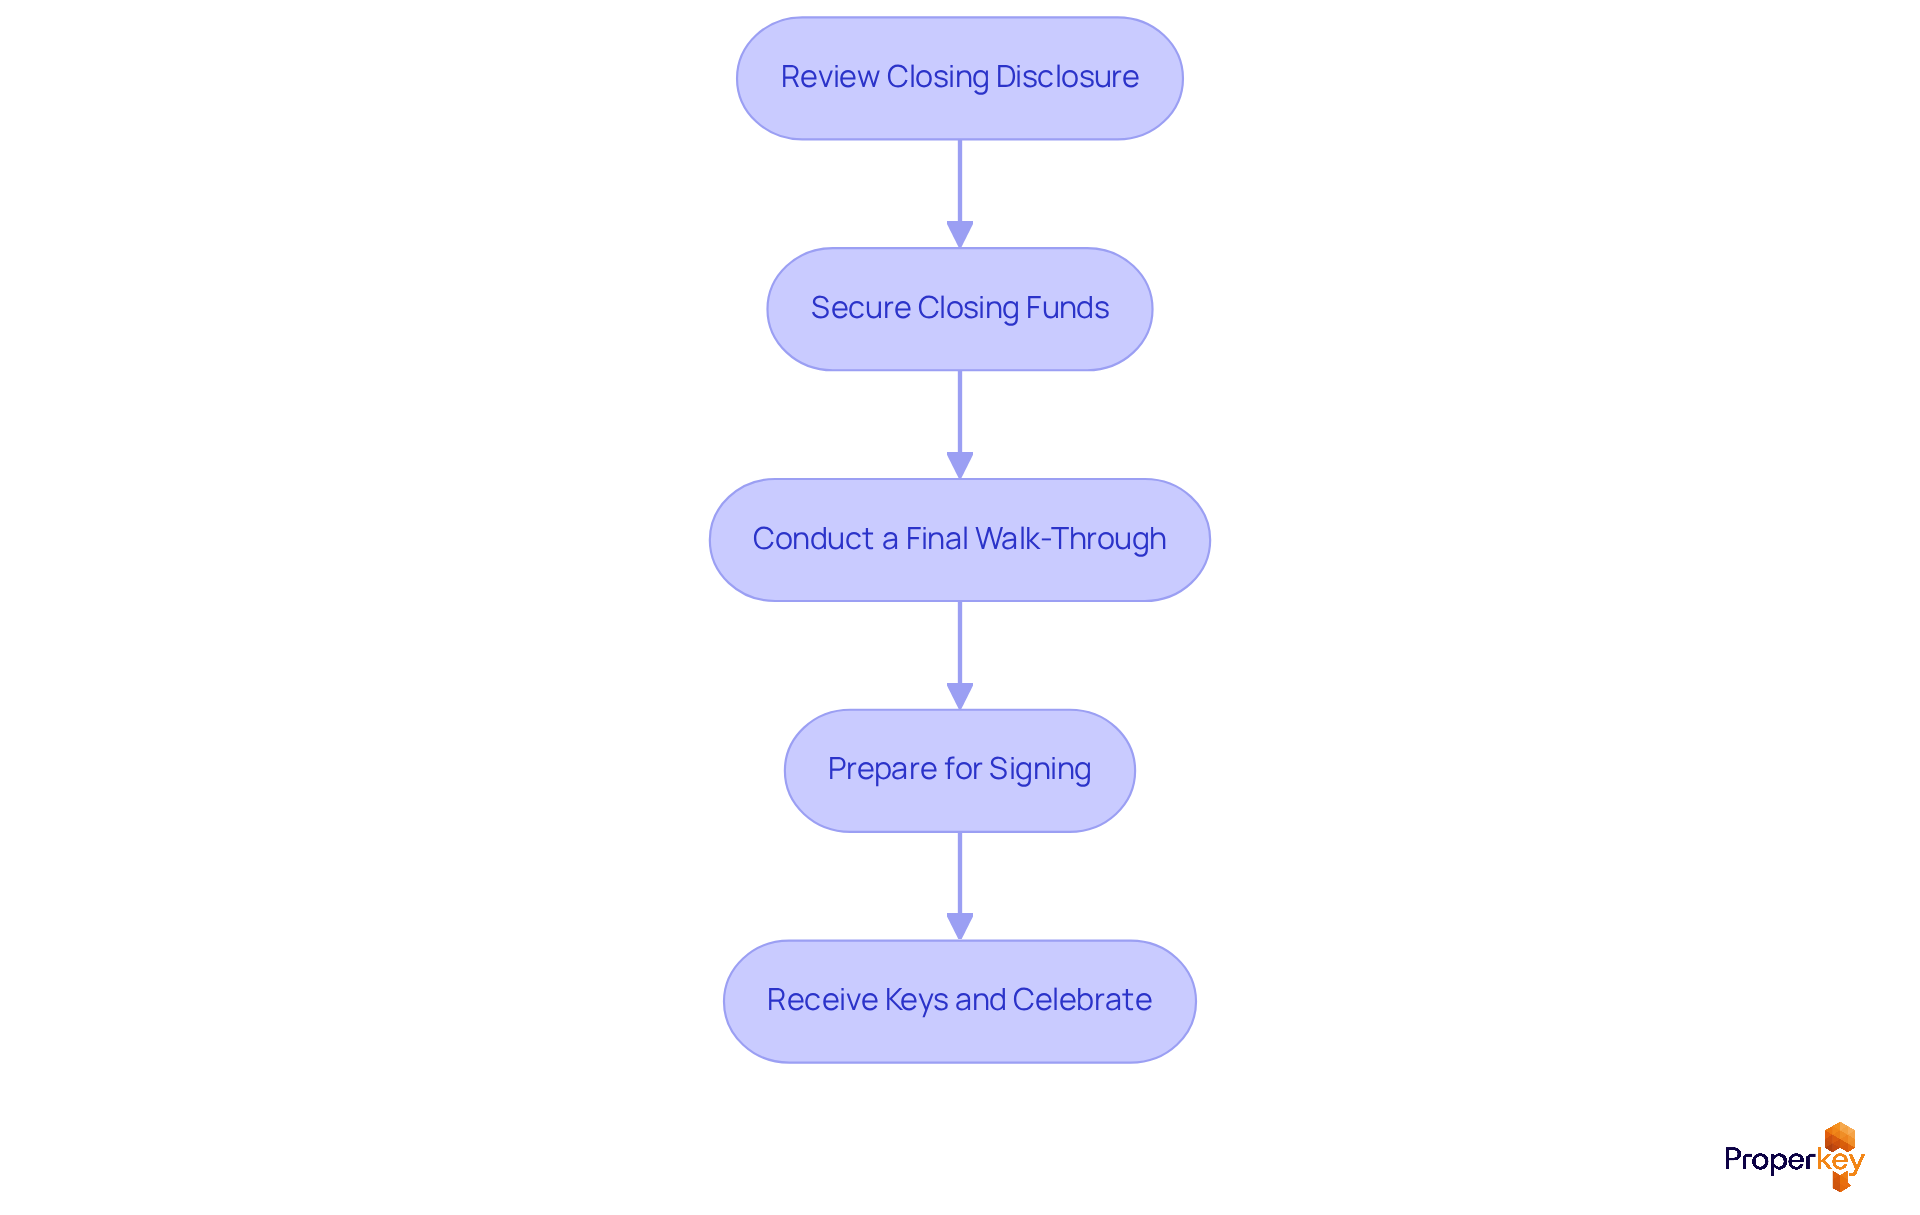
- Review Closing Disclosure: At least three business days prior to closing, you will receive a Closing Disclosure detailing the final terms of your financing, including the amount borrowed, interest rate, and closing costs. Make sure to review this document carefully to confirm that everything aligns with your expectations.
- Secure Closing Funds: Ensure you have the required funds ready for your down payment and closing costs to avoid any last-minute surprises. This may involve wiring money to the closing agent or bringing a certified check. Remember, closing agents typically accept only cashier’s checks or verified wire transfers.
- Conduct a Final Walk-Through: Prior to closing, take the time to perform a final walk-through of the property. This is your chance to verify that all promised repairs are done and that the home is in the condition you expect.
- Prepare for Signing: On closing day, bring your government-issued ID and any additional documents requested by your lender. Get ready to sign multiple documents, including the loan agreement, which solidifies your commitment to this important investment.
- Receive Keys and Celebrate: After all documents are signed and funds are transferred, you will receive the keys to your new home. This moment signifies the successful culmination of your journey into homeownership, a milestone that deserves celebration!
Conclusion
Navigating the mortgage landscape for a million-dollar home can feel daunting, but it doesn't have to be. Securing a mortgage for such a property demands strategic planning and decisive action. By understanding your financial readiness, exploring various mortgage options, and gathering the necessary documentation, potential homeowners can navigate this journey with confidence. This guide equips you with the knowledge to navigate the mortgage process confidently and make decisions that align with your financial aspirations.
Key insights include:
- The importance of assessing your credit score and debt-to-income ratio
- The various types of mortgage options available for high-value properties
- The significance of thorough documentation
- Understanding the mortgage application process, which can ultimately lead to a smoother experience
By comparing offers and negotiating terms, buyers can secure the best possible financing for their new home.
Many potential homeowners feel lost in the complexities of securing a mortgage for a high-value property. However, by mastering these steps, you can transform uncertainty into confidence and control over your financial future. As you embark on your journey to homeownership, staying proactive and informed is key to your success. Whether it's through utilizing tools like Properkey or consulting with mortgage professionals, taking decisive action today can turn your homeownership aspirations into reality, setting you on a path to financial success.
Frequently Asked Questions
What should I check to assess my financial readiness before selling my home?
You should check your credit score, calculate your debt-to-income ratio (DTI), assess your savings, evaluate your employment stability, and consider any additional monetary responsibilities.
How can I check my credit score?
Obtain your credit report from major credit bureaus such as Equifax, Experian, and TransUnion. A credit score of at least 700 is often favored by lenders for advantageous loan rates.
What is a good debt-to-income ratio (DTI)?
Lenders typically favor a debt-to-income ratio of 36% or lower. To calculate your DTI, divide your total monthly debt payments by your gross monthly income and multiply by 100.
How much should I save for a down payment on a high-value home?
For a mortgage on a 1 million dollar home, you should aim for a down payment of around 20%, which amounts to $200,000. Additionally, set aside funds for closing expenses, which can range from 2% to 5% of the borrowing amount.
What employment history do lenders prefer?
Lenders generally prefer applicants with at least two years of stable employment in the same field. If self-employed, be prepared to provide documentation like tax returns and profit-loss statements.
What are jumbo loans and why are they important?
Jumbo loans are mortgages for properties valued at $1 million or higher, exceeding conventional mortgage limits. They come with stricter credit standards and often require a minimum credit score of 700.
What are the differences between fixed-rate and adjustable-rate mortgages (ARMs)?
Fixed-rate mortgages offer stability with consistent monthly payments, while ARMs start with lower rates that can fluctuate. ARMs may be suitable for those planning to sell or refinance before the rate adjusts.
What is an interest-only mortgage?
An interest-only mortgage allows you to pay only the interest for a set period, which can be beneficial if you expect an increase in income or plan to sell before principal payments begin.
What should I consider when researching financing criteria for jumbo loans?
Financing criteria can vary by institution, with many requiring a down payment of at least 20%. Some programs may accept down payments as low as 10% for well-qualified borrowers.
How can a mortgage broker assist me in securing a jumbo loan?
A mortgage broker can simplify the process by providing access to various lenders and helping you navigate the complexities of high-value home financing to find a product that meets your needs.
What documentation should I prepare for the underwriting process?
Gather recent pay stubs, tax returns, and asset statements early to expedite the underwriting process, as lenders require a comprehensive assessment of your financial situation for jumbo loans.
List of Sources
- Assess Your Financial Readiness and Credit Score
- Average Mortgage Rates by Credit Score (https://experian.com/blogs/ask-experian/average-mortgage-rates-by-credit-score)
- What is the average credit score and how can you improve yours? (https://cnbc.com/select/the-average-credit-score)
- What Is the Average Credit Score in the US? (https://experian.com/blogs/ask-experian/what-is-the-average-credit-score-in-the-u-s)
- Average Credit Score Statistics 2026 (https://wallethub.com/edu/cs/average-credit-scores/25578)
- Current Mortgage Rates by Credit Score | [current_year] (https://themortgagereports.com/87625/mortgage-rates-by-credit-score)
- Explore Mortgage Options for High-Value Homes
- California Jumbo Loan Limits for 2026: What Makes a Loan Jumbo, How to Qualify, and How to Decide (https://amerisave.com/learn/california-jumbo-loan-limits-for-what-makes-a-loan-jumbo-how-to-qualify-and-how-to-decide)
- Jumbo loan limits and requirements in 2026 (https://rocketmortgage.com/learn/jumbo-loan-limits)
- What is a Jumbo Loan: The Complete 2026 Guide (https://53.com/content/fifth-third/en/financial-insights/personal/home-ownership/what-is-a-jumbo-loan.html)
- ARMs Offer Significant Savings Over Fixed-Rate Mortgages (https://nationalmortgageprofessional.com/news/arms-offer-significant-savings-over-fixed-rate-mortgages)
- Everything you need to know about Jumbo Loans in 2026 | Mortgage Equity Partners (https://mortgageequitypartners.com/everything-you-need-to-know-about-jumbo-loans-in-2026)
- Gather Required Documentation for Your Application
- A Complete Checklist of Documents Needed for a Mortgage (https://money.usnews.com/loans/mortgages/articles/a-complete-checklist-of-documents-needed-for-a-mortgage)
- Documents Needed For Mortgage Preapproval | Bankrate (https://bankrate.com/mortgages/documents-for-preapproval)
- Documents you need to apply for a mortgage | Fannie Mae (https://yourhome.fanniemae.com/buy/home-loan-documents)
- Proof of Income: What to Know When Applying for a Mortgage (https://pnc.com/insights/personal-finance/borrow/what-is-proof-of-income.html)
- The Complete Mortgage Preapproval Checklist for 2026 (https://sistarmortgage.com/blog/mortgage-preapproval-checklist)
- Submit Your Mortgage Application and Understand the Process
- How the Mortgage Process Works in California (2026) - JVM Lending (https://jvmlending.com/blog/how-does-the-mortgage-process-work-for-homebuyers-in-california)
- US Mortgage Statistics 2026: Debt, Delinquency and Foreclosure Data (https://lendingtree.com/home/mortgage/u-s-mortgage-market-statistics)
- How Does the Mortgage Application Process Work | CS Bank (https://cs.bank/articles/how-does-the-mortgage-application-process-work)
- How Long Is a Mortgage Pre-Approval Good For? (https://rate.com/mortgage/resource/how-long-is-a-pre-approval-good-for)
- How Long Does Mortgage Pre-Approval Take? | CrossCountry Mortgage (https://crosscountrymortgage.com/mortgage/resources/how-long-does-mortgage-pre-approval-take)
- Compare Mortgage Offers and Understand Terms
- Where are mortgage rates heading in August — and beyond? Here’s what the pros predict (https://marketwatch.com/picks/whats-next-for-mortgage-rates-heres-where-7-pros-say-theyre-heading-in-august-and-beyond-53cb1c70)
- Current California Mortgage and Refinance Rates | Bankrate (https://bankrate.com/mortgages/mortgage-rates/california)
- Mortgage rates Wednesday, Aug. 26, 2026 | Fortune (https://fortune.com/article/current-mortgage-rates-08-26-2026)
- Loan estimate explainer | Consumer Financial Protection Bureau (https://consumerfinance.gov/owning-a-home/loan-estimate)
- How to Read a Mortgage Loan Estimate - NerdWallet (https://nerdwallet.com/mortgages/learn/loan-estimate)
- Finalize Your Mortgage and Prepare for Closing
- Closing Day Tips (https://amfam.com/resources/first-time-home-buyers-guide/what-to-expect-on-closing-day)
- What Happens on Closing Day in California? A Seller's Walkthrough (2026) (https://snapdwell.com/blog/what-happens-on-closing-day-california)
- What Happens on Closing Day & How Long it Takes (https://veteransunited.com/education/closing-day)
- What To Expect at Closing on a House | Fannie Mae (https://yourhome.fanniemae.com/buy/what-expect-closing-house)
- What Can I Expect To Happen On Closing Day? (https://crescenttitle.com/blog/what-to-expect-on-closing-day)