Should You Lock in Your Mortgage Rate? 4 Steps to Decide

Introduction
Homeowners often grapple with uncertainty, unsure of when to lock in their mortgage rates amidst fluctuating market conditions. Let’s explore the essential steps homeowners need to take when deciding to lock in their mortgage rates, highlighting both the advantages and potential drawbacks of this crucial financial decision.
- Delaying this decision could result in higher payments and lost opportunities.
- Act now to secure the best possible rate and protect your financial future.
Understand Mortgage Rate Locks
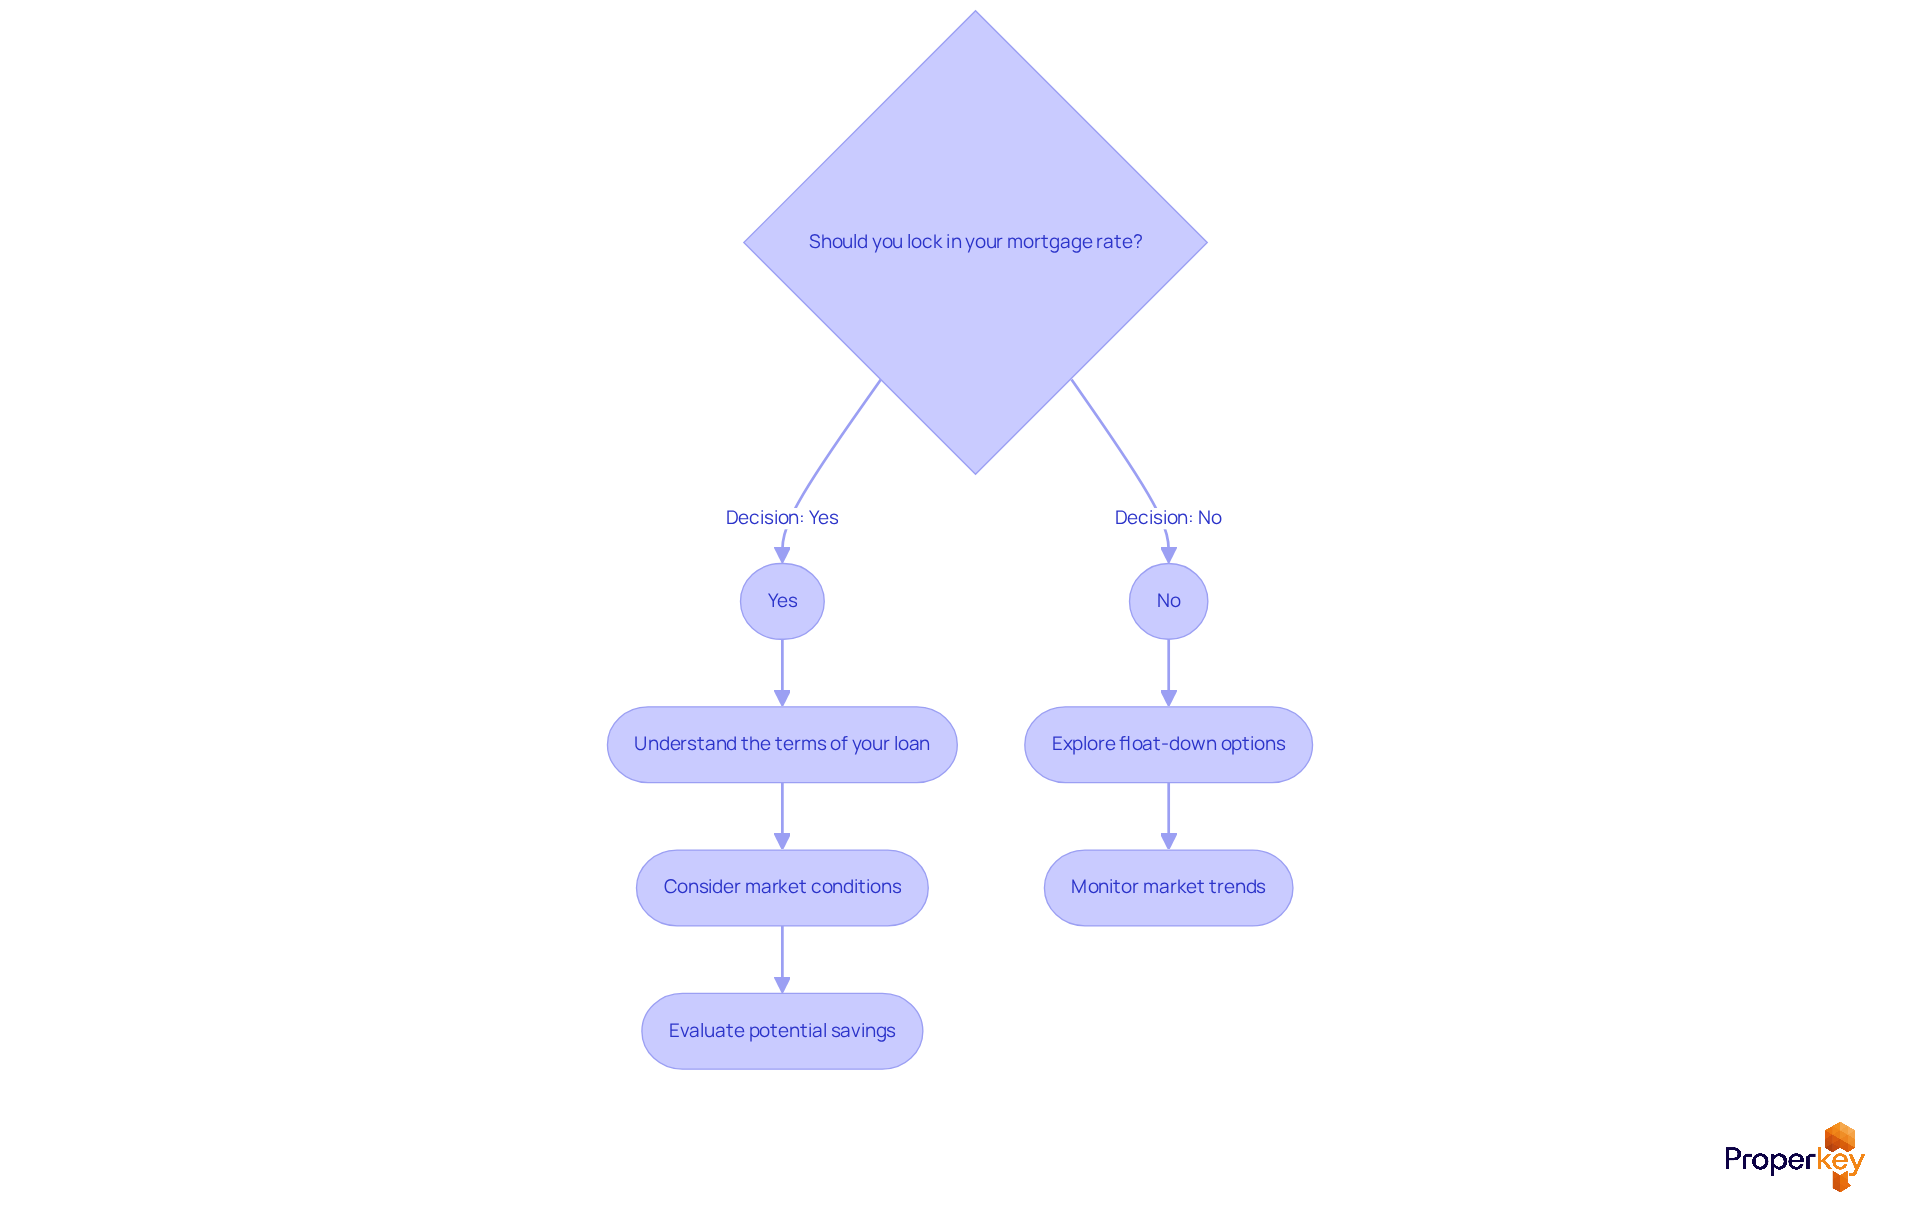
In a fluctuating market, you may wonder, should you lock in your mortgage rate to secure a loan interest lock as your best defense against rising costs? A loan interest lock is an essential agreement between you and your lender that guarantees a specific interest percentage for a set duration, usually between 30 to 60 days. This means that if market prices rise during this period, your rate stays the same, protecting you from increases that could impact your monthly payments and overall loan costs. In today's environment, where nearly 21.2% of homeowners face mortgage costs of 6% or higher, the question arises: should you lock in your mortgage rate to take advantage of lower interest rates?
Some lenders also offer a float-down option, allowing you to benefit from lower rates if they drop after you've secured your price. Understanding your agreement's terms is vital; it can shape your financial planning and home buying journey. Given the volatility of loan interest rates, obtaining a favorable rate can lead to significant savings, particularly in states like California, Idaho, and Nevada, where housing market conditions are constantly shifting.
As we approach 2026, homeowners with rates above 7% may find figures close to 6% attractive, leading to the question of whether you should lock in your mortgage rate. With inflation showing signs of relief, the potential for reduced loan costs could encourage more buyers to enter the market. Don't leave your financial future to chance; explore your options today and secure the best deal for your home financing needs.
Determine the Right Time to Lock Your Rate
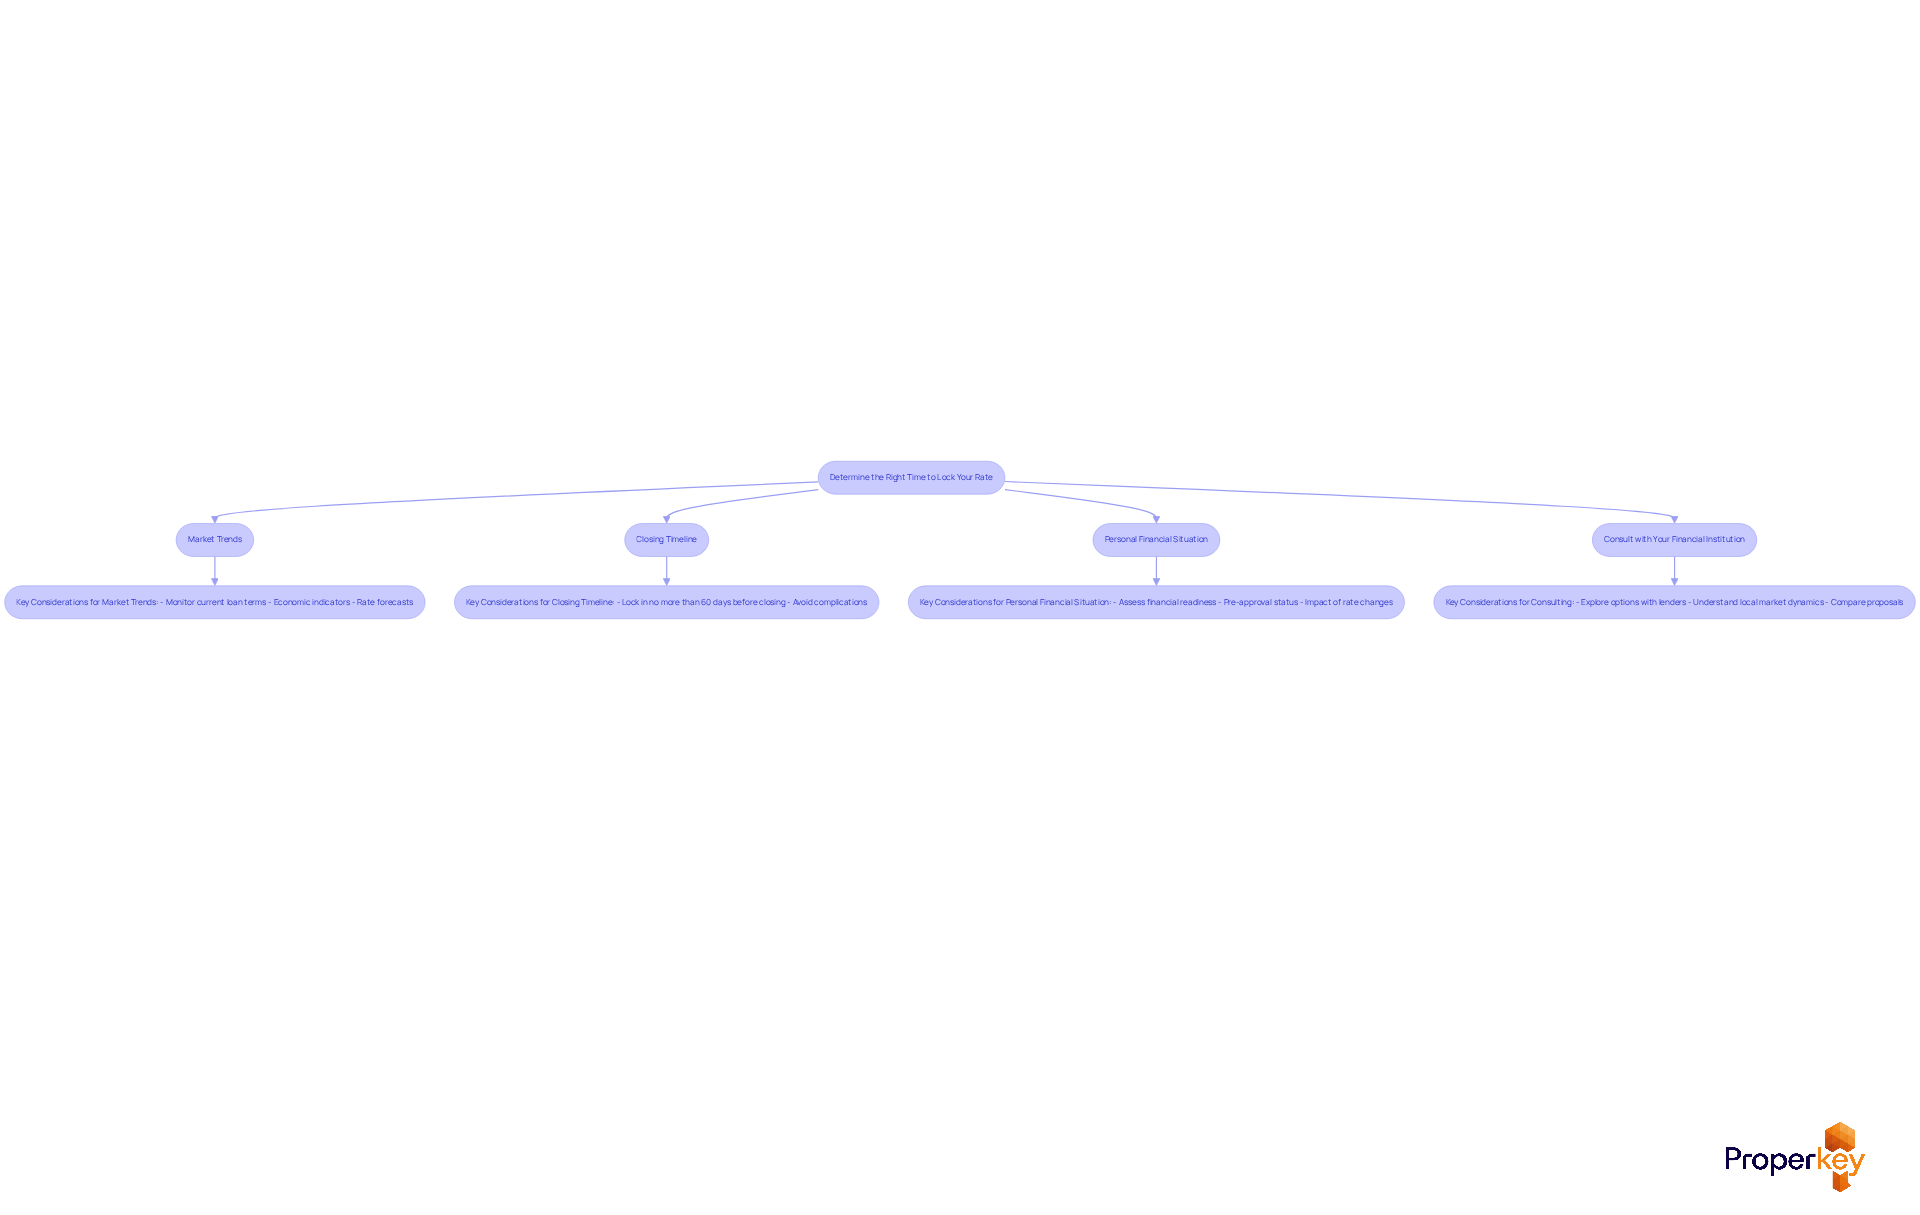
Timing is crucial when it comes to securing your loan interest, especially in a fluctuating market where every percentage point counts. Here are essential factors to consider:
- Market Trends: Keep an eye on current loan terms and economic indicators. With the average 30-year fixed mortgage percentage at 6.77% as of August 2026, and forecasts suggesting a slight decline to around 6.4% in Q3 2026, you might wonder when you should you lock in your mortgage rate, as locking in a deal sooner could be beneficial if rates are on the rise. Conversely, if prices are dropping, you might want to consider waiting.
- Closing Timeline: Secure your rate when you have a clear closing timeline. Most lenders recommend locking in your interest no more than 60 days before your closing date to avoid complications, ensuring you secure favorable terms without risking fluctuations.
- Personal Financial Situation: Take a moment to assess your financial readiness. If you’re pre-approved and have found a property, you may wonder should you lock in your mortgage rate to secure favorable conditions, especially in a market where prices can shift daily. Remember, even a small difference in rates can lead to significant savings over the life of your mortgage.
- Consult with Your Financial Institution: Consult with your financial institution to explore your options and gain insights into current market conditions. They can help you determine the best time to lock based on your specific financial situation and local market dynamics in California, Idaho, and Nevada. Additionally, evaluating proposals from various financial institutions can enhance your savings and ensure you secure the most favorable terms.
Acting swiftly can mean the difference between securing a favorable rate and facing higher costs down the line.
Evaluate Costs and Trade-offs of Rate Locks
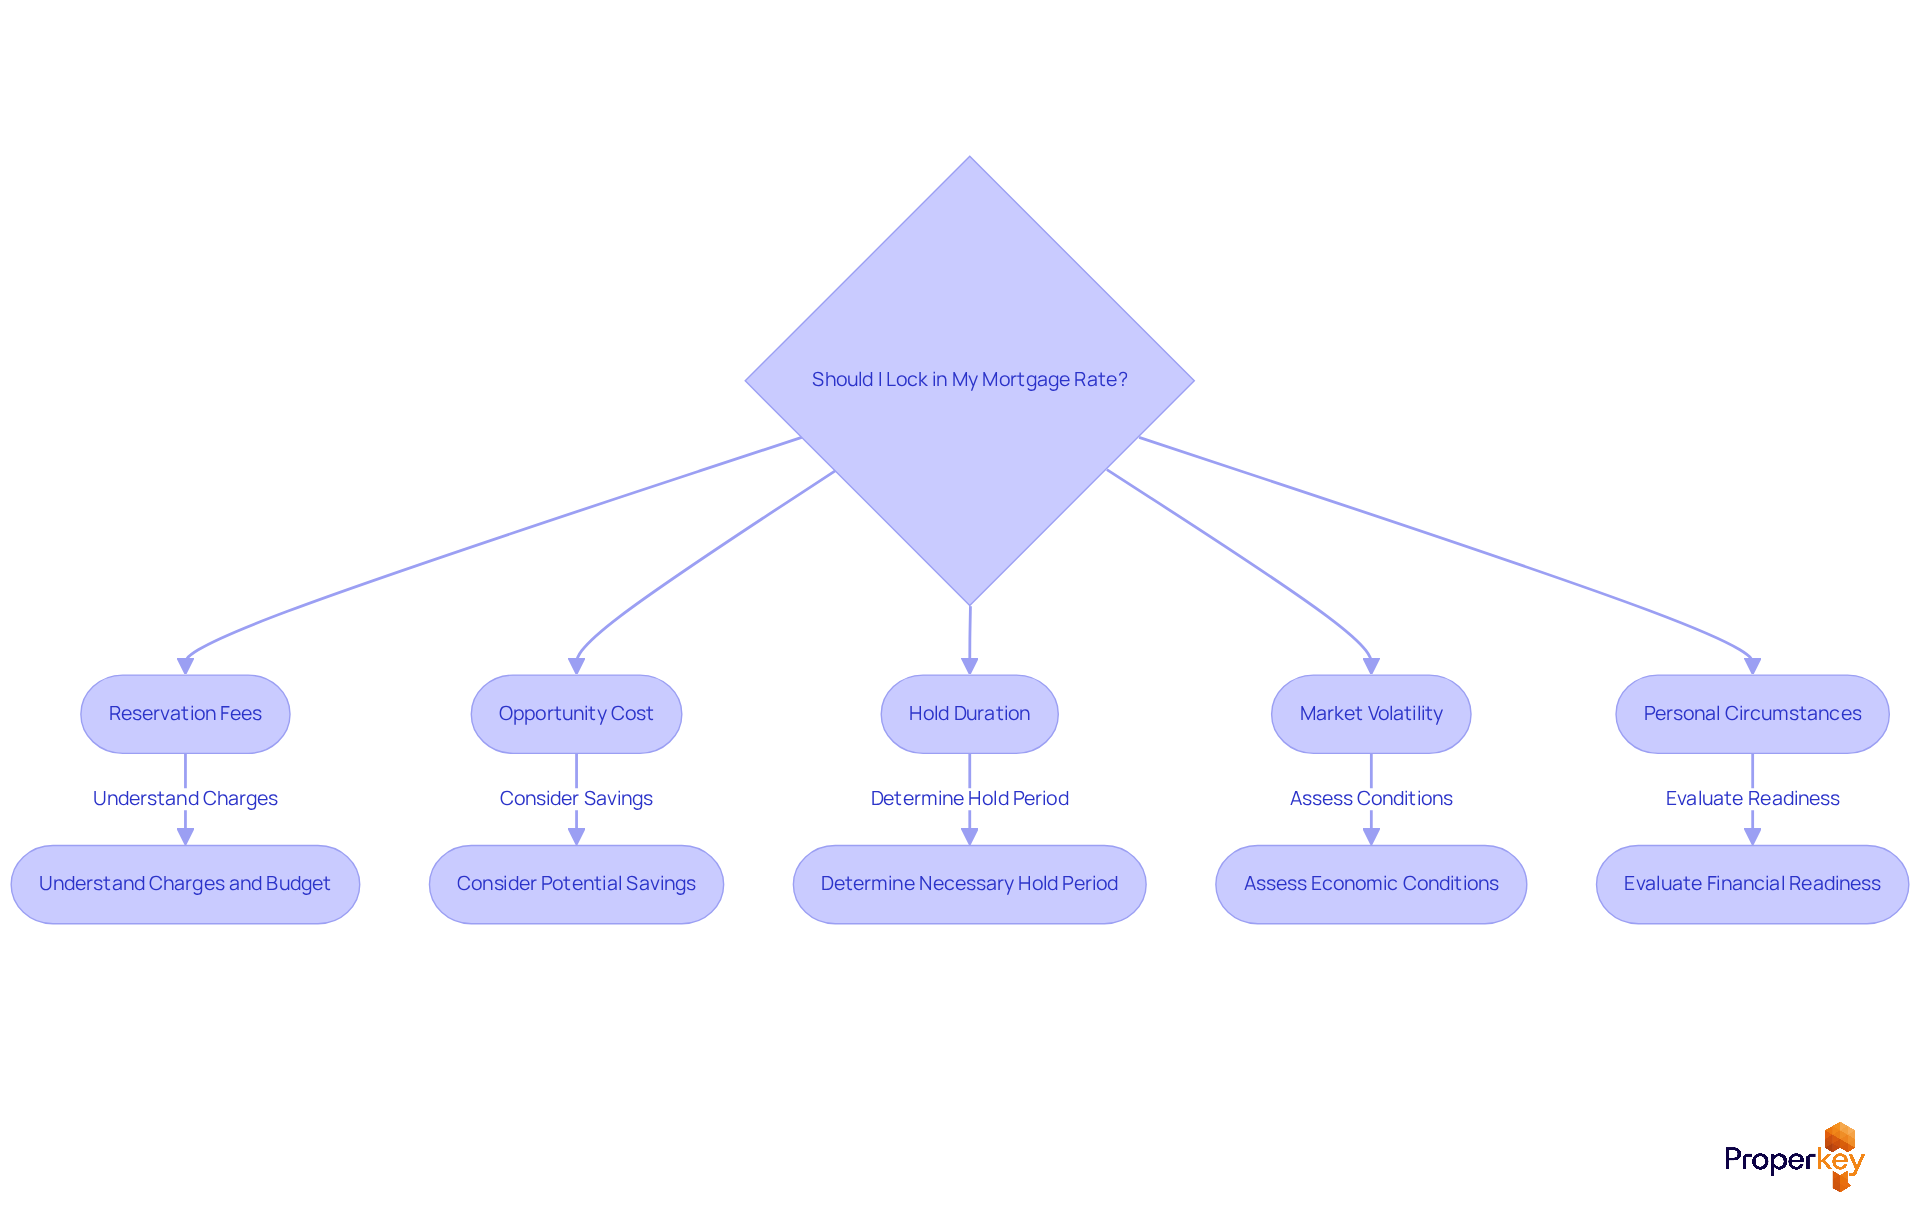
Before locking in your mortgage rate, consider the potential costs and trade-offs that could impact your financial future:
- Reservation Fees: Many financial institutions offer standard price locks for shorter durations without initial costs. It's crucial to understand these charges and factor them into your budget.
- Opportunity Cost: Committing to a mortgage rate might mean losing out on potential savings if market rates drop. While some lenders provide a float-down option to take advantage of lower rates, this feature often comes with additional costs.
- Hold Duration: Typical hold periods range from 30 to 60 days, with some lenders allowing holds beyond 60 days for new construction, which may incur a higher cost. Think about how long you need the lock to fit your closing timeline, so you don’t end up paying more than necessary.
- Market Volatility: Mortgage costs fluctuate based on economic conditions. Securing a rate safeguards against rising costs, offering predictability for budgeting. While locking in a rate provides stability, you should consider should you lock in your mortgage rate, as it also carries the risk of locking in a higher rate if the market shifts downward.
- Personal Circumstances: Your financial readiness and timeline for proceeding with the purchase should significantly influence your decision. If you're unsure about your financial situation or the timing of your acquisition, it may be wise to hold off on securing a rate, especially since borrowers are encouraged to act quickly to secure rates below 6%, as they may not consistently align with the Federal Reserve.
Follow Steps to Lock Your Mortgage Rate Successfully
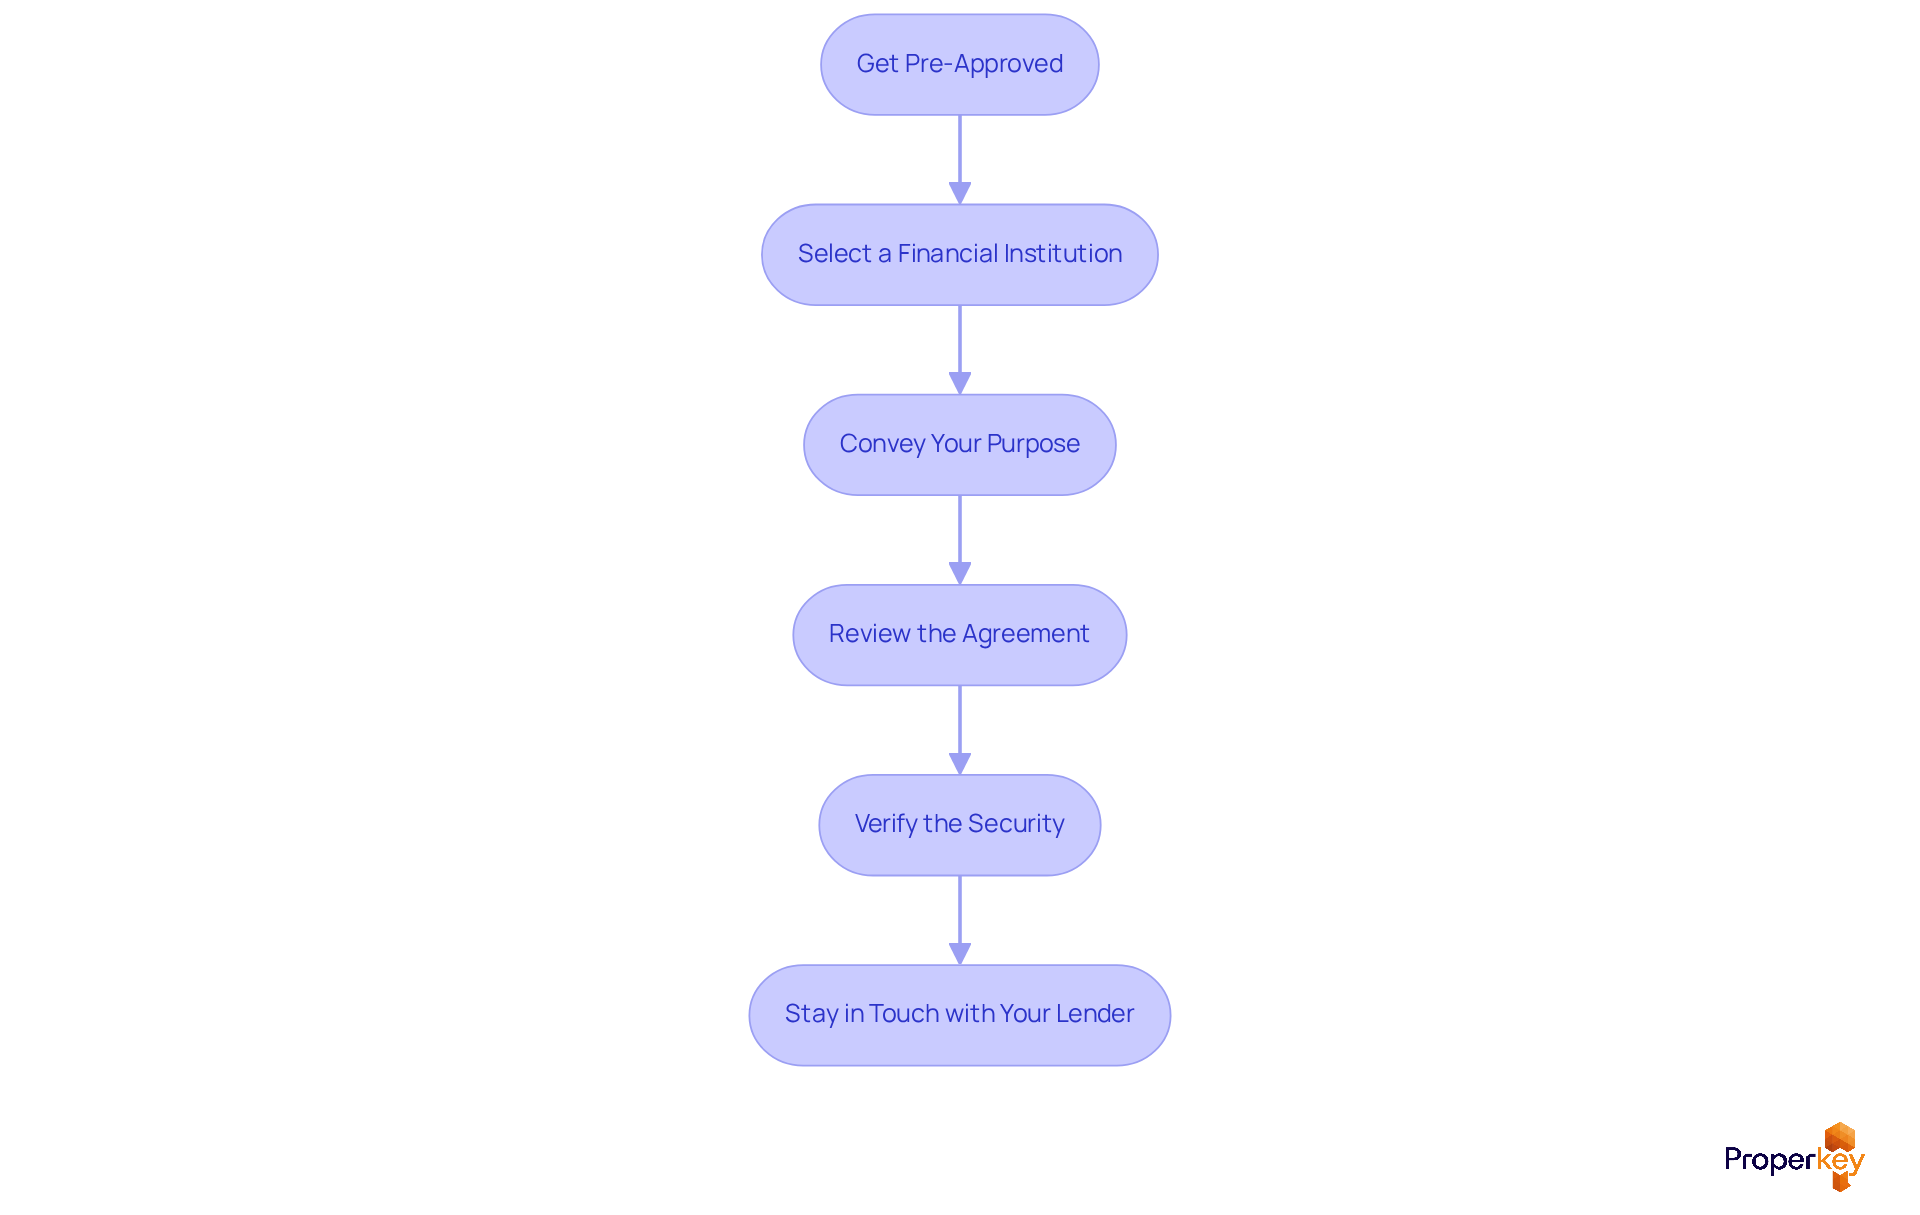
Navigating the complexities of locking in your mortgage rate can be daunting, but these essential steps will guide you through the process:
- Get Pre-Approved: Start by obtaining a mortgage pre-approval. This process clarifies your budget and the available prices. It makes navigating your options much easier. Vana provides an efficient method where you can evaluate offers from various financial institutions through a single application, guaranteeing you receive the best deal. In California, Idaho, and Nevada, getting pre-approved early can help you stand out in a competitive market.
- Select a Financial Institution: Investigate different providers to discover one that presents attractive pricing and beneficial conditions. Engage in discussions about their interest protection policies to ensure you understand your options. Remember, most financial institutions offer initial interest guarantees at no cost, but some may impose charges for extensions.
- Convey Your Purpose: When you're ready to secure your price, reach out to your financial institution to express your intention. Specify the duration you need for the security, which typically ranges from 30 to 120 days, and any specific terms you wish to include.
- Review the Agreement: Take a close look at the pricing hold agreement your lender provides. Pay attention to the terms, including the duration, any applicable fees, and conditions that may influence your agreement. For instance, prolonging a price guarantee can lead to costs, typically about 0.125% of the loan amount for each 5-10 days.
- Verify the Security: After reviewing the agreement, confirm the security with your financial institution. Keep a copy of the agreement for your records and monitor market conditions as your closing date approaches. Recent trends suggest that numerous purchasers are employing interest safeguards to reduce risks linked to increasing borrowing costs, with an 11% rise in safeguard activity compared to the prior year.
- Stay in Touch with Your Lender: Maintain open communication with your lender throughout the process. If your financial situation or market conditions change, discuss your options to ensure you are making informed decisions. As Marc Halpern, CEO of Foundation Mortgage, states, 'A price lock is one of the strongest forms of protection a borrower has in a volatile interest environment, particularly should you lock in your mortgage rate.'
Mastering these steps not only secures your mortgage rate but also positions you for financial success in an unpredictable market.
Conclusion
In a market where interest rates can change overnight, deciding whether to lock in a mortgage rate is more than just a choice - it's a necessity. By locking in a specific interest rate for a set period, borrowers can shield themselves from potential increases that could significantly affect their monthly payments and overall loan costs. Grasping the nuances of mortgage rate locks - like timing and costs - is crucial for making informed decisions that align with your financial goals.
Throughout this guide, we've highlighted key factors to aid in your decision-making process. These include:
- Monitoring market trends
- Assessing your financial readiness
- Consulting with financial institutions to explore the best options available
Additionally, understanding the costs and trade-offs associated with rate locks is vital, as these elements can influence your long-term financial outcomes. Following a structured approach to locking in a mortgage rate can lead to substantial savings and peace of mind in an unpredictable market.
Ultimately, the decision to lock in a mortgage rate should be made with careful consideration of both current market conditions and personal circumstances. By taking proactive steps and staying informed, you can navigate the complexities of mortgage financing effectively. By making informed decisions today, you can safeguard your financial future against the unpredictability of tomorrow's market.
Frequently Asked Questions
What is a mortgage rate lock?
A mortgage rate lock is an agreement between you and your lender that guarantees a specific interest percentage for a set duration, typically between 30 to 60 days.
Why should I consider locking in my mortgage rate?
Locking in your mortgage rate protects you from rising interest rates during the lock period, ensuring your rate remains the same even if market prices increase, which can help manage your monthly payments and overall loan costs.
What is a float-down option in mortgage rate locks?
A float-down option allows you to benefit from lower interest rates if they drop after you have secured your initial rate lock.
How can mortgage rate locks impact financial planning?
Understanding the terms of your mortgage rate lock can significantly shape your financial planning and home buying journey, potentially leading to substantial savings.
What should homeowners with rates above 7% consider?
Homeowners with rates above 7% may find rates close to 6% attractive, prompting them to consider locking in their mortgage rate as market conditions evolve.
How does the current market environment affect mortgage rates?
With nearly 21.2% of homeowners facing mortgage costs of 6% or higher, the fluctuating market conditions make it crucial to evaluate whether to lock in a mortgage rate to take advantage of potentially lower rates.
What factors should I consider before locking in my mortgage rate?
You should consider the volatility of loan interest rates, the terms of your agreement, and the current market conditions to make an informed decision about locking in your mortgage rate.
List of Sources
- Understand Mortgage Rate Locks
- Mortgage Rate Lock-In Persists, With Ultralow Rate Holders Showing Little Sign of Budging (https://realtor.com/news/trends/homeowners-monthly-mortgage-payments-july-2026-report)
- The Mortgage Lock-In Effect Is Fading: Will More Affordable Homes Will Go Up for Sale? | New American Funding (https://newamericanfunding.com/learning-center/housing-news/the-mortgage-lock-in-effect-is-fading-will-more-affordable-homes-will-go-up-for-sale)
- Compare Today's Mortgage Interest Rates - NerdWallet (https://nerdwallet.com/mortgages/mortgage-rates)
- What to consider about mortgage rate locks now, according to experts (https://cbsnews.com/news/what-to-consider-about-mortgage-rate-locks-now-according-to-experts)
- Mortgage Rates (https://freddiemac.com/pmms)
- Determine the Right Time to Lock Your Rate
- When is the Best Time to Lock Your Mortgage Rate? (https://americanfinancing.net/market-watch/mortgage-rate-lock)
- Compare Today's Mortgage Interest Rates - NerdWallet (https://nerdwallet.com/mortgages/mortgage-rates)
- Mortgage Rates Forecast For 2026: Experts Predict Whether Interest Rates Will Drop (https://forbes.com/advisor/mortgages/mortgage-interest-rates-forecast)
- Should you lock in a mortgage interest rate before the June Fed meeting? (https://cbsnews.com/news/lock-in-mortgage-interest-rate-before-june-2026-fed-meeting)
- How Often Do Mortgage Rates Change? Best Days to Lock (https://themortgagereports.com/18161/best-day-to-lock-mortgage-rate-data)
- Evaluate Costs and Trade-offs of Rate Locks
- 3 benefits of a mortgage interest rate lock to know now (https://cbsnews.com/news/benefits-mortgage-interest-rate-lock-march-2026)
- Mortgage Rate Locks 101: 30/45/60-Day Options, Float-Downs, and Fees (https://thefederalsavingsbank.com/Blog/mortgage-rate-locks-101-30-45-60-day-options-float-downs-and-fees)
- What is a Mortgage Rate Lock and When Should You Use One - Heritage Bank NA (https://heritagebankna.com/what-is-a-mortgage-rate-lock-and-when-should-you-use-one)
- Should you lock a mortgage rate before the July Fed meeting? Pros and cons to consider now (https://cbsnews.com/news/should-you-lock-mortgage-rate-before-july-fed-meeting-pros-cons)
- Mortgage Rate Lock: What It Is And When To Lock | Bankrate (https://bankrate.com/mortgages/what-is-mortgage-rate-lock)
- Follow Steps to Lock Your Mortgage Rate Successfully
- Mortgage Rate Lock: What It Is And When To Lock | Bankrate (https://bankrate.com/mortgages/what-is-mortgage-rate-lock)
- Should I Lock My Mortgage Rate Today? | Pennymac (https://pennymac.com/blog/should-i-rate-lock-my-mortgage)
- When mortgage rates move, what matters more than chasing 5.99% (https://usbank.com/about-us-bank/news-and-stories/article-library/when-mortgage-rates-move-what-matters-more-than-chasing.html)
- What to consider about mortgage rate locks now, according to experts (https://cbsnews.com/news/what-to-consider-about-mortgage-rate-locks-now-according-to-experts)