Understanding High Mortgage Interest Rates: Key Insights for Buyers and Sellers
Introduction
High mortgage interest rates are not just reshaping the real estate landscape; they are creating significant hurdles for home sellers and buyers alike. As these rates climb, they inflate monthly payments and diminish purchasing power, forcing potential homeowners to rethink their budgets and expectations.
Navigating this complex environment requires strategic thinking and informed decision-making that aligns with your financial goals. Understanding the intricacies of mortgage interest rates and their broader implications is essential for anyone looking to thrive in today’s housing market.
Define Mortgage Interest Rates and Their Importance
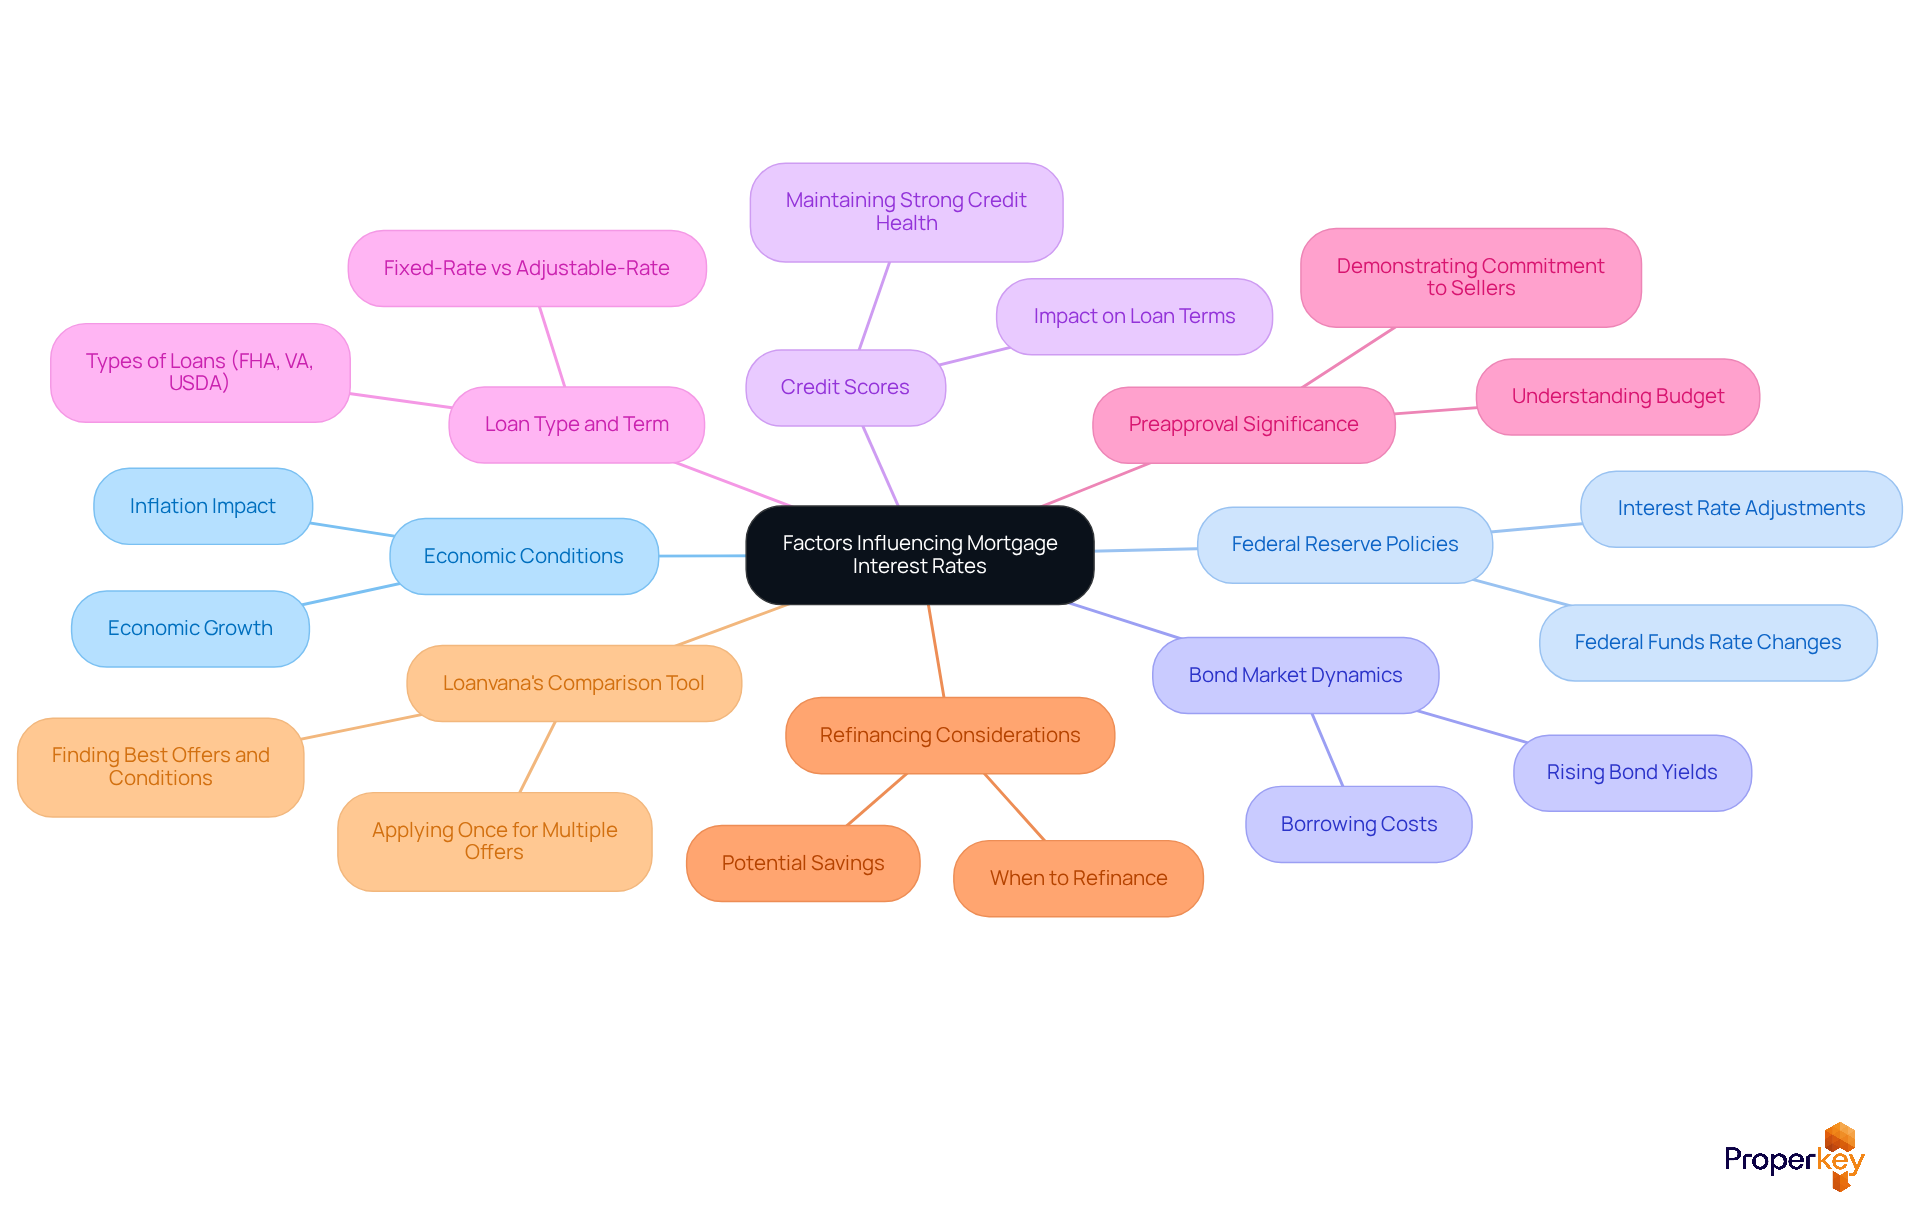
High mortgage interest rates can significantly hinder both home buyers and sellers, influencing the landscape of real estate transactions. These costs reflect the expense of borrowing, expressed as a percentage of the loan amount, and they play a pivotal role in determining monthly loan payments and the overall cost of a loan over its lifetime. Elevated interest levels can lead to higher monthly payments, which greatly impacts affordability for prospective purchasers. As of August 2026, the average 30-year fixed loan interest reached approximately 6.49%. Such elevated rates, specifically high mortgage interest rates, can discourage buyers due to the increased monthly expenses associated with these figures.
Understanding current loan terms is crucial for both buyers and sellers. For sellers, understanding these figures helps in pricing homes competitively in a market where high mortgage interest rates can dampen buyer demand. In fact, many homeowners hesitate to sell because they hold loans with lower interest rates, which can keep housing inventory limited even when demand decreases. This dynamic often results in reduced listing prices, as sellers may need to adjust their expectations to attract buyers who are affected by high mortgage interest rates.
It’s crucial for buyers to grasp how mortgage costs can shape their purchasing power. With many buyers contributing between 3% to 20% of the purchase price, even a slight increase in interest can have a significant impact. For instance, a 0.25% rise in interest on a $360,000 loan can lead to nearly $22,000 in additional interest over 30 years. Therefore, buyers should focus on securing favorable terms and consider the total monthly payments, which include property taxes and insurance, rather than just the home price.
To assist in this process, Loanvana's financing tool allows buyers to apply once and compare hundreds of loan options side-by-side from various lenders. This efficient method simplifies the financing process and enables buyers to view real-time interest figures, making it easier to navigate the complexities of home financing and discover the best options available.
Case studies illustrate the significance of these figures in the current market. As loan costs increased, many buyers adjusted their expectations and budgets, leading to a more cautious approach to home acquisitions. This shift in buyer behavior underscores the necessity for both parties to stay informed about financing trends and their effects on the housing market. Understanding these trends is not just beneficial; it’s essential for navigating the complexities of today’s housing market effectively.
Explore Factors Influencing Mortgage Interest Rates
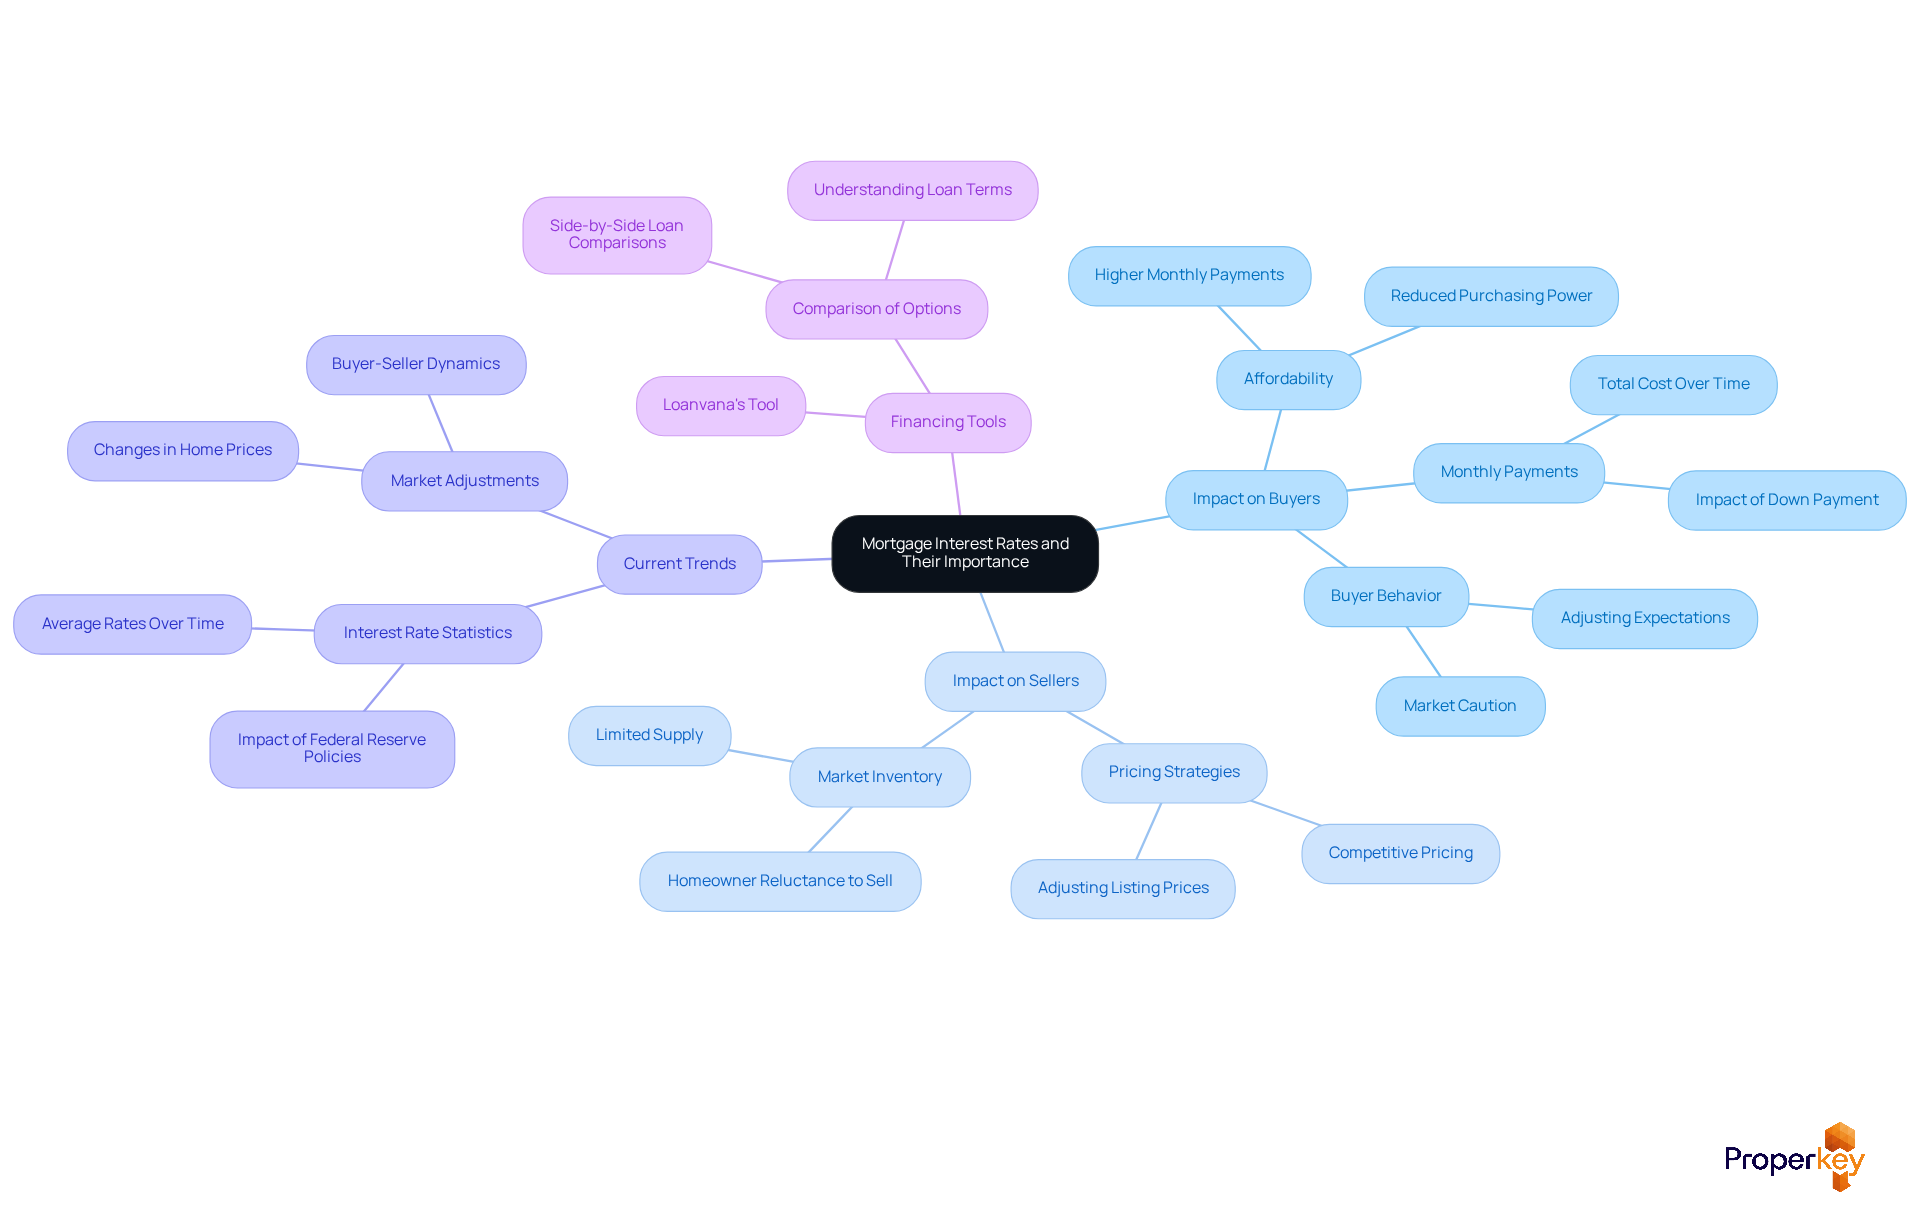
Navigating California's real estate market can be daunting, especially when it comes to understanding high mortgage interest rates. Several key factors influence high mortgage interest rates, and understanding them can make a significant difference for homebuyers.
- Economic Conditions: Inflation and economic growth are pivotal in shaping mortgage rates. As inflation continues, lenders often raise charges to protect their profitability, which can directly impact homebuyers' affordability. As of August 6, 2026, the average interest percentage for a 30-year fixed loan is 6.69%, reflecting these ongoing economic pressures.
- Federal Reserve Policies: The Federal Reserve's monetary policy plays a crucial role in determining home loan costs. When the Fed raises interest levels to address inflation, it often leads to high mortgage interest rates, which increase borrowing expenses for prospective homeowners. Notably, the Fed implemented its third successive reduction to the federal funds level in December 2025, which has consequences for current home loan costs.
- Bond Market Dynamics: When bond yields rise, borrowing costs usually go up, making loans more expensive in the broader market. This connection is vital for understanding how external financial factors can influence high mortgage interest rates.
- Credit Scores: Your credit score plays a big role in the mortgage terms you can secure. Better credit scores typically lead to reduced costs, making it crucial for purchasers to uphold strong credit health when looking for a mortgage.
- Loan Type and Term: The type of loan-whether fixed-rate or adjustable-rate-and its term can also affect the interest rate offered. Comprehending options such as jumbo loans, FHA, VA, and USDA loans is essential for purchasers, particularly those considering high-value financing alternatives for luxury residences or renovation projects. Fixed-rate loans offer stability in payments, whereas adjustable-rate loans may begin at a lower rate but can vary over time.
- Preapproval Significance: Obtaining preapproval for a loan assists purchasers in comprehending their budget and demonstrates to sellers that they are committed, which is essential in a competitive market.
- Refinancing Considerations: If interest levels decrease or a borrower's credit rating enhances, refinancing may be a feasible choice for purchasers and sellers maneuvering through the loan landscape.
- Loanvana's Comparison Tool: Using Loanvana's financing tool enables purchasers to apply once and compare hundreds of loan options side-by-side from various lenders, ensuring they discover the best offers and conditions available, especially for high-value properties.
Understanding these factors is crucial for buyers and sellers navigating California's ever-changing financing landscape, particularly due to high mortgage interest rates. Mastering these factors not only empowers buyers but also positions them for success in a competitive market.
Implement Strategies to Manage High Mortgage Interest Rates
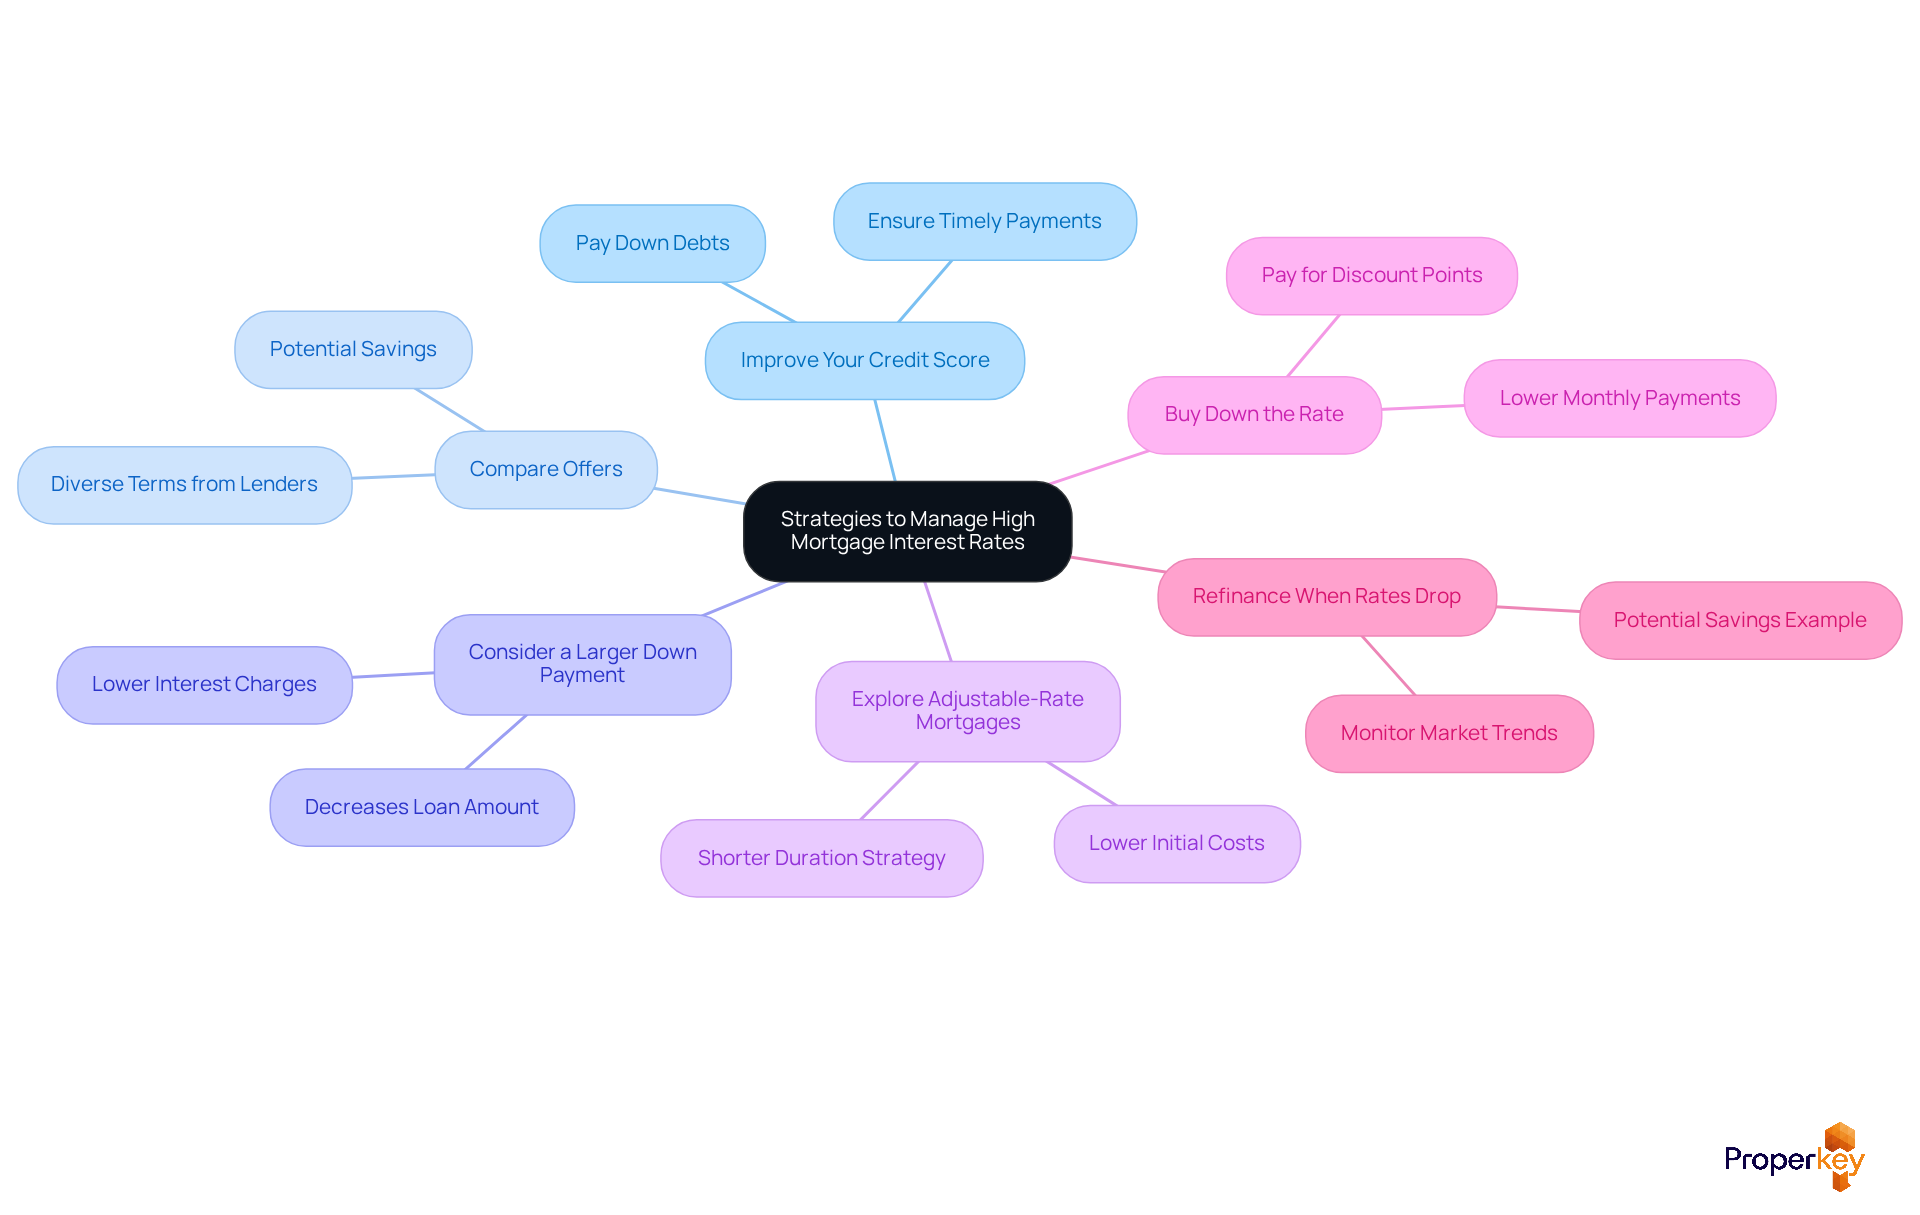
High mortgage interest rates are making it increasingly challenging for home sellers to navigate the market effectively. To manage these challenges, consider the following strategies:
- Improve Your Credit Score: A higher credit score can qualify you for lower interest rates. Focus on paying down debts and ensuring timely payments to boost your score, as this can significantly impact your mortgage options.
- Compare Offers: Different lenders provide diverse terms. Comparing offers from multiple lenders can help you find the best deal, potentially saving you thousands over the life of your loan.
- Consider a Larger Down Payment: A larger down payment decreases the loan amount and can result in a lower interest charge. This is particularly important in markets like California, where home prices are high and a substantial down payment can make a significant difference.
- Explore Adjustable-Rate Mortgages (ARMs): If you intend to remain in your residence for a shorter duration, an ARM may provide lower initial costs compared to fixed-rate mortgages. This can be a strategic choice for buyers in fluctuating markets.
- Buy Down the Rate: Consider paying for discount points to reduce your interest cost. This can be beneficial if you plan to stay in your home long-term, as it can lead to lower monthly payments.
- Refinance When Rates Drop: Keep an eye on market trends. If prices drop, refinancing your home loan can result in considerable savings. For example, a decrease in percentages from 7.25% to 6.5% could save you $200 each month on a $400,000 loan.
By implementing these strategies, you can not only manage your mortgage costs but also position yourself for success in a challenging market.
Assess the Impact of High Mortgage Rates on Affordability
In California's current market, high mortgage interest rates are reshaping the landscape for both home buyers and sellers. Here’s how:
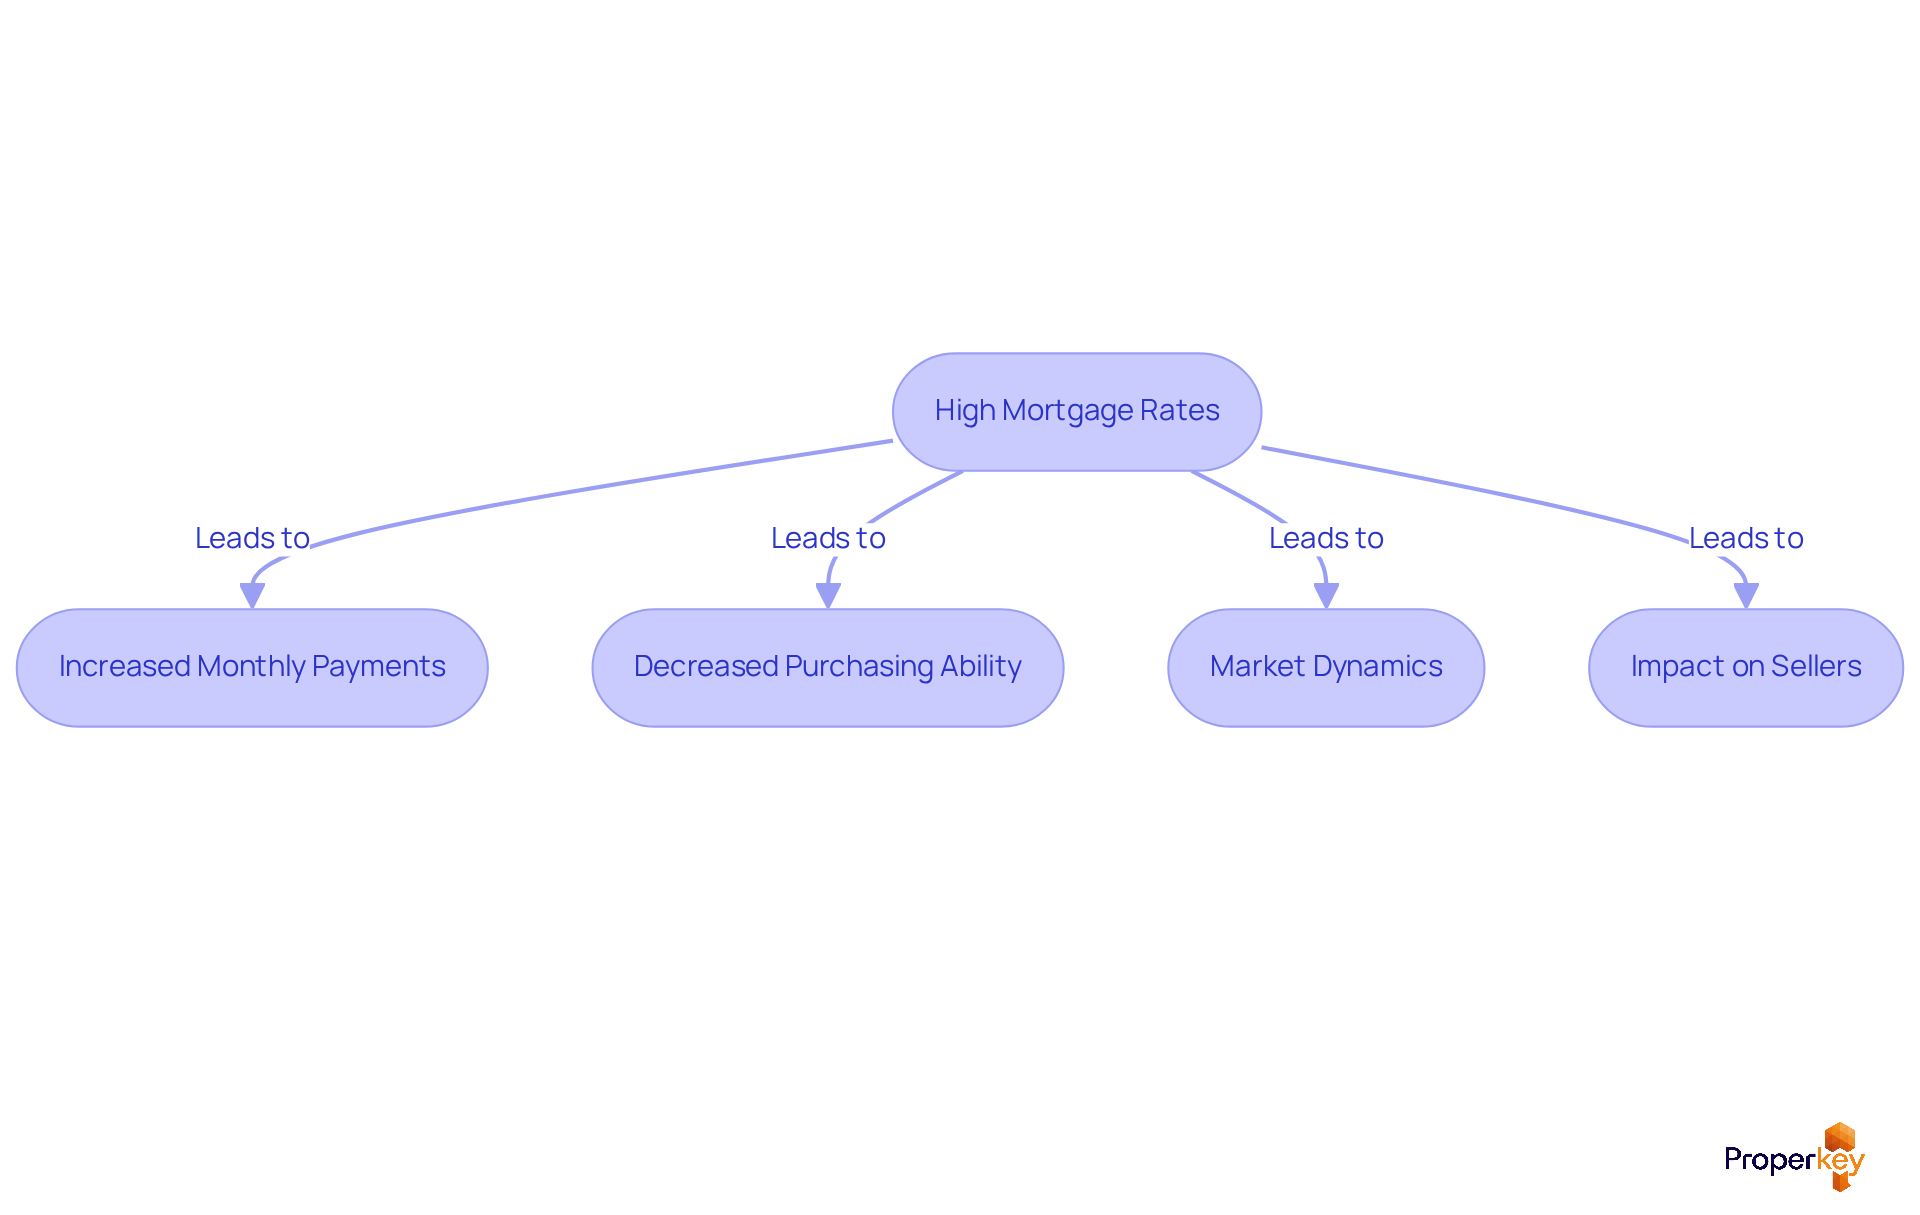
- Increased Monthly Payments: Rising rates lead to higher monthly mortgage payments, straining budgets and limiting the amount buyers can afford. For example, a 1% rise in borrowing costs can diminish a purchaser's purchasing ability by roughly 10%. This means that an individual who could purchase a $500,000 house at a 3% interest might only be able to afford a $350,000 property at 6%.
- Decreased Purchasing Ability: As loan costs climb, buyers find their purchasing power shrinking, which means they often have to adjust their home price expectations. This shift can significantly impact their ability to secure desirable properties in competitive markets.
- Market Dynamics: Elevated mortgage costs frequently result in reduced demand from purchasers, as prospective clients may discover themselves unable to afford the market. This trend often leads to longer selling times. Sellers may also face lower home prices, making the market even more challenging.
- Impact on Sellers: Sellers may need to recalibrate their pricing strategies due to decreased customer demand. Without adjustments, they risk prolonged listings and unsold properties. Understanding how high mortgage interest rates impact affordability is crucial for sellers to position their homes competitively in the market. For instance, as inventory levels increase, sellers who do not modify their expectations may find it difficult to draw in customers.
Taking a close look at these impacts helps both buyers and sellers navigate the tricky waters of today’s market characterized by high mortgage interest rates.
Conclusion
High mortgage interest rates present significant challenges for both buyers and sellers in the real estate market. Grasping how these rates impact your financial landscape is vital; they shape affordability and dictate market trends. As interest rates rise, the cost of borrowing increases, leading to higher monthly payments that can deter potential buyers and complicate selling strategies for homeowners.
Several critical factors drive high mortgage interest rates, including:
- Economic conditions
- Federal Reserve policies
- Individual credit scores
It’s essential to be informed about these elements to navigate the current market effectively. Practical strategies such as:
- Improving credit scores
- Comparing loan offers
- Considering refinancing options
can help manage the impact of high rates.
In this shifting market, being proactive and informed is your best strategy for success. Buyers and sellers alike must adapt to the realities of high mortgage interest rates, leveraging available tools and strategies to make informed decisions. Those who adapt and leverage the right strategies will find opportunities even in a tough market.
Frequently Asked Questions
What are mortgage interest rates and why are they important?
Mortgage interest rates reflect the cost of borrowing money to purchase a home, expressed as a percentage of the loan amount. They are crucial because they determine monthly loan payments and the overall cost of a loan over its lifetime, significantly impacting affordability for home buyers.
How do high mortgage interest rates affect home buyers?
High mortgage interest rates can lead to increased monthly payments, making homes less affordable for prospective buyers. This discouragement can reduce buyer demand in the real estate market.
What was the average mortgage interest rate for a 30-year fixed loan as of August 2026?
As of August 2026, the average mortgage interest rate for a 30-year fixed loan reached approximately 6.49%.
How do high mortgage interest rates influence home sellers?
Sellers need to understand mortgage interest rates to price their homes competitively. High rates can dampen buyer demand, leading some homeowners to hesitate in selling, especially if they have lower-rate loans. This can limit housing inventory and result in reduced listing prices.
What impact does a small increase in interest rates have on loan costs?
Even a slight increase in interest rates can significantly affect loan costs. For example, a 0.25% rise in interest on a $360,000 loan can lead to nearly $22,000 in additional interest over 30 years.
What should buyers focus on when considering mortgage costs?
Buyers should focus on securing favorable loan terms and consider total monthly payments, which include property taxes and insurance, rather than just the home price.
How can buyers simplify the financing process?
Buyers can use tools like Loanvana's financing tool, which allows them to apply once and compare hundreds of loan options side-by-side from various lenders, making it easier to navigate home financing.
Why is it essential for buyers and sellers to stay informed about financing trends?
Staying informed about financing trends is essential for both buyers and sellers to navigate the complexities of the housing market effectively, as these trends can significantly influence buyer behavior and market dynamics.
List of Sources
- Define Mortgage Interest Rates and Their Importance
- Interest Rates Impact on Housing Market and Home Prices | Chase (https://chase.com/personal/mortgage/education/financing-a-home/interest-rates-and-housing-market)
- What will happen to home prices if mortgage rates stay high this year? Experts weigh in (https://cbsnews.com/news/what-will-happen-home-prices-mortgage-rates-stay-high-experts)
- Compare Today's Mortgage Interest Rates - NerdWallet (https://nerdwallet.com/mortgages/mortgage-rates)
- The impact of today’s changing interest rates on the housing market | U.S. Bank (https://usbank.com/investing/financial-perspectives/investing-insights/interest-rates-impact-on-housing-market.html)
- How Mortgage Rates Affect Housing Affordability (https://nahb.org/blog/2025/03/how-mortgage-rates-affect-housing-affordability)
- Explore Factors Influencing Mortgage Interest Rates
- Why are mortgage rates going up in 2026? (https://rocketmortgage.com/learn/when-to-get-a-mortgage-with-rising-rates)
- Will mortgage rates drop below 6% in 2026? (https://cbsnews.com/news/will-mortgage-rates-drop-below-6-2026)
- Average U.S. long-term mortgage rate rises to 6.22%, highest in more than 3 months (https://pbs.org/newshour/economy/average-u-s-long-term-mortgage-rate-rises-to-6-22-highest-in-more-than-3-months)
- Mortgage Rates (https://freddiemac.com/pmms)
- Mortgage Rates Retreat, Still Near One-Year Peak | Bankrate (https://bankrate.com/mortgages/analysis/mortgage-rates-august-5-2026)
- Implement Strategies to Manage High Mortgage Interest Rates
- Will Mortgage Rates Go Down in 2026? | Morgan Stanley (https://morganstanley.com/insights/articles/mortgage-rates-forecast-2025-2026-will-mortgage-rates-go-down)
- What can we expect to happen to mortgage rates this year (https://cnbc.com/select/2026-mortgage-rate-outlook)
- Will mortgage rates drop below 6% in 2026? (https://cbsnews.com/news/will-mortgage-rates-drop-below-6-2026)
- Data Spotlight: The Impact of Changing Mortgage Interest Rates | Consumer Financial Protection Bureau (https://consumerfinance.gov/data-research/research-reports/data-spotlight-the-impact-of-changing-mortgage-interest-rates)
- Mortgage Rates Forecast For 2026: Experts Predict Whether Interest Rates Will Drop (https://forbes.com/advisor/mortgages/mortgage-interest-rates-forecast)
- Assess the Impact of High Mortgage Rates on Affordability
- How Interest Rates Affect the Housing Market (https://investopedia.com/mortgage/mortgage-rates/housing-market)
- High mortgage rates to keep US housing market subdued through 2026 (https://mpamag.com/us/news/general/high-mortgage-rates-to-keep-us-housing-market-subdued-through-2026/578692)
- Data Spotlight: The Impact of Changing Mortgage Interest Rates | Consumer Financial Protection Bureau (https://consumerfinance.gov/data-research/research-reports/data-spotlight-the-impact-of-changing-mortgage-interest-rates)
- How Rising Interest Rates Can Impact Your Homebuying Power (https://associatedbank.com/education/articles/personal-finance/loans-and-debt/how-rising-interest-rates-can-impact-your-homebuying)