Understanding How Often You Can Refinance a Home Equity Loan

Introduction
Navigating the complexities of home equity loans can be daunting for homeowners eager to optimize their financial strategies. With rising property values in states like California, Idaho, and Nevada, many are exploring the benefits of refinancing these loans to secure better terms or access additional funds.
But how frequently can homeowners refinance their home equity loans without incurring penalties or complications?
Let’s explore the rules and considerations of refinancing, providing you with insights to make informed financial decisions.
Define Home Equity Loans: Understanding the Basics
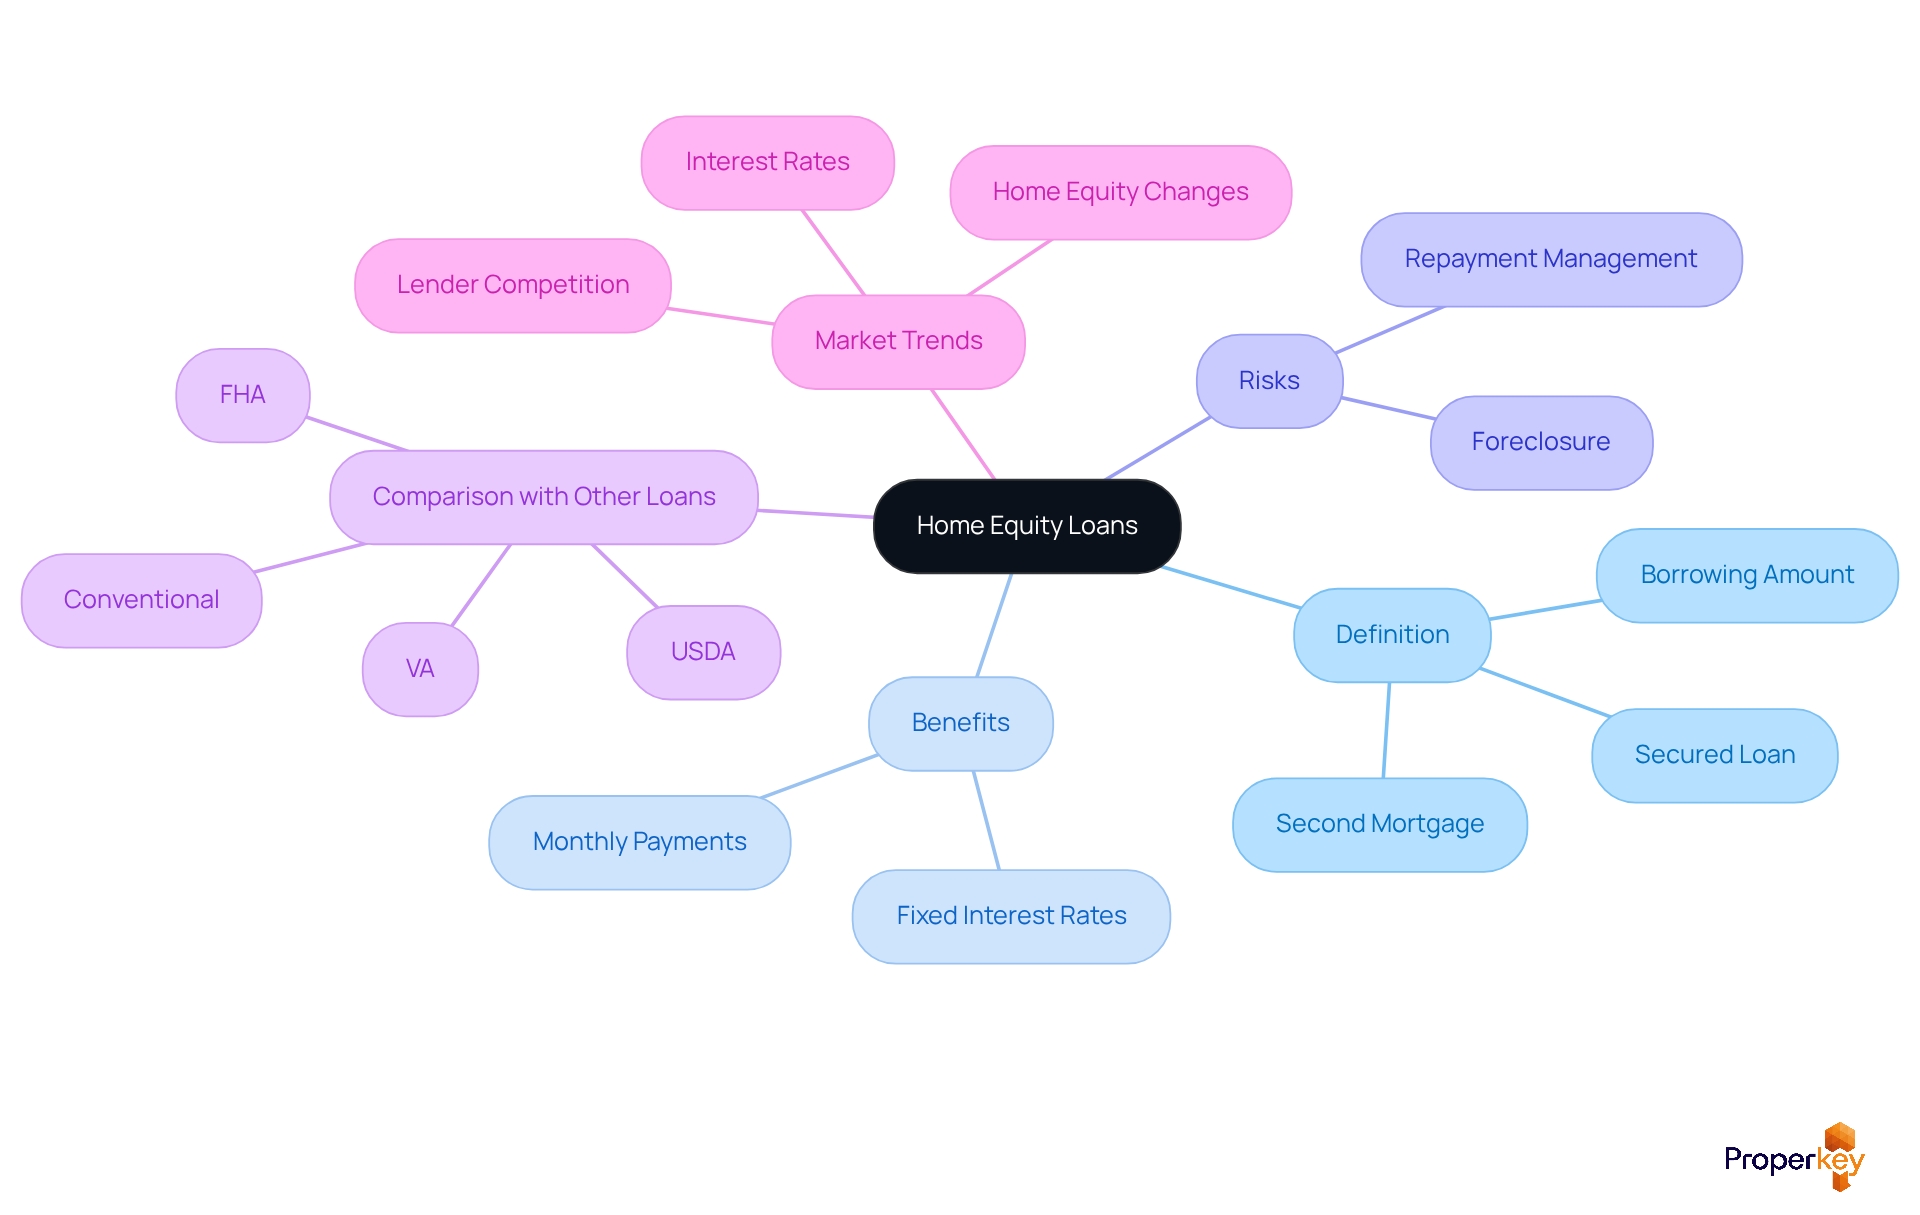
Are you aware of how property equity financing can unlock the potential of your home’s value? Often referred to as a second mortgage, this financing option allows property owners to borrow against the equity they've built in their homes. This loan is secured by your home, meaning if you can't repay, the lender could take your property. The amount you can borrow typically depends on the difference between your property's current market value and your outstanding mortgage balance. In states like California, Idaho, and Nevada, property owners have witnessed significant increases in average property values, making these financing options particularly appealing. For instance, California homeowners have seen their average property value rise from $147,133 in 2020 to $218,008 in 2025.
Home equity financing usually comes with fixed interest rates and is repaid through consistent monthly payments over a specified term. This structure makes it a favored choice for homeowners looking to finance major expenses, such as renovations or debt consolidation. As of early 2026, borrowing rates for property value in these states are competitive, with 5-year agreements around 7.97% and 10-year agreements at approximately 8.16%. This makes them a cost-effective solution compared to personal loans or credit cards.
Grasping the fundamentals of residential financing is essential for property owners aiming to utilize their asset's worth. For example, a homeowner in California with a property valued at $750,000 and an outstanding mortgage of $500,000 could potentially access up to $250,000 through a property financing option, depending on lender policies and specific terms. However, it’s crucial to recognize that borrowing against your property carries risks, including the possibility of foreclosure if repayments are not managed properly. Understanding how to leverage this asset wisely can transform your financial future, providing flexibility for various needs, from funding renovations to consolidating debt.
In addition to home equity financing, homeowners should also explore other mortgage alternatives such as:
- Conventional
- FHA
- VA
- USDA
Traditional financing is ideal for those with strong credit and stable income, while FHA programs cater to first-time buyers with lower credit scores. VA financing offers favorable terms for veterans and active military personnel, and USDA assistance is designed for rural homebuyers. Each of these options has unique characteristics that can enhance property value financing, offering a comprehensive financial solution for diverse borrower needs. As Linda Bell, a residential lending specialist, states, "Property value is more than just a figure." Understanding how to leverage this asset wisely can transform your financial future.
Contextualize Refinancing: Importance in Real Estate Transactions
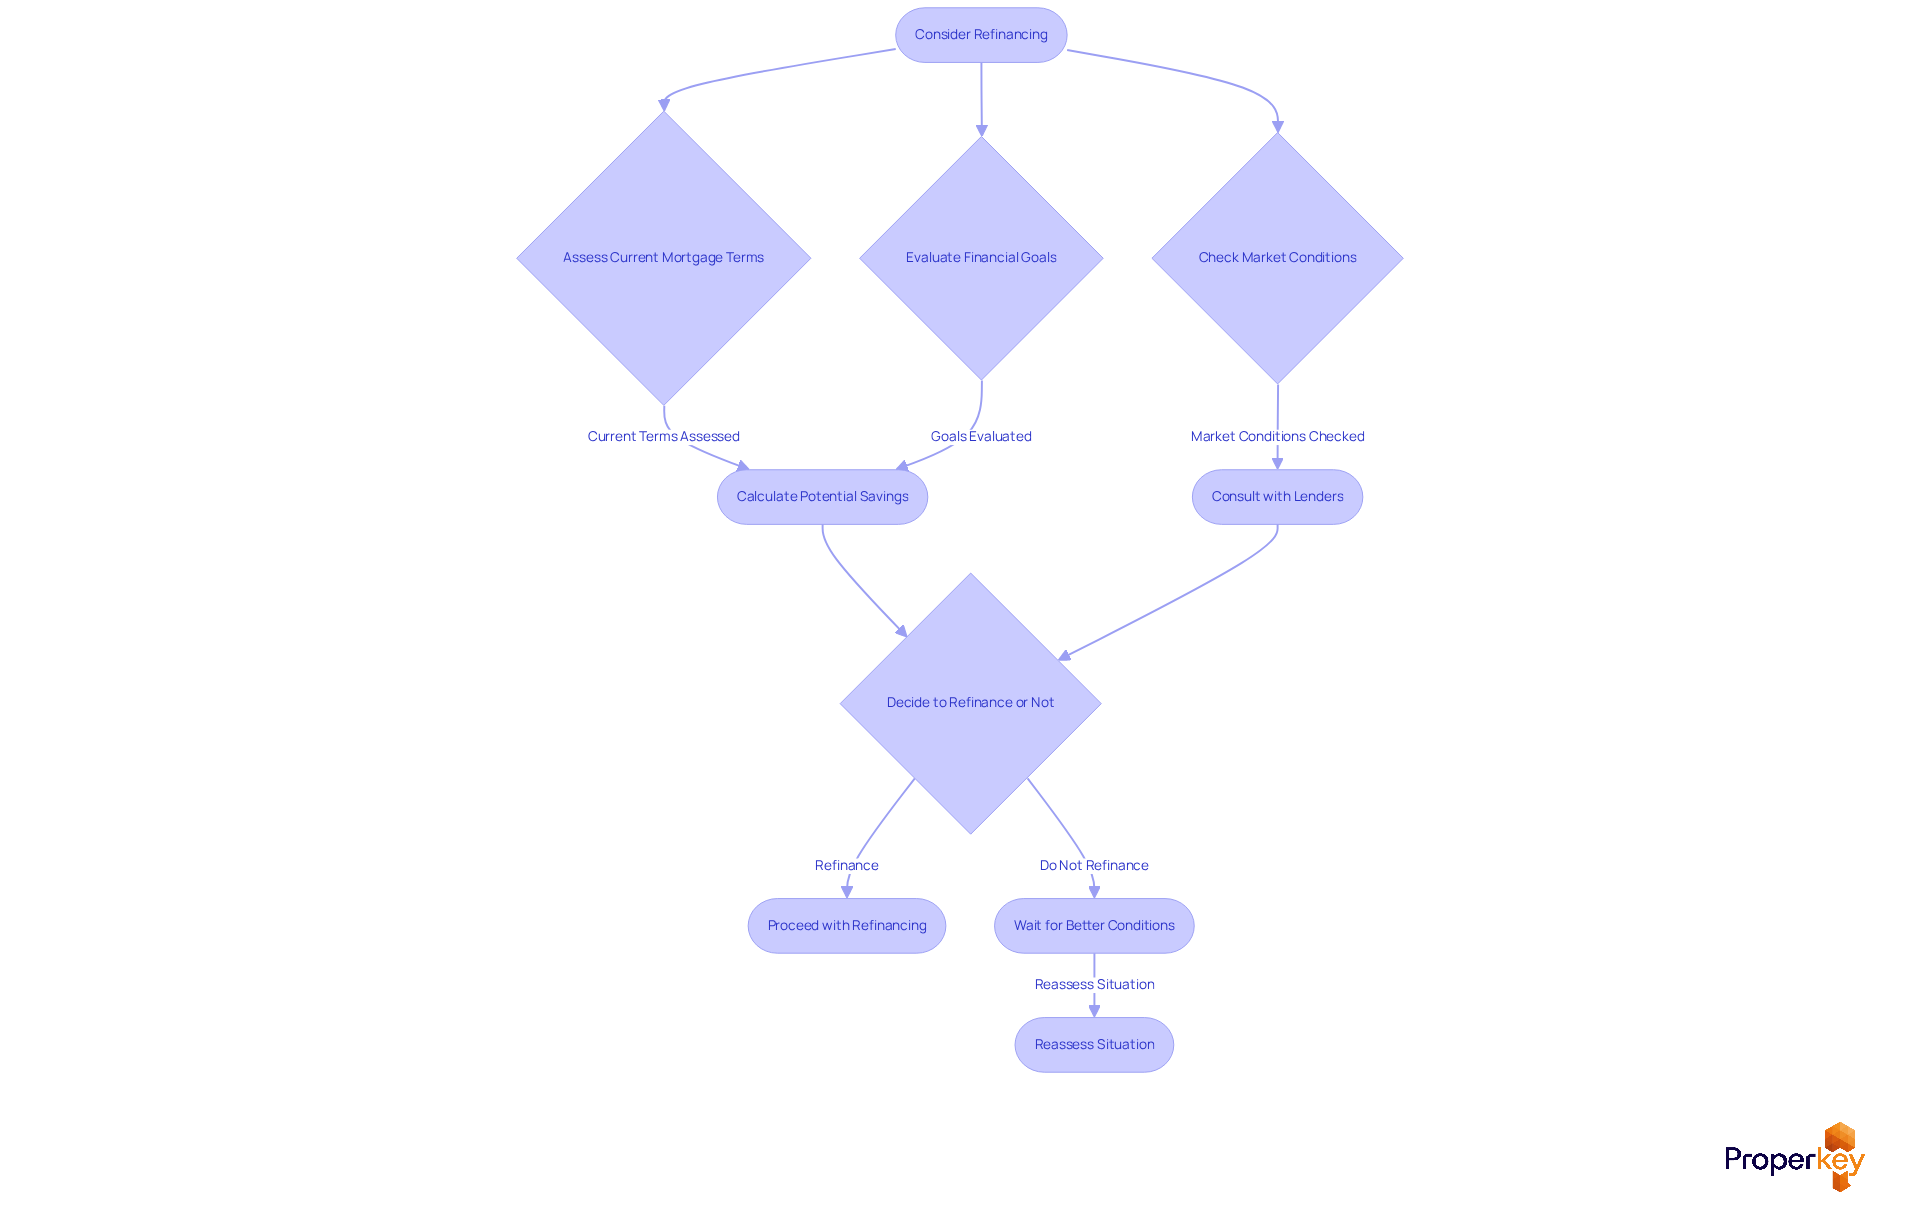
Are you struggling with high mortgage payments that strain your budget? When considering refinancing a property loan, it's important to understand how often you can refinance a home equity loan to secure better terms or access additional funds. Refinancing is essential for homeowners, prompting them to consider how often they can refinance a home equity loan to adjust their financial commitments in response to changing market conditions and personal needs. With mortgage rates projected to decline, many are considering how often can you refinance a home equity loan to achieve reduced monthly payments, making it an appealing option. In 2026, refinancing is expected to represent approximately 35% of total mortgage originations, highlighting its growing importance in the market.
Moreover, knowing how often you can refinance a home equity loan can enable property owners to tap into their home's equity for various financial needs, such as funding education or making investments, thus enhancing their financial flexibility. In states like California, Idaho, and Nevada, where property values fluctuate, residents may find refinancing particularly beneficial. Homeowners who bought at higher rates may wonder how often can you refinance a home equity loan to save hundreds on their monthly payments.
Loanvana makes the refinancing process straightforward. With our tool, you can easily apply once and compare numerous options from various lenders, making it simple to find the best refinancing solution for your needs. If you provide a copy of your most recent mortgage statement, Loanvana can show you how to save money. Already in the process? Present your written financing estimate (LE), and Loanvana will surpass it. Homeowners often wonder how often they can refinance a home equity loan, as refinancing a $300,000 mortgage from 7% to 6% could save them approximately $188 monthly and $56,400 over 25 years. Such savings can be pivotal for families looking to manage their budgets effectively. Additionally, knowing how often you can refinance a home equity loan can eliminate private mortgage insurance (PMI) for those who have built sufficient equity, potentially saving $1,800 each year on a $300,000 mortgage, further enhancing financial outcomes.
Ultimately, the decision to refinance should consider how often you can refinance a home equity loan based on individual financial goals and current market realities. Homeowners in these states should consider how often they can refinance a home equity loan, along with their unique situations and the potential benefits of refinancing, to make informed decisions that align with their long-term financial strategies. By taking action now, you can secure a more favorable financial future through refinancing.
Trace the Evolution: History of Home Equity Loans and Refinancing
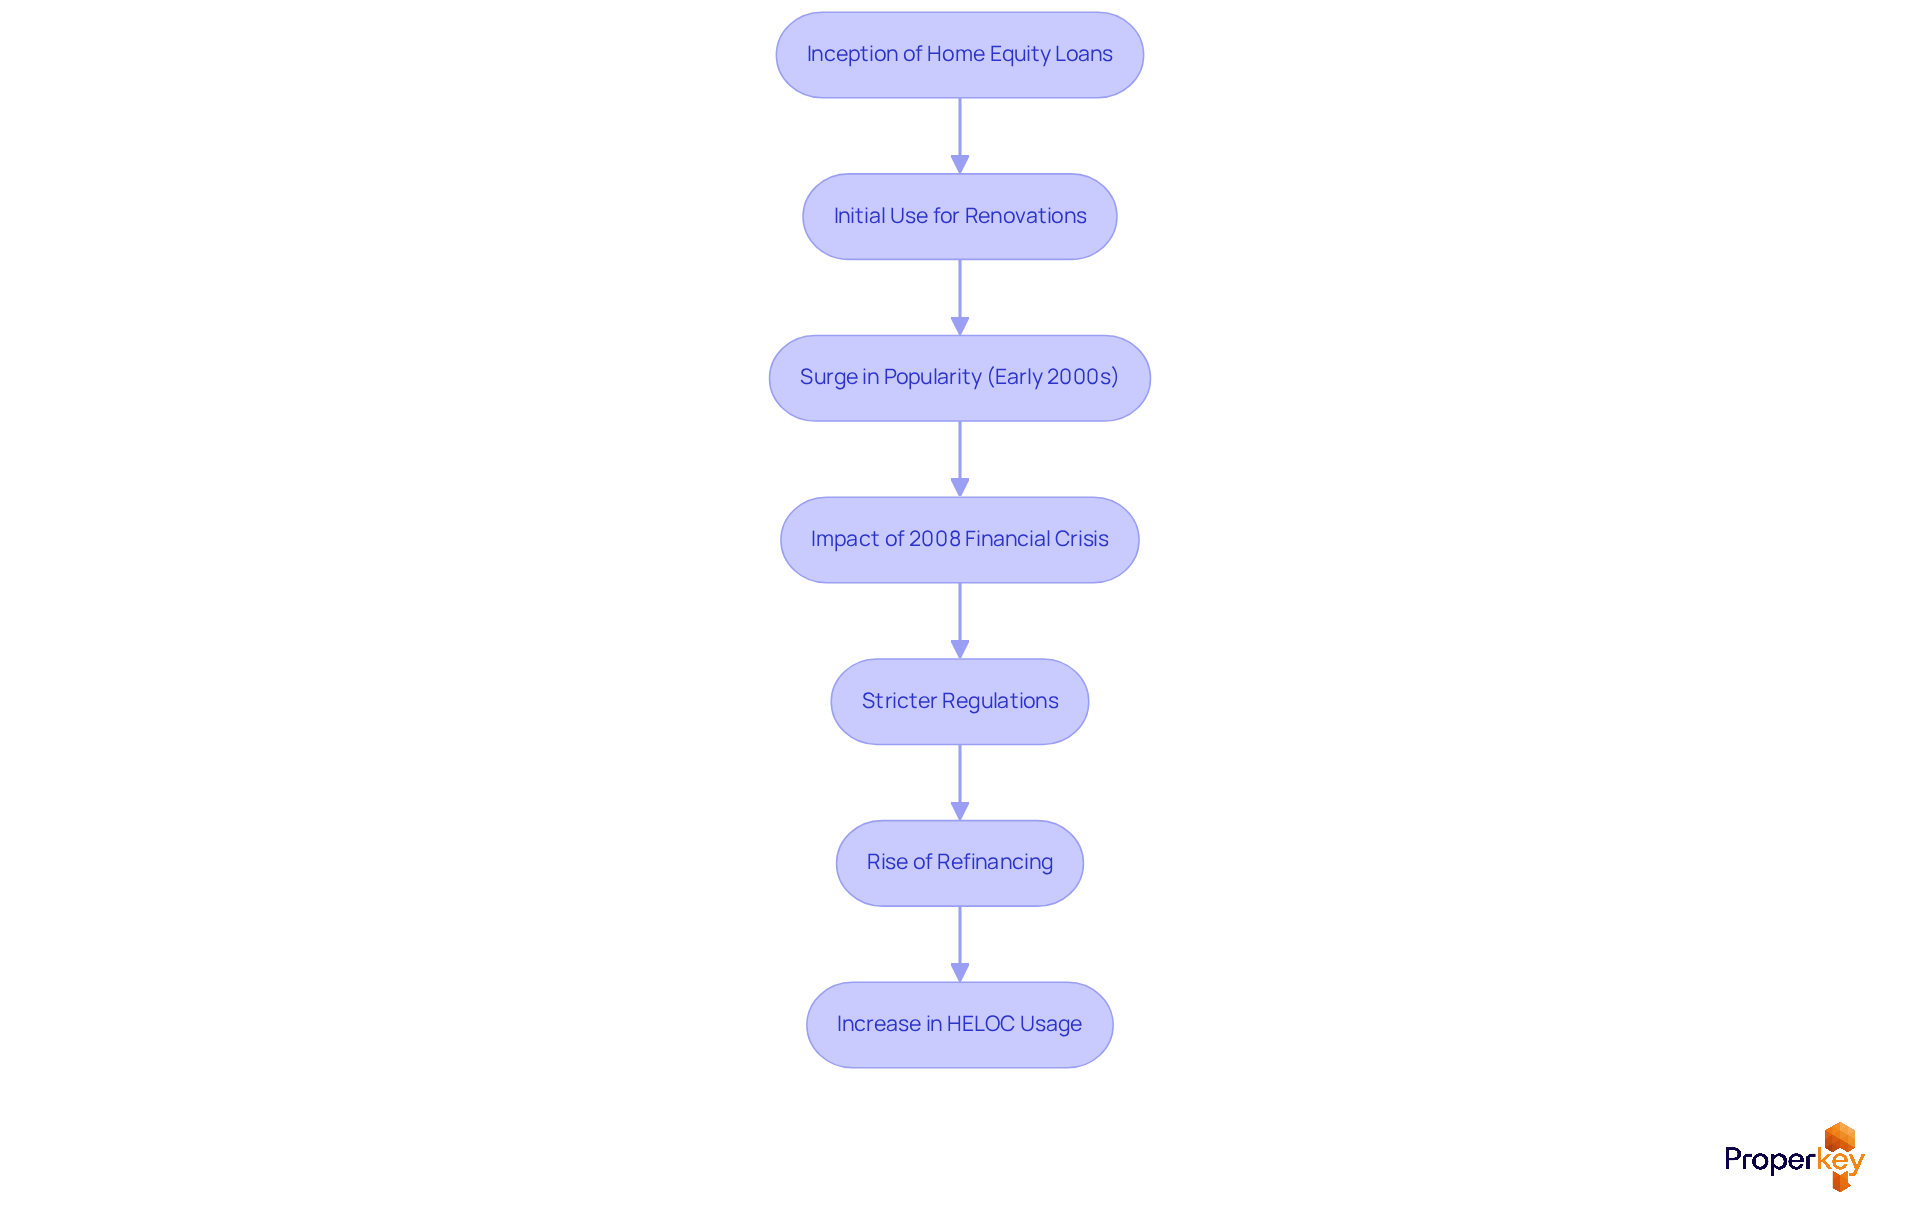
Navigating the complexities of home equity financing can be daunting for many homeowners, especially as the landscape continues to evolve. Home equity financing has transformed significantly since its inception. Initially, these loans were primarily used for renovations and major purchases. However, as the housing market grew and homeowners became more informed, the ways they used these loans expanded. The early 2000s saw a surge in popularity, fueled by rising property values and aggressive lending practices. In states like California, Idaho, and Nevada, property owners began leveraging their assets more frequently, signaling a growing trend toward utilizing property value for various financial needs.
The financial crisis of 2008 prompted a reevaluation of lending practices, leading to stricter regulations and a more cautious approach to borrowing. This shift resulted in a decrease in residential financing originations, as lenders tightened their standards. However, as the market stabilized, refinancing property value loans became a common strategy for homeowners looking to optimize their financial situations. By 2025, residential property loans accounted for 17.52% of all U.S. mortgage transactions, indicating a strong recovery and adjustment to new market conditions.
In recent years, property owners in these states have increasingly opted for lines of credit (HELOCs) as an alternative to conventional refinancing. This trend is particularly evident among lower-income borrowers, where the share of HELOC users rose from 9.18% in Q1 2022 to 10.82% in Q1 2025, reflecting a growing reliance on these products for liquidity without sacrificing low fixed mortgage rates. The typical HELOC sum per borrower also rose considerably, from $67,357 in Q3 2022 to $76,562 in Q1 2025, highlighting the changing environment of property borrowing.
Case studies from California, Idaho, and Nevada illustrate how property owners are utilizing these financial tools to navigate their unique market conditions. For instance, in California, where property values have steadily increased, homeowners are more likely to leverage their assets for investments or renovations. In contrast, in Idaho and Nevada, the focus may shift toward consolidating debt or financing significant life events. This shift shows that homeowners are becoming savvier about how they borrow and use their equity. As homeowners adapt to these changes, understanding the nuances of home equity financing will be crucial for maximizing their financial potential.
Identify Key Factors: How Often Can You Refinance?
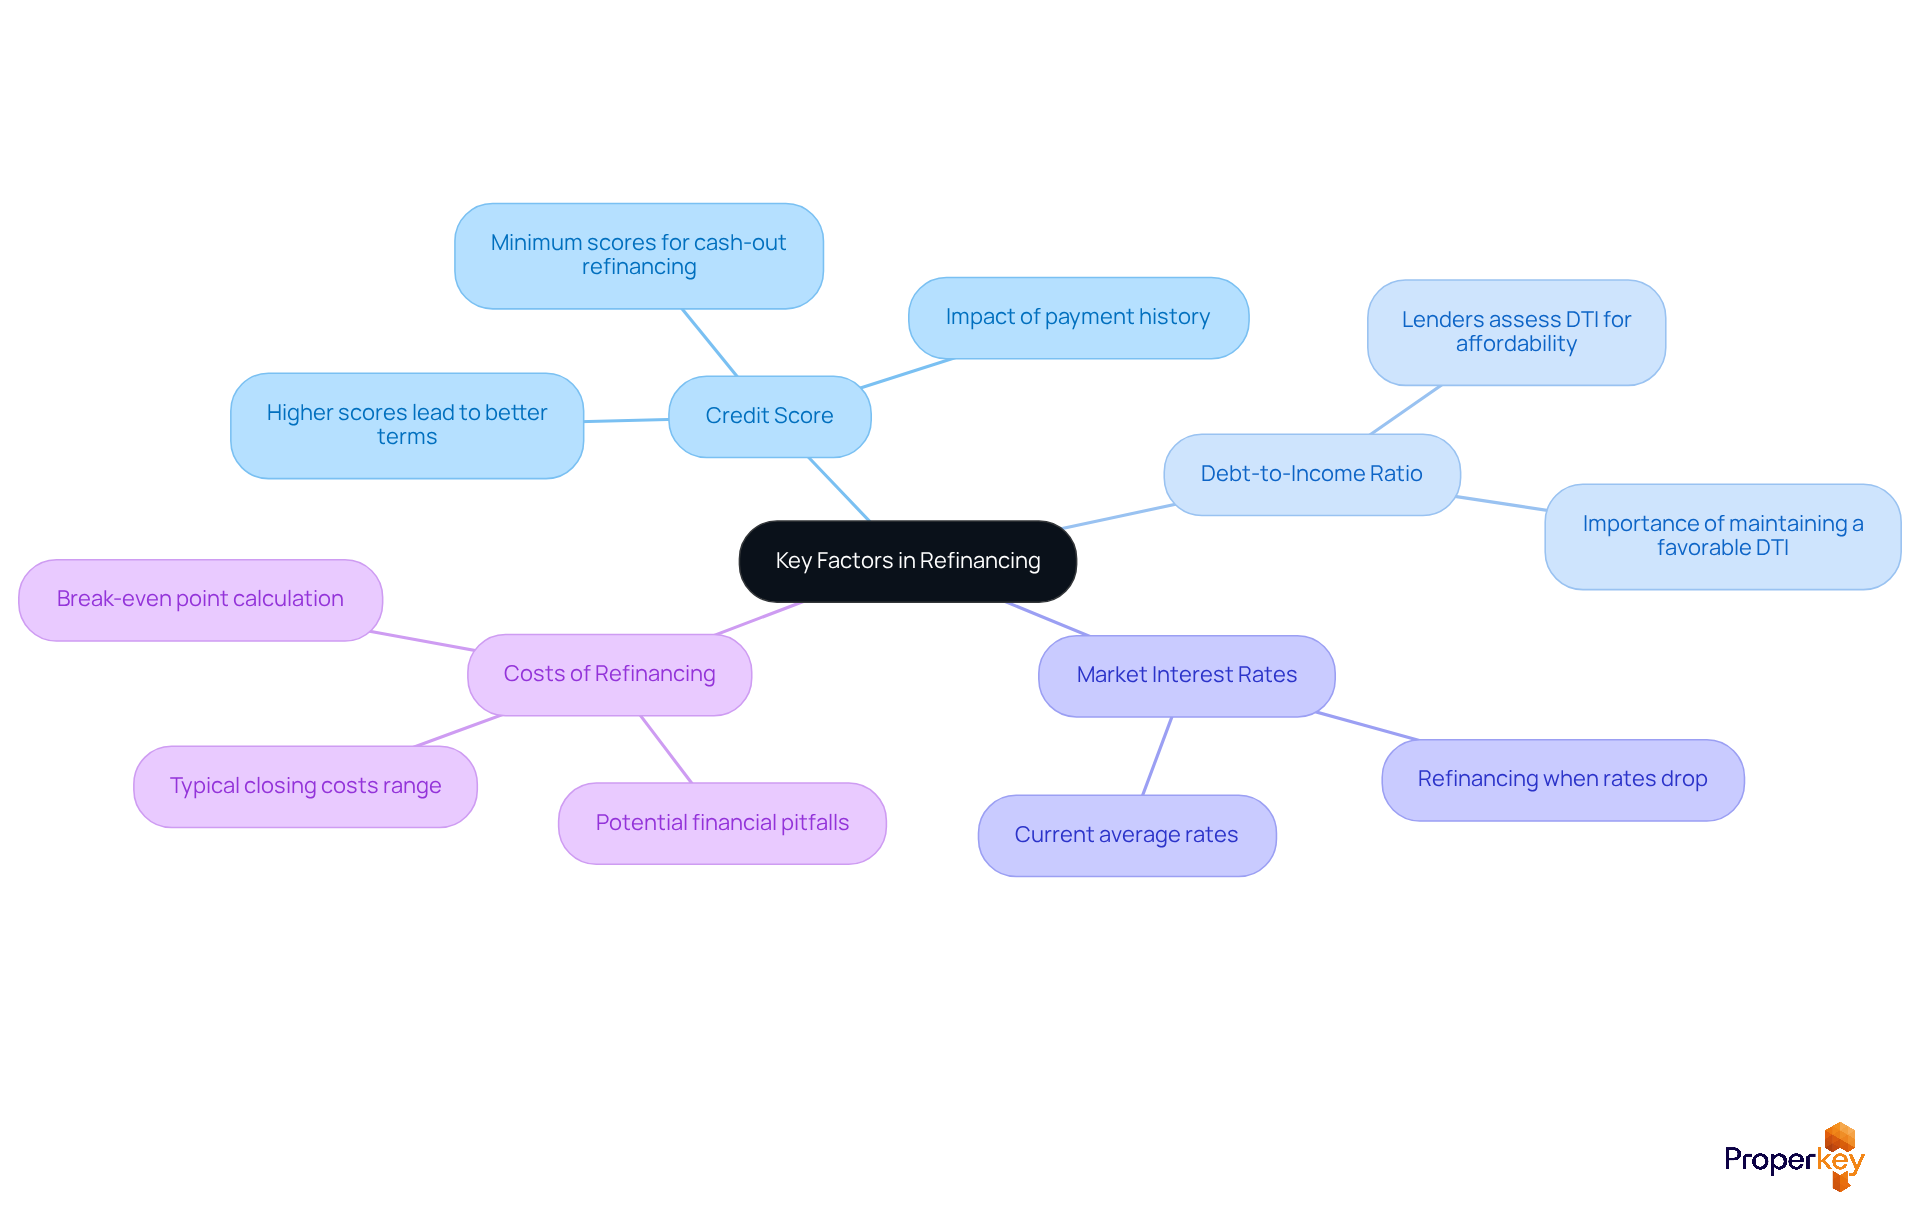
Are you considering refinancing your home equity loan? While there are no strict limits on how often you can refinance a home equity loan, several critical factors can significantly impact your decision regarding this process. Most lenders require a seasoning period of six months to a year before you can refinance, allowing them to assess your financial stability and the value of your property.
Key factors that affect refinancing frequency include:
- Credit Score: A higher credit score can enhance refinancing options, potentially leading to better interest rates and terms.
- Debt-to-Income Ratio (DTI): Lenders assess DTI to determine if property owners can manage their monthly debt payments, including the new mortgage payment after refinancing.
- Market Interest Rates: Current rates play a significant role; property owners may choose to refinance when rates drop to secure lower payments.
- Costs of Refinancing: Homeowners should consider closing costs and fees, which typically range from 3% to 6% of the loan amount. Neglecting to understand these costs could lead to financial pitfalls, so it's essential to evaluate them carefully before proceeding with refinancing.
For instance, a property owner in California with a $300,000 mortgage might incur closing costs between $9,000 and $18,000 when refinancing. Failing to account for these costs can lead to unexpected financial burdens, undermining the benefits of refinancing.
In practice, property owners have successfully navigated how often they can refinance a home equity loan to achieve lower rates or consolidate debt. However, they must weigh the benefits against the costs and potential impacts on their credit scores. By carefully weighing these factors, you can make informed decisions that enhance your financial future rather than complicate it.
Provide Examples: When Refinancing Makes Sense
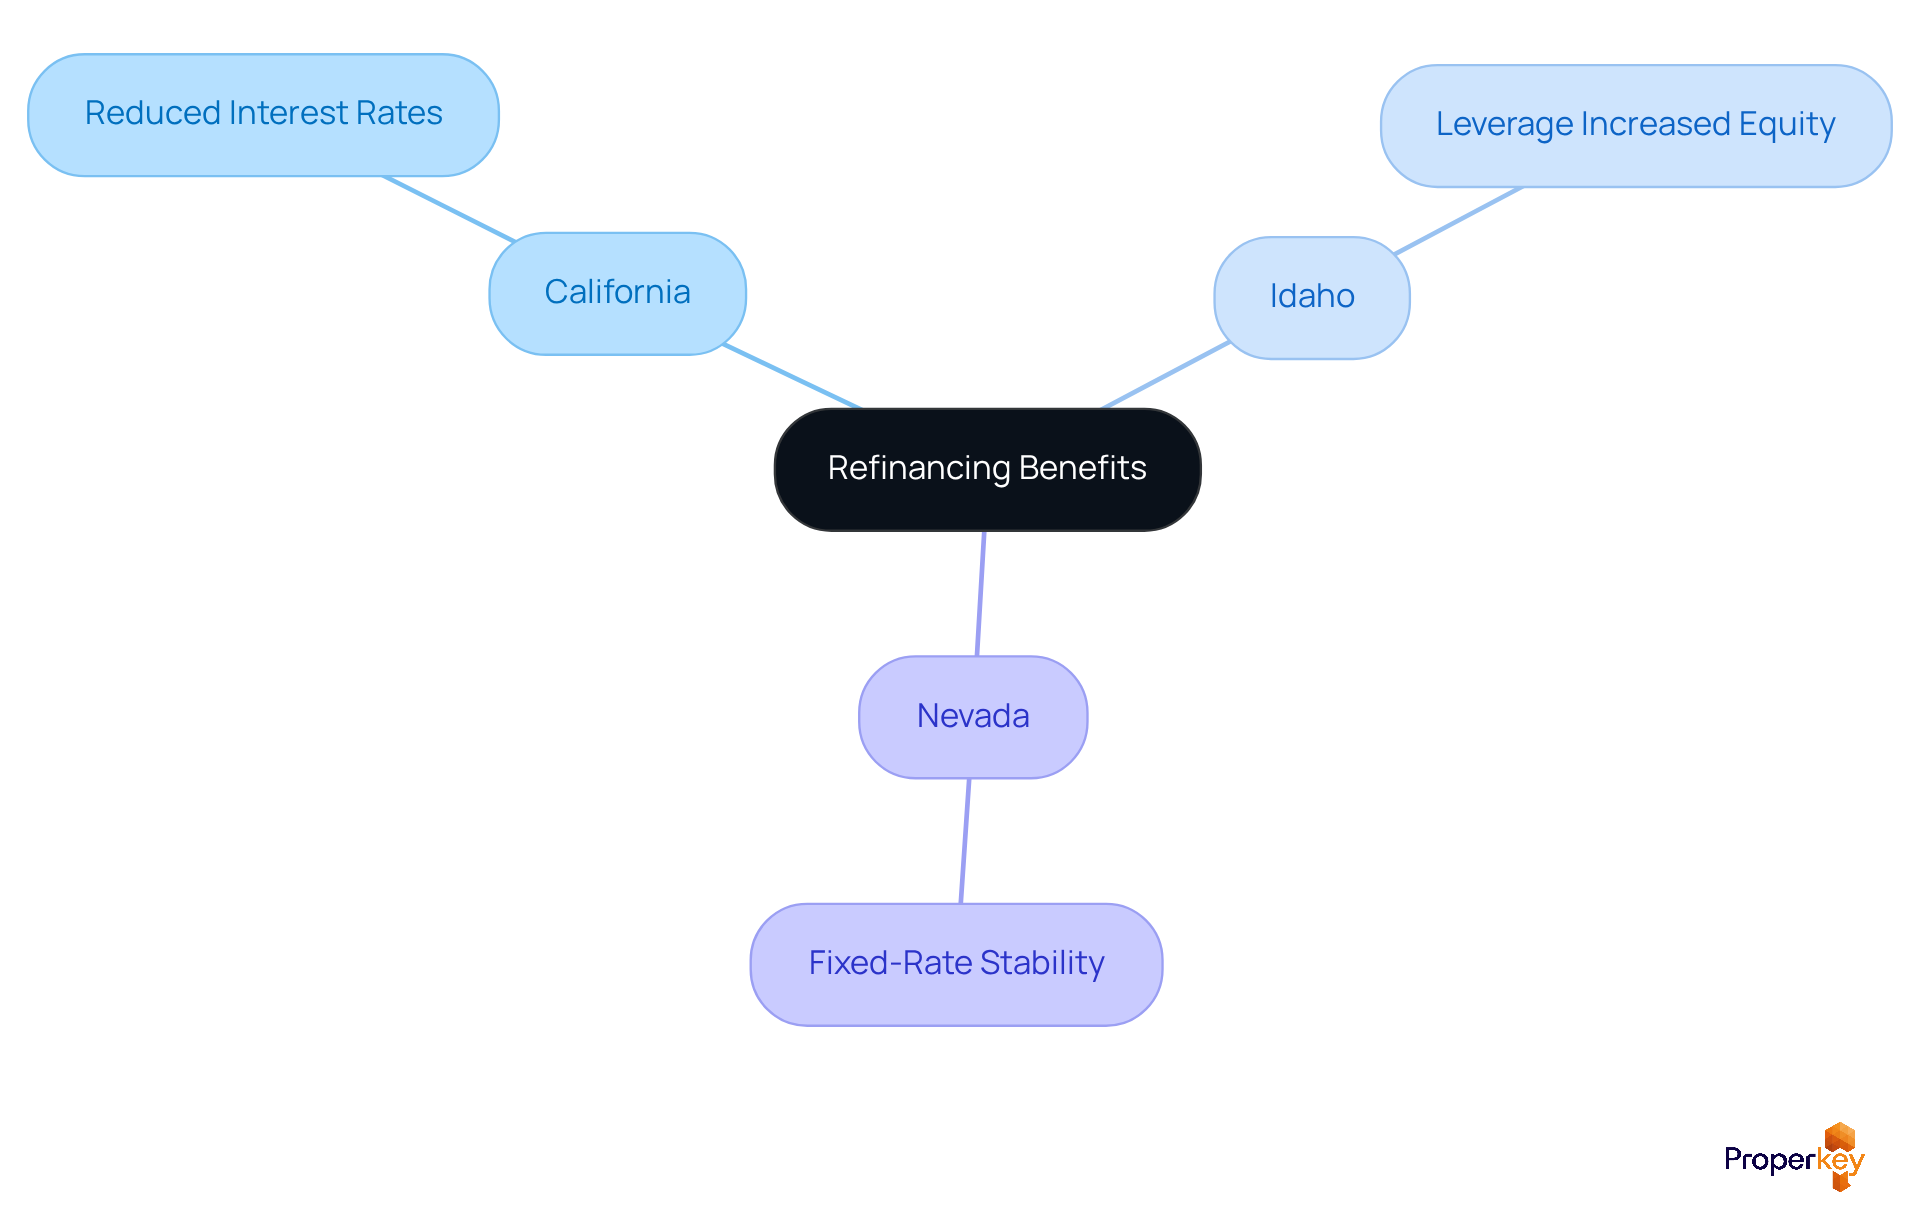
Navigating the complexities of refinancing can be daunting for many homeowners, yet it holds the potential for substantial financial benefits. Refinancing a home value credit is a strategic move that can yield significant benefits. For instance, property owners in California who have experienced notable enhancements in their credit scores since obtaining their initial financing are often qualified for reduced interest rates, leading to substantial savings over the loan term.
In Idaho, rising property values empower homeowners to leverage increased equity for renovations or to consolidate higher-interest debts, enhancing their financial flexibility. Homeowners in Nevada should consider refinancing from an adjustable-rate to a fixed-rate loan to secure stable monthly payments, especially in today’s unpredictable market.
These scenarios highlight the importance of evaluating your financial situation and the market landscape to make informed refinancing decisions that align with your goals.
Conclusion
Navigating the complexities of home equity loans and refinancing can be daunting for homeowners, yet understanding these elements is crucial for financial success. The ability to refinance a home equity loan offers significant advantages, allowing property owners to adjust their financial commitments in response to changing market conditions and personal needs. Grasping the rules and considerations of refinancing empowers homeowners to make informed decisions that significantly enhance their financial flexibility and security.
Throughout this article, we’ve explored the definition of home equity loans, the importance of refinancing in real estate transactions, and the historical evolution of these financial products. Key factors such as credit scores, debt-to-income ratios, and market interest rates play a crucial role in determining how often homeowners can refinance. Real-world examples have illustrated how refinancing can lead to substantial savings and improved financial outcomes, particularly in states like California, Idaho, and Nevada.
Ultimately, embracing the refinancing process can be the key to unlocking a more secure financial future, empowering homeowners to make choices that truly reflect their aspirations. By taking proactive steps and leveraging the opportunities available, property owners can navigate the complexities of home equity financing and make decisions that align with their long-term financial goals.
Frequently Asked Questions
What is a home equity loan?
A home equity loan, often referred to as a second mortgage, allows property owners to borrow against the equity they have built in their homes. It is secured by the home, meaning if the borrower cannot repay, the lender could take the property.
How is the amount for a home equity loan determined?
The amount you can borrow typically depends on the difference between your property's current market value and your outstanding mortgage balance.
What are the typical interest rates for home equity loans in 2026?
As of early 2026, borrowing rates for home equity loans in states like California, Idaho, and Nevada are competitive, with 5-year agreements around 7.97% and 10-year agreements at approximately 8.16%.
What are common uses for home equity loans?
Home equity loans are often used to finance major expenses such as home renovations or debt consolidation.
What risks are associated with borrowing against home equity?
Borrowing against your property carries risks, including the possibility of foreclosure if repayments are not managed properly.
What other mortgage alternatives should homeowners consider?
Homeowners should explore other mortgage alternatives such as Conventional, FHA, VA, and USDA loans, each with unique characteristics that can enhance property value financing.
How often can homeowners refinance a home equity loan?
Homeowners can refinance a home equity loan as needed to secure better terms or access additional funds, especially in response to changing market conditions and personal financial needs.
What are the potential benefits of refinancing a home equity loan?
Refinancing can lead to reduced monthly payments, eliminate private mortgage insurance (PMI) for those with sufficient equity, and provide access to funds for various financial needs.
How can Loanvana assist with refinancing?
Loanvana simplifies the refinancing process by allowing users to apply once and compare options from various lenders. They can also show potential savings based on recent mortgage statements.
What should homeowners consider before refinancing?
Homeowners should consider their individual financial goals, current market realities, and how often they can refinance a home equity loan to make informed decisions that align with their long-term financial strategies.
List of Sources
- Define Home Equity Loans: Understanding the Basics
- Home equity loan pros and cons to know for 2026 (https://cbsnews.com/news/home-equity-loan-pros-and-cons-to-know-for-2026)
- States Where Home Equity's Grown The Most And Least | Bankrate (https://bankrate.com/home-equity/best-and-worst-states-for-home-equity-study)
- Home Equity News Headlines - HELN News (https://hel.news)
- Home Equity Loan and HELOC Rates Hold Near 2026 Lows, but Inflation Concerns Signal Potential Increases - Forward EPS Estimate (https://bvwd.ca.gov/expert-time/Home-Equity-Loan-and-HELOC-Rates-Hold-Near-2026-Lows-but-Inflation-Concerns-Signal-Potential-Increases-12-5446)
- Thinking About Using Your Home Equity? What to Know About Rates and Risks (https://kiplinger.com/personal-finance/home-equity-loans/what-to-know-before-tapping-home-equity)
- Contextualize Refinancing: Importance in Real Estate Transactions
- US Mortgage Statistics 2026: Debt, Delinquency and Foreclosure Data (https://lendingtree.com/home/mortgage/u-s-mortgage-market-statistics)
- Refinancing Your Mortgage in 2026: Timing & Strategies (https://saukmortgagegroup.com/refinancing-mortgage-2026-timing-benefits-strategies)
- 7 Key Insights on Refinancing Your Mortgage in 2026: Pros, Cons, and When It Makes Sense (https://amerisave.com/learn/key-insights-on-refinancing-your-mortgage-in-pros-cons-and-when-it-makes-sense)
- Homeowners turn to cash-out refinancing to take advantage of big gains in home equity (https://fox40.com/news/business/ap-business/ap-homeowners-turn-to-cash-out-refinancing-to-take-advantage-of-big-gains-in-home-equity)
- Mortgage Rates on the Decline: Should You Refinance in 2026? (https://johnsonfinancialgroup.com/about-us/newsroom/mortgage-rates-on-the-decline-should-you-refinance-in-2026)
- Trace the Evolution: History of Home Equity Loans and Refinancing
- Tracking the Shift from Mortgage Refinancings to HELOCs (https://stlouisfed.org/on-the-economy/2026/jun/tracking-shift-mortgage-refinancings-helocs)
- Home Equity News Headlines - HELN News (https://hel.news)
- Home Equity Loans Capture Record Share As Homeowners Stay Put (https://nationalmortgageprofessional.com/news/home-equity-loans-capture-record-share-homeowners-stay-put)
- HELOC and Home Equity Trends: Navigating the New Lending Landscape (https://meridianlink.com/blog/heloc-home-equity-trends-navigating-landscape)
- MBA Home Equity Study Shows Increase in Originations, Debt Outstanding in 2024 (https://mba.org/news-and-research/newsroom/news/2025/07/28/mba-home-equity-study-shows-increase-in-originations--debt-outstanding-in-2024)
- Identify Key Factors: How Often Can You Refinance?
- 3 home equity loan moves borrowers should make for 2026 (https://cbsnews.com/news/home-equity-loan-moves-borrowers-should-make-for-2026)
- Current Home Equity Loan Rates (https://wsj.com/buyside/personal-finance/mortgage/home-equity-loan-rates)
- Homeowners Are Raiding Home Equity Instead of Refinancing (https://money.usnews.com/loans/mortgages/articles/homeowners-are-raiding-home-equity-instead-of-refinancing)
- How often can you refinance your home? (https://rocketmortgage.com/learn/how-often-can-you-refinance-your-home)
- Cash Out Refinance Minimum Credit Scores 2026 (https://freedommortgage.com/learn/home-equity/cash-out-refinance-credit-score)
- Provide Examples: When Refinancing Makes Sense
- States Where Home Equity's Grown The Most And Least | Bankrate (https://bankrate.com/home-equity/best-and-worst-states-for-home-equity-study)
- Average HELOC Balances Surpass $50K in 2026 (https://experian.com/blogs/ask-experian/research/home-equity-line-of-credit-study)
- Refinancing Your Mortgage in 2026: Timing & Strategies (https://saukmortgagegroup.com/refinancing-mortgage-2026-timing-benefits-strategies)
- Will a HELOC or home equity loan be better in 2026? Lending experts weigh in (https://cbsnews.com/news/will-a-heloc-or-home-equity-loan-be-better-in-2026-lending-experts-weigh-in)
- Current Refinance Rates - Compare Rates Today | Bankrate (https://bankrate.com/mortgages/refinance-rates)