What Is PMI on a Home Loan? Understanding Its Role and Importance
Introduction
Navigating the complexities of home financing can be daunting, especially when it comes to understanding Private Mortgage Insurance (PMI). This essential insurance not only safeguards lenders against potential defaults but also plays a pivotal role in making homeownership attainable, particularly for first-time buyers grappling with high market prices.
So, how does PMI impact your mortgage costs, and what does it mean for your journey to homeownership? Grasping these nuances can empower buyers to make confident choices in their home financing journey.
Define PMI: What It Means in Home Loans
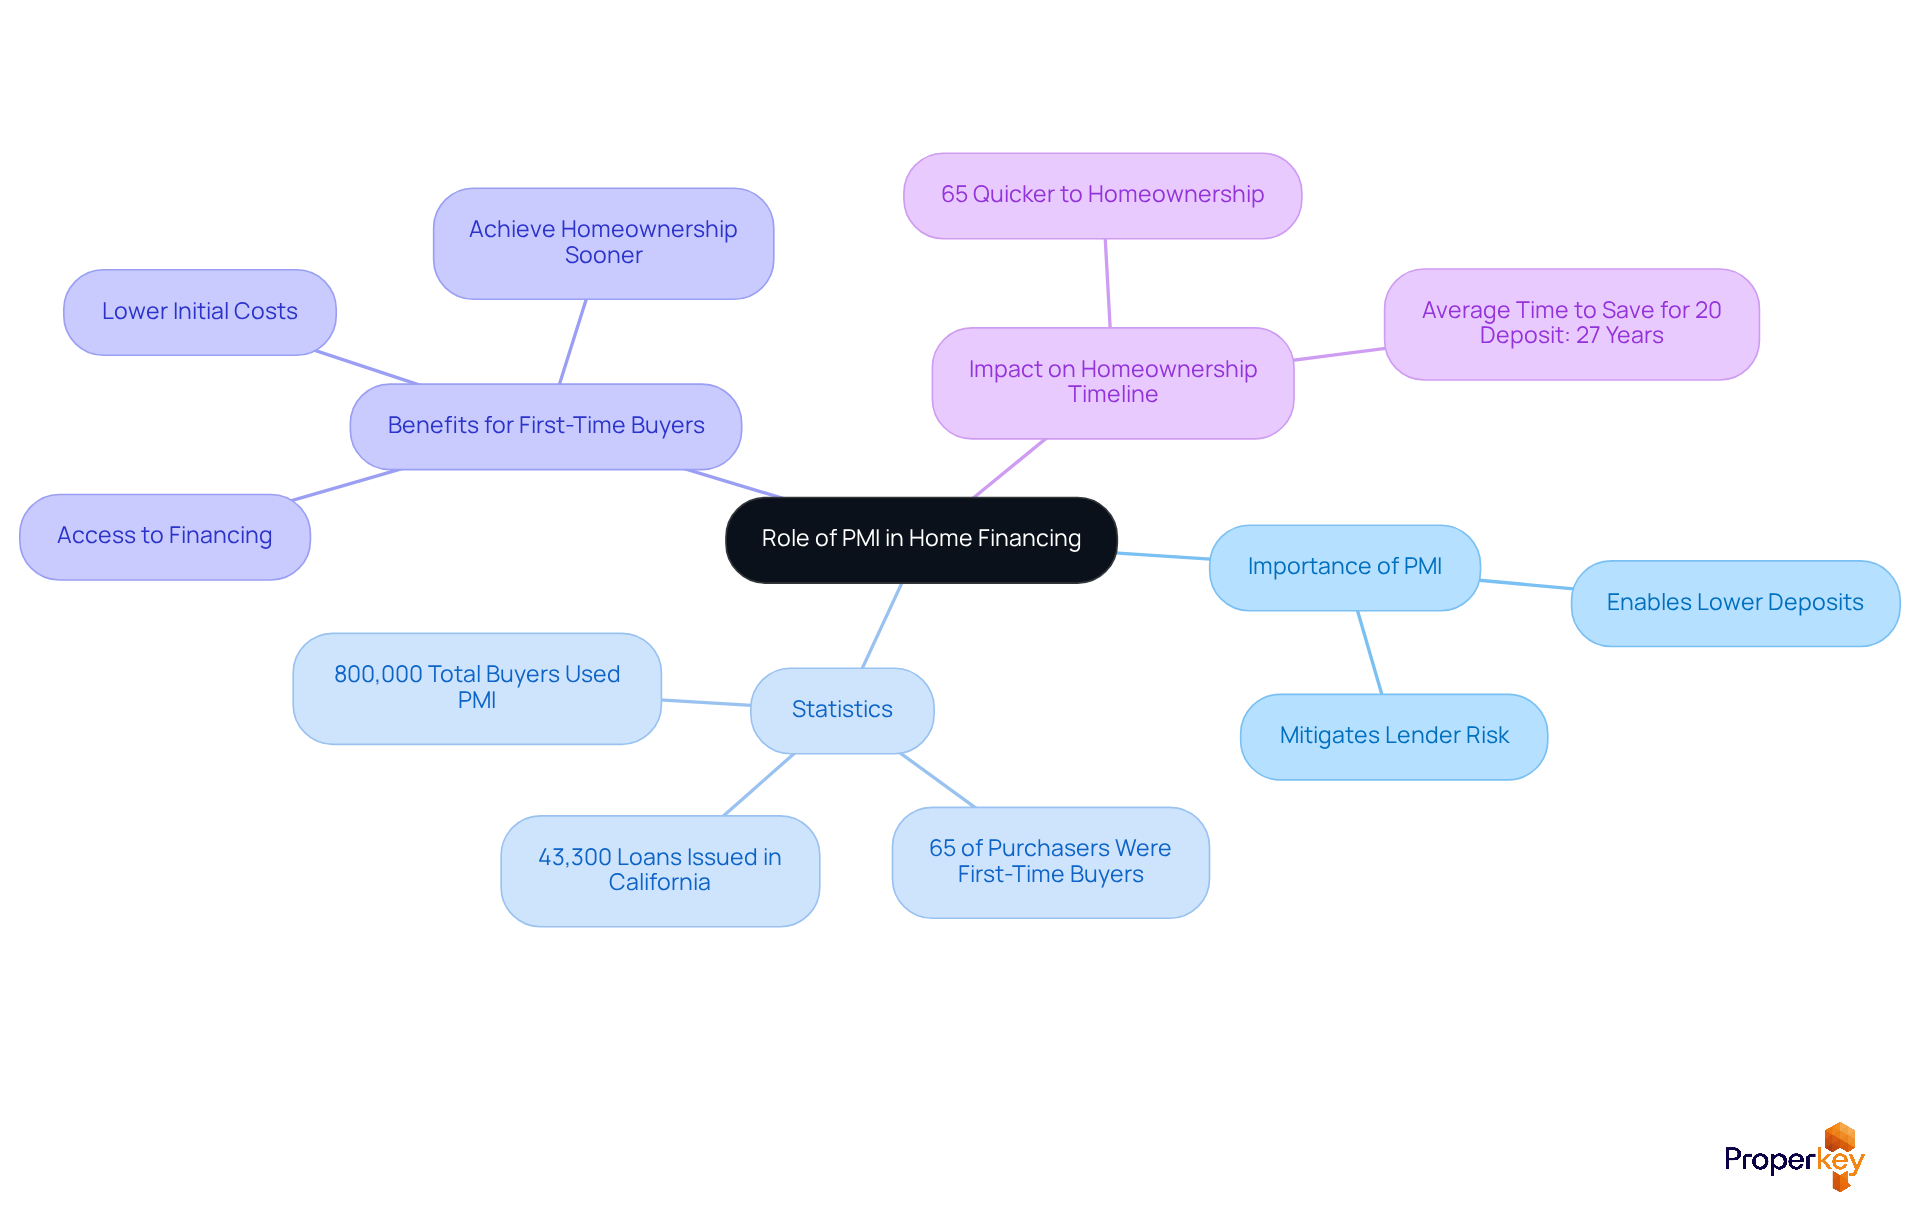
Navigating the complexities of home financing can be daunting, especially when it comes to understanding Private Mortgage Insurance (PMI). PMI protects lenders against default, meaning if a borrower fails to meet their obligations, the lender is compensated for their losses. Typically, PMI is included in the monthly mortgage charge, which increases the overall cost of homeownership. Unlike homeowner's insurance, which protects your property, PMI is designed to safeguard the lender's investment.
In California, a staggering 43,000 homebuyers turned to PMI in 2023, with 72% of them being first-time buyers eager to enter the market. This trend highlights the increasing dependence on PMI to enable homeownership, particularly in a competitive market where initial costs can be a significant obstacle. For instance, an individual with a 10% deposit on a $500,000 house could anticipate paying around $143 monthly in PMI, demonstrating how this insurance can enhance homeownership accessibility.
The good news? Homeowners can eliminate PMI once their equity rises, whether through property appreciation or by reducing their loan to an 80% loan-to-value (LTV) ratio. This flexibility enables individuals to manage their mortgage expenses effectively over time. By understanding what is PMI on a home loan, homebuyers can make informed decisions that enhance their financial stability.
Understand the Role of PMI in Home Financing
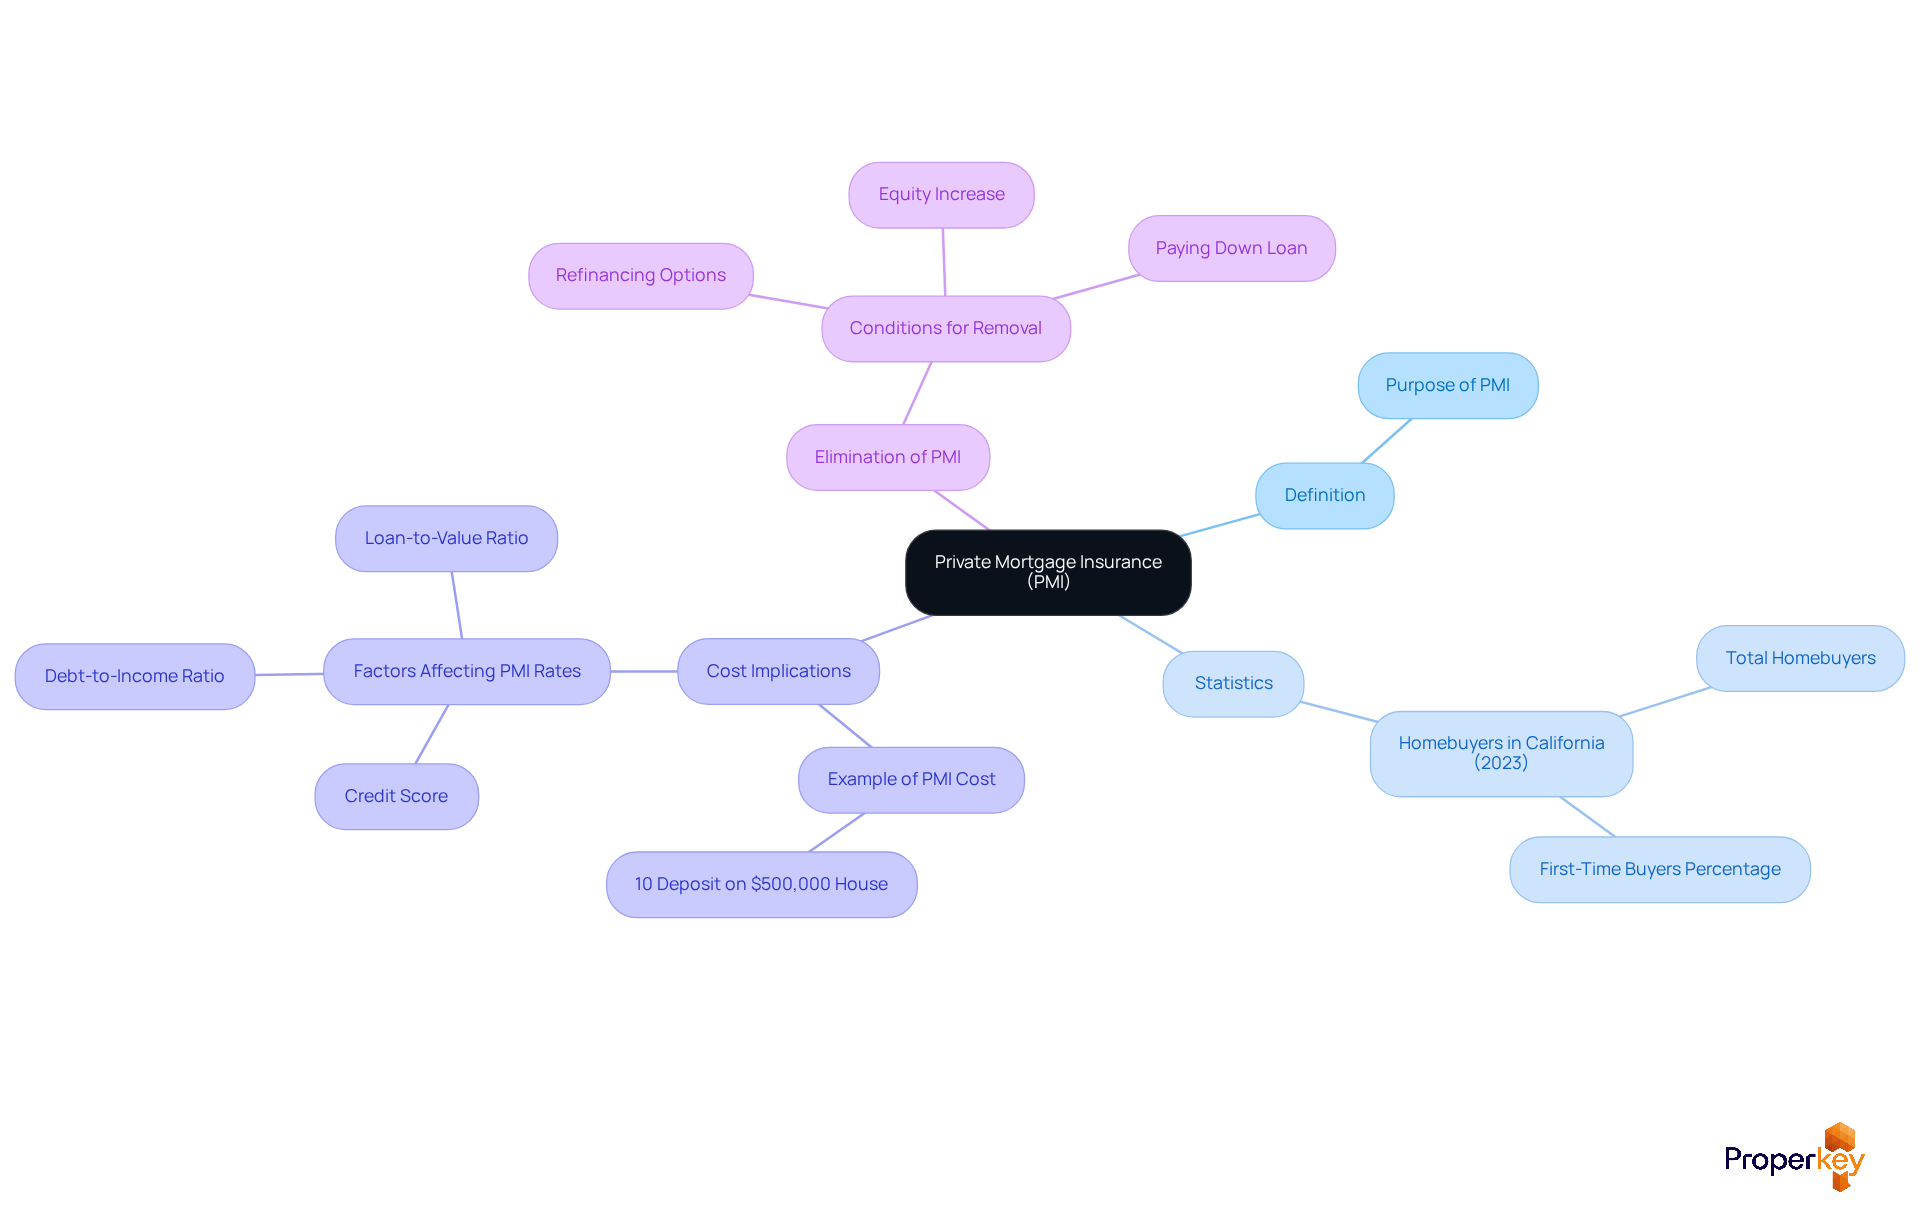
Many first-time buyers struggle to save the substantial 20% deposit required for traditional mortgages, making homeownership seem out of reach. Understanding what is PMI on a home loan is crucial for purchasers as it plays a significant role in home financing. In competitive housing markets like California, Idaho, and Nevada, where prices are on the rise, PMI allows borrowers to secure mortgages with reduced initial costs, often as low as 3%. This insurance mitigates the lender's risk, enabling them to offer loans to those who might otherwise be unable to purchase a home.
In California, about 43,300 loans with PMI were issued in 2024. Notably, 72% of these loans were granted to first-time homebuyers. This trend highlights what is PMI on a home loan and its importance in making homeownership accessible. It allows buyers to enter the market sooner and start building equity-rather than waiting years to save a larger deposit. In fact, knowing what is PMI on a home loan can enable a household to become homeowners 65% quicker compared to saving for a 20% deposit, which could take an average of 27 years.
In understanding what is PMI on a home loan, it's important to note that these charges usually appear in the borrower's monthly mortgage payments. Once the loan-to-value (LTV) ratio hits 78-80%, borrowers can request cancellation. This feature not only helps manage initial costs but also provides a pathway to lower long-term payments as equity builds. In 2024, PMI companies assisted nearly 800,000 purchasers, with first-time homeowners constituting 65% of that total, highlighting what is PMI on a home loan and its significant influence on enabling homeownership.
By leveraging PMI, first-time buyers can not only achieve homeownership sooner but also contribute to a more stable housing market.
Trace the Origins and Evolution of PMI
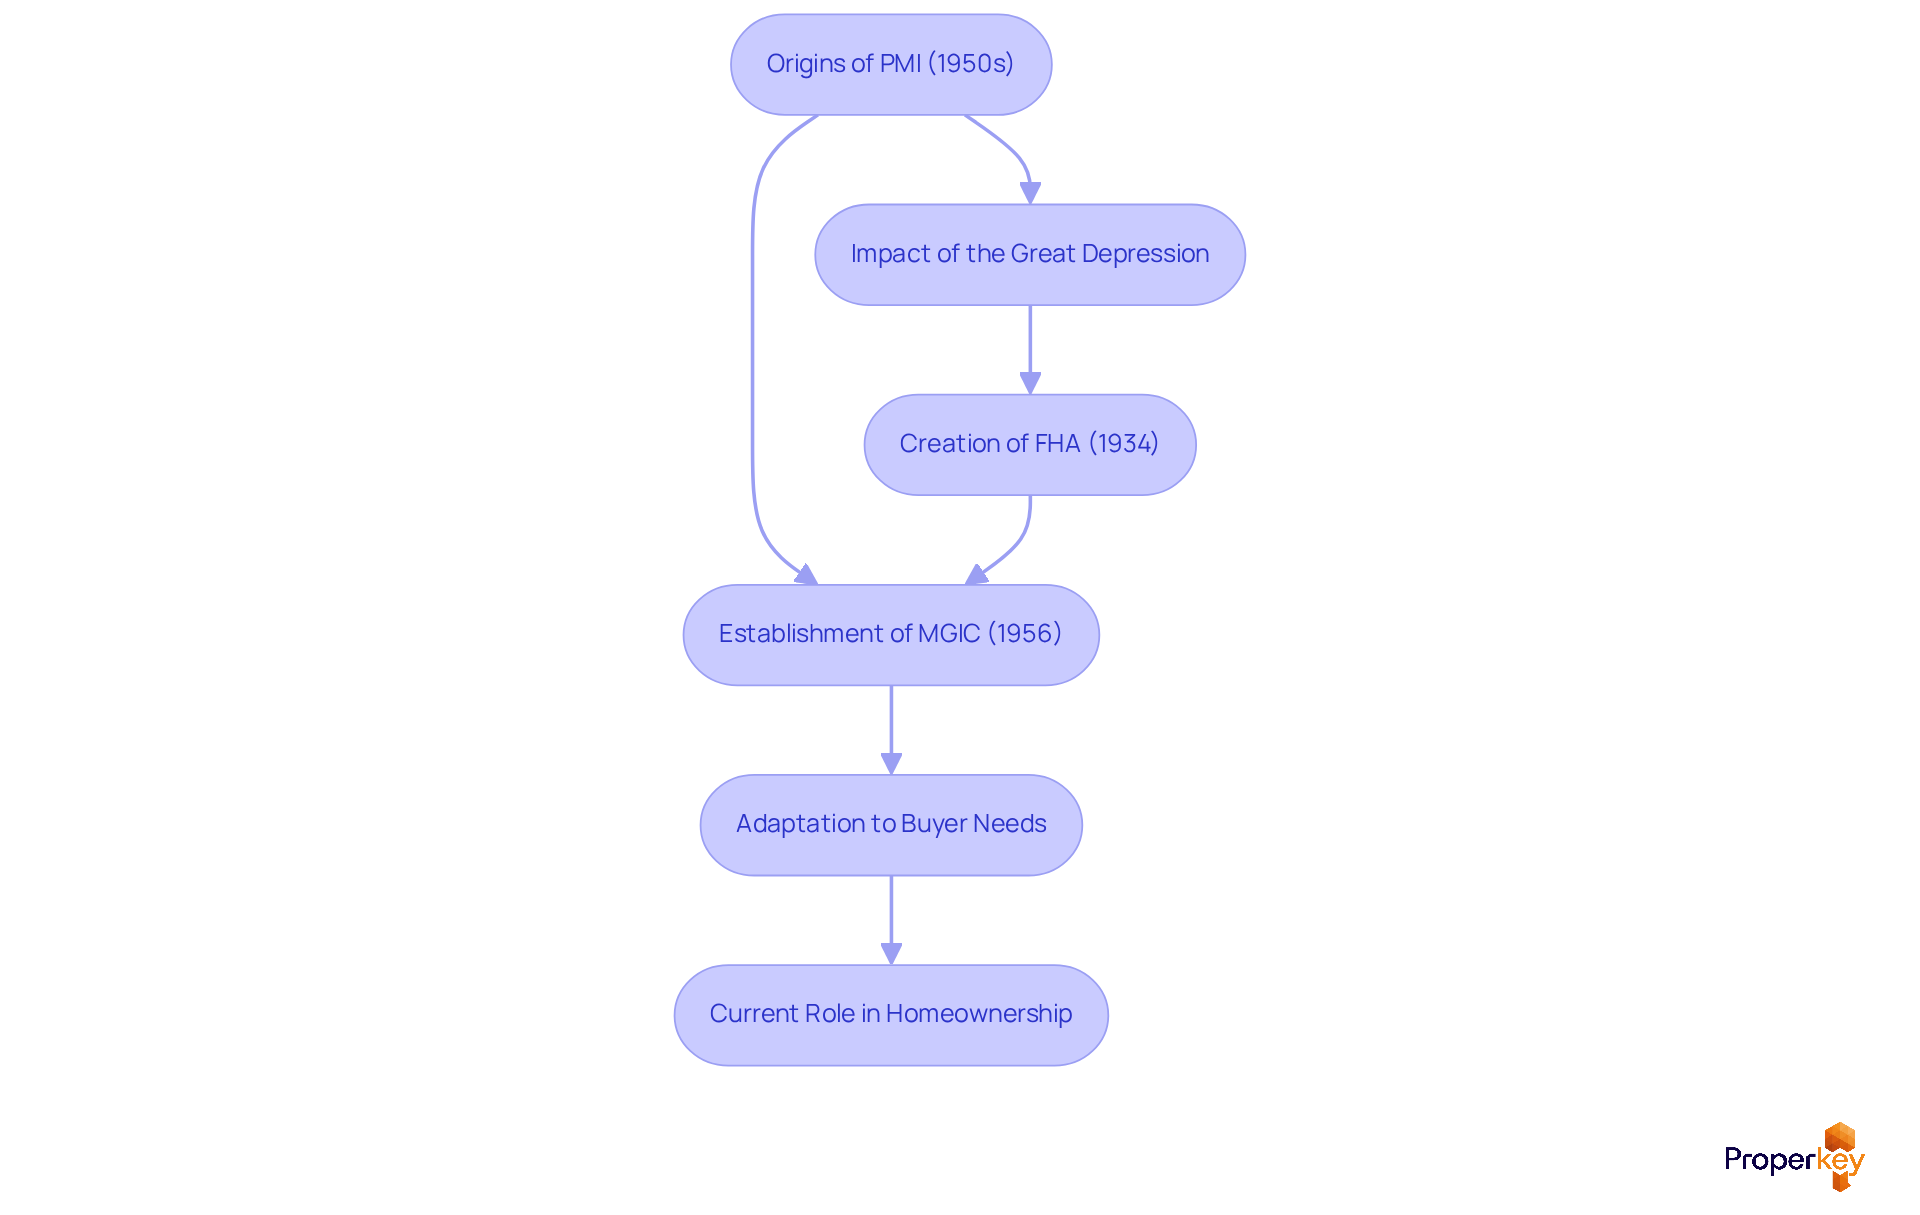
Navigating the complexities of home financing can be daunting, especially when trying to grasp [what is PMI on a home loan](https://mortgageprofessor.com/A - PMI/A Brief History of Mortgage Insurance.html). The concept of PMI emerged in the United States during the 1950s, primarily to safeguard lenders against defaults by individuals. The establishment of the Mortgage Guaranty Insurance Corporation (MGIC) in 1956 marked a pivotal moment in the industry, laying the groundwork for PMI's evolution. What started as a niche product, what is PMI on a home loan has now become essential for many traditional loans, making homeownership more accessible to a diverse range of buyers.
Over the decades, PMI has adapted to the evolving needs of buyers and lending practices, becoming an integral part of the mortgage landscape. For instance, in 2025, homebuyers in states like Florida and Texas ranked among the top users of PMI, with Florida homebuyers saving an average of $66,000 at closing. This trend highlights PMI's role in promoting homeownership, especially for first-time purchasers and those with limited down payment options. Many aspiring homeowners might find their dreams of owning a home slipping away if they do not know what is PMI on a home loan.
Historically, the evolution of PMI can be traced back to the Great Depression, which prompted significant changes in the housing finance system. The Federal Housing Administration (FHA) was created in 1934 to encourage mortgage lending after the market collapse, and by the post-World War II era, confidence in FHA-backed loans had returned, paving the way for private mortgage insurance to re-emerge.
In California, the historical context of PMI is particularly relevant, as the state has seen significant fluctuations in the housing market. The Alger Report of 1934 highlighted the practices of title and mortgage guaranty corporations, emphasizing the need for a robust insurance framework to protect lenders and consumers alike. As PMI, which is what is PMI on a home loan, continues to play a crucial role in the housing market, it enables millions of Americans to achieve their homeownership dreams, making it a vital component of real estate transactions today.
To make the home buying process easier, Properkey provides a full-service platform with local agents, financing options, and escrow services. This ensures a seamless transition from searching for a home to closing the deal. Additionally, Loanvana's innovative financing tool allows buyers to apply once and compare hundreds of loan options side-by-side from multiple lenders, simplifying the financing process and helping buyers secure the best rates.
Explore Key Characteristics and Types of PMI
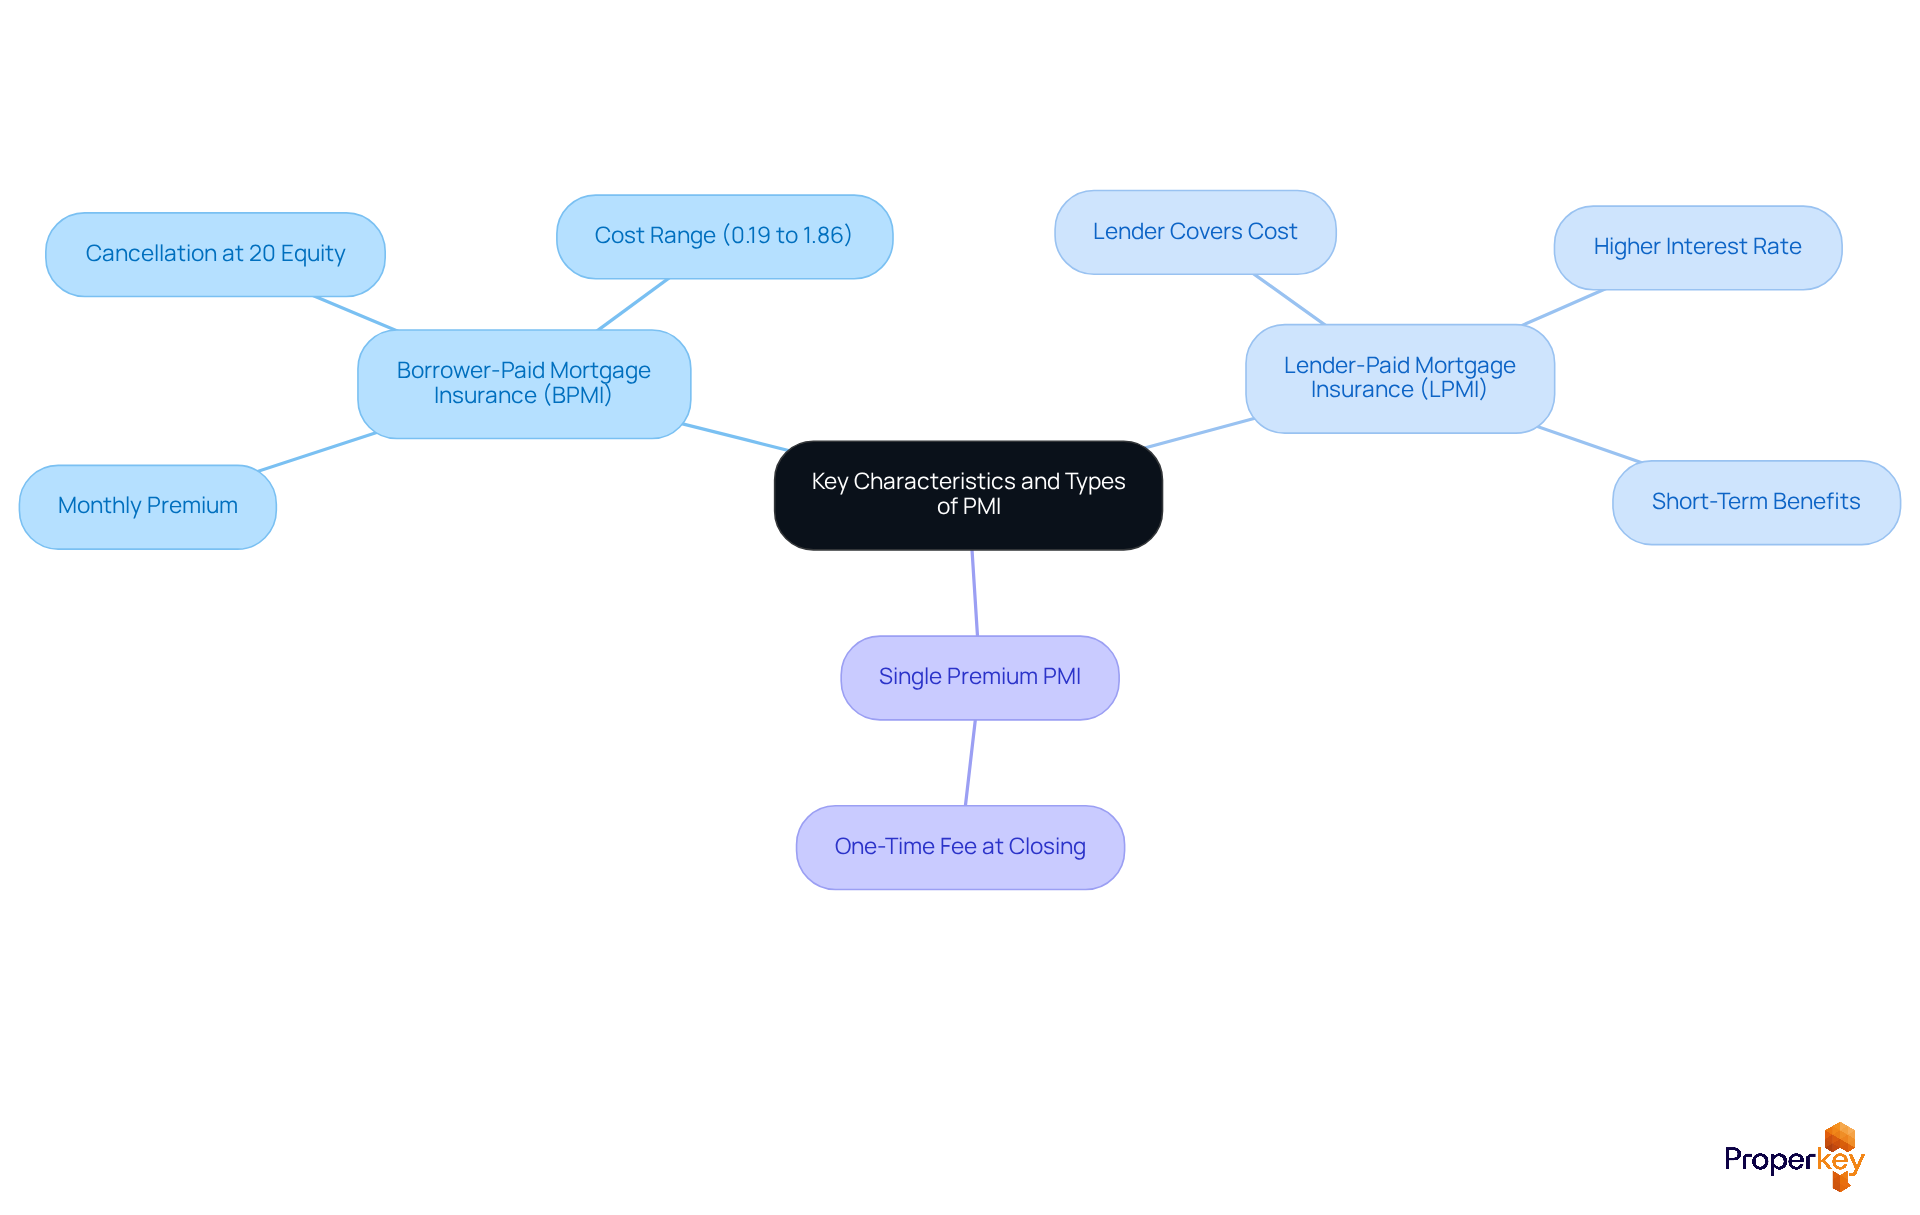
Understanding what is PMI on a home loan is crucial for home sellers in California, Idaho, and Nevada, as making the wrong choice can lead to significant financial repercussions. PMI comes in several types, each impacting home sellers in California, Idaho, and Nevada differently. The most common type is Borrower-Paid Mortgage Insurance (BPMI), where you pay a monthly premium as part of your mortgage payment. You can cancel BPMI once you reach 20% equity in your home, which helps lower your monthly expenses. Did you know PMI costs can range from 0.19% to 1.86% of your mortgage balance? Understanding these figures is vital for budgeting.
On the other hand, Lender-Paid Mortgage Insurance (LPMI) has the lender covering the PMI cost, which usually means a slightly higher interest rate for you. This option can be beneficial if you plan to refinance or sell your home within a few years, as it eliminates monthly PMI payments. However, it may lead to higher overall costs if you hold the mortgage long-term.
To grasp the importance of PMI in your mortgage, it's essential to understand what is PMI on a home loan, as it acts as a safety net for lenders, ensuring they’re protected if a borrower defaults. You can also opt for a single premium PMI, paying a one-time fee at closing. Understanding these options is crucial, as your choice of PMI can significantly impact your monthly expenses and overall loan costs.
In California, Idaho, and Nevada, choosing between BPMI and LPMI depends on your financial situation, credit score, and long-term homeownership plans. It’s essential to evaluate your options carefully. Choosing the wrong PMI type could lead to unnecessary expenses that burden your financial future.
Examine Real-Life Examples of PMI in Home Loans
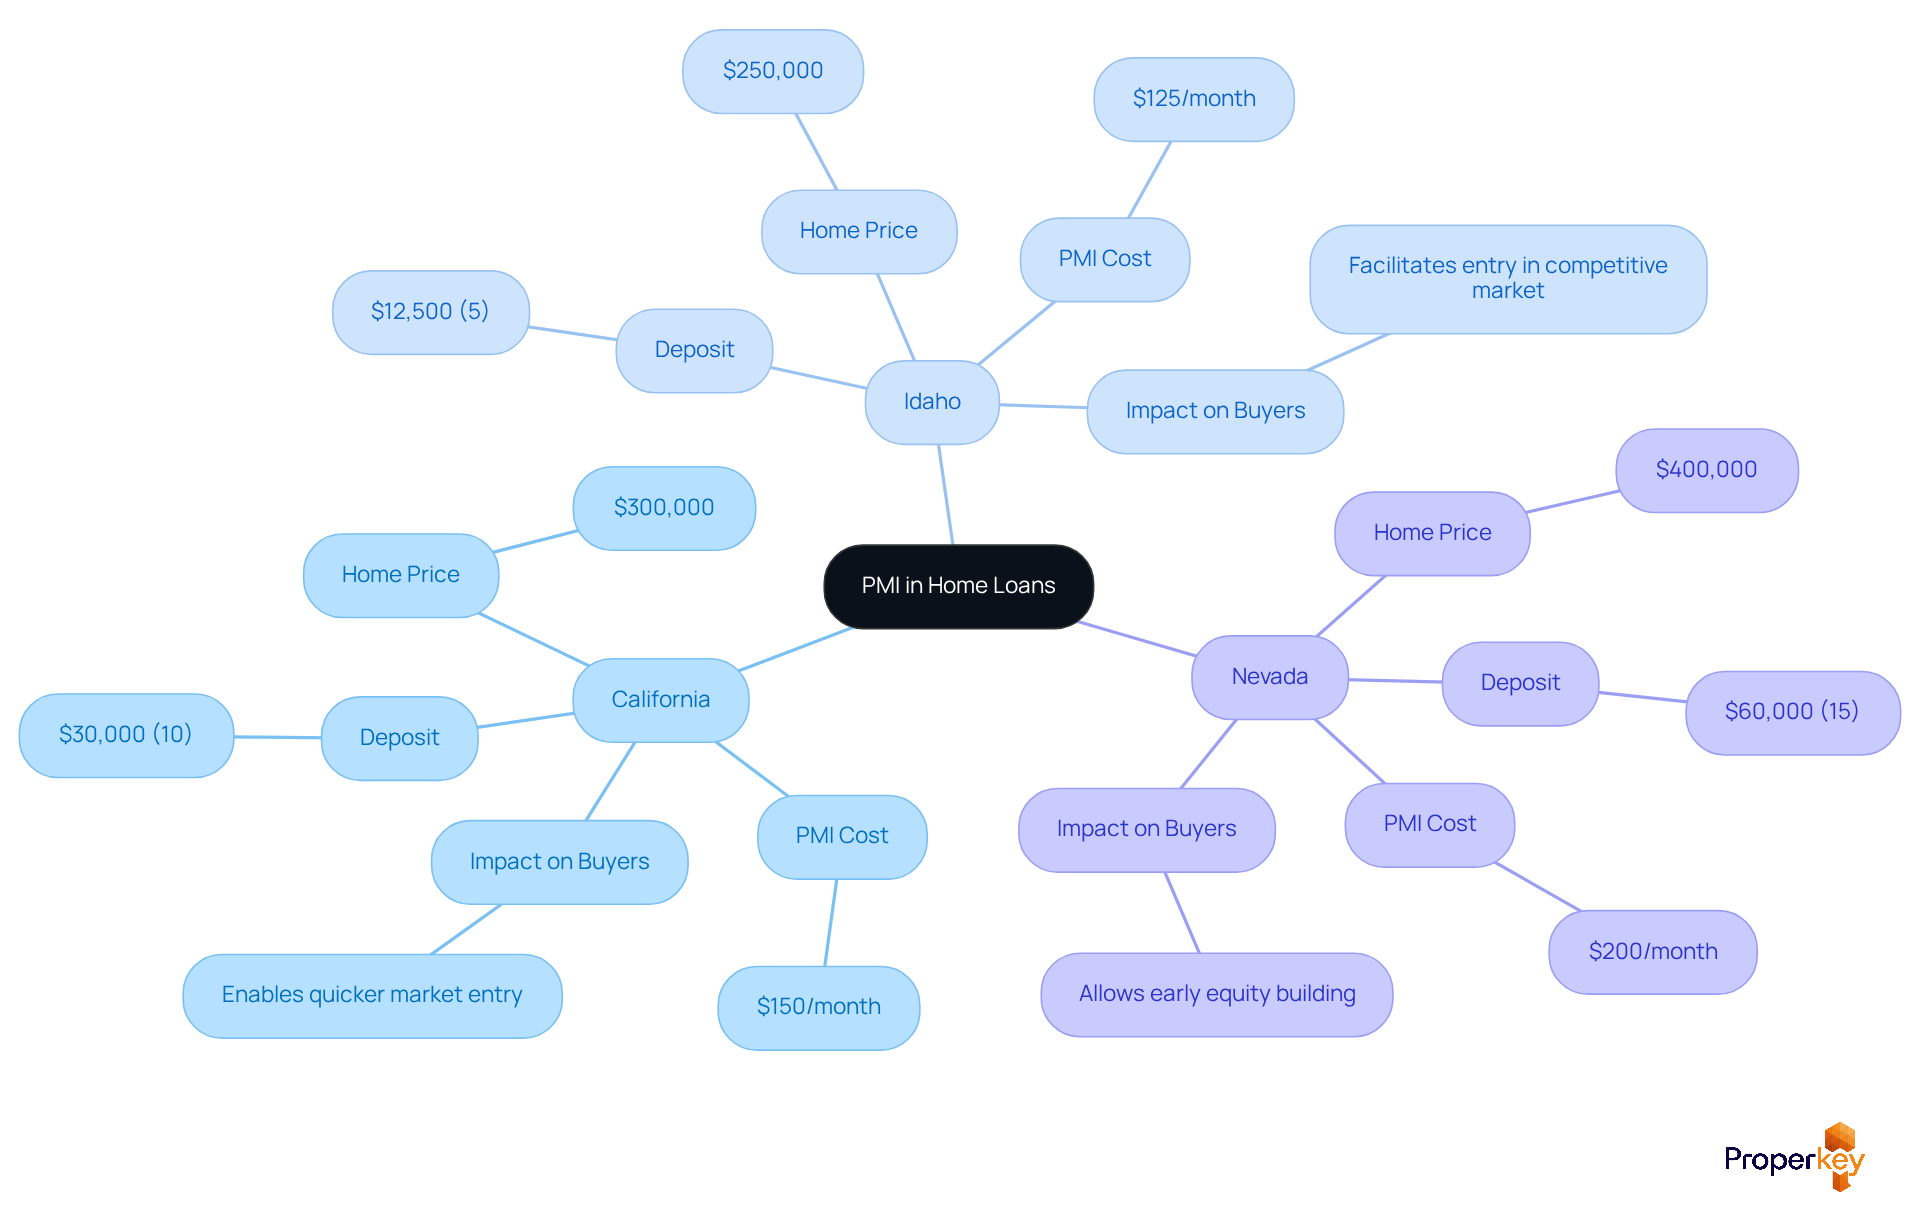
Navigating the complexities of home financing can be daunting for first-time buyers, especially when it comes to understanding Private Mortgage Insurance (PMI). Consider a first-time homebuyer in California acquiring a $300,000 house with a 10% deposit of $30,000. Since the initial deposit is less than 20%, the lender requires PMI. In this case, PMI might add about $150 to the monthly mortgage payment. While this raises the total expense, it helps buyers jump into the market quickly instead of waiting to save for a larger deposit. To explore financing options, purchasers can utilize Loanvana's financing tool, which allows them to apply once and compare hundreds of loan options side-by-side from multiple lenders.
In Idaho, a comparable scenario occurs for an individual considering a $250,000 house with a 5% deposit of $12,500. Here, PMI might increase the monthly charge by approximately $125. This added cost helps buyers jump into the market quickly, which is vital in a competitive setting where home prices are increasing.
In Nevada, an individual acquiring a $400,000 home with a 15% deposit of $60,000 would also encounter PMI requirements. The additional cost of what is PMI on a home loan could add approximately $200 to their monthly mortgage payment. Although this increases their monthly budget, it provides the opportunity to start building equity in their new home sooner.
Consider these examples: PMI can be a game-changer for first-time homeowners in California, Idaho, and Nevada, despite its effect on monthly budgets and long-term financial planning. Furthermore, homeowners can request PMI cancellation once their loan-to-value (LTV) ratio reaches 80%, or it will be automatically terminated at 78% LTV according to CFPB guidelines. By understanding these costs and the potential for cancellation, buyers can make informed decisions that align with their financial goals. By leveraging tools like Loanvana, buyers can not only navigate these costs but also position themselves for long-term financial success.
Conclusion
Navigating the complexities of Private Mortgage Insurance (PMI) is crucial for anyone looking to secure a home loan. PMI acts as a vital safety net for lenders. It enables borrowers to secure mortgages with lower down payments, making homeownership more accessible. By mastering PMI, potential homeowners can make informed decisions that align with their financial goals.
Key insights include:
- The historical context of PMI
- Various types of PMI
- Impact on homebuyers in California, Idaho, and Nevada
Statistics reveal that a significant portion of PMI users are first-time buyers, underscoring its importance in facilitating quicker access to homeownership. Additionally, understanding the nuances between Borrower-Paid Mortgage Insurance (BPMI) and Lender-Paid Mortgage Insurance (LPMI) can significantly influence a buyer's financial trajectory.
Ultimately, PMI is more than just an added cost; it’s a gateway for many to enter the housing market sooner and begin building equity. As the housing landscape continues to evolve, staying informed about PMI and its implications can empower buyers to navigate their home financing journey with confidence. With the right knowledge, the dream of homeownership is not just a possibility; it can become a reality sooner than you think.
Frequently Asked Questions
What is Private Mortgage Insurance (PMI)?
Private Mortgage Insurance (PMI) is insurance that protects lenders against default, compensating them for losses if a borrower fails to meet their mortgage obligations. It is typically included in the monthly mortgage charge.
How does PMI differ from homeowner's insurance?
PMI safeguards the lender's investment in the event of borrower default, while homeowner's insurance protects the property itself from damages or losses.
Why do many homebuyers in California use PMI?
Many homebuyers in California use PMI because it allows them to secure mortgages with lower initial costs, often as low as a 3% deposit, making homeownership more accessible, especially for first-time buyers.
What percentage of homebuyers using PMI in California are first-time buyers?
In California, approximately 72% of homebuyers who used PMI in 2023 were first-time buyers.
How can PMI help homebuyers enter the market sooner?
PMI enables homebuyers to purchase homes with smaller down payments, allowing them to start building equity sooner rather than waiting years to save for a larger deposit.
When can homeowners eliminate PMI?
Homeowners can eliminate PMI once their equity increases, either through property appreciation or by reducing their loan to an 80% loan-to-value (LTV) ratio.
How does PMI impact monthly mortgage payments?
PMI typically appears as an additional charge in the borrower's monthly mortgage payments, increasing the overall cost of homeownership.
What is the significance of PMI in the housing market?
PMI plays a significant role in making homeownership accessible, allowing first-time buyers to achieve homeownership 65% quicker compared to saving for a 20% deposit, thus contributing to a more stable housing market.
List of Sources
- Define PMI: What It Means in Home Loans
- PMI By the Numbers Archives - USMI (https://usmi.org/filter_data/pmi-by-the-numbers)
- PMI Calculator - NerdWallet (https://nerdwallet.com/mortgages/calculators/pmi)
- Certain PMI Requirements Waived for State-Chartered CUs - California's Credit Unions and Nevada's Credit Unions (https://californiascreditunions.org/news/certain-pmi-requirements-waived-for-state-cus-dfpi-issues-order)
- Press Release: Californians Used Private Mortgage Insurance to Purchase Homes in a Challenging Real Estate Market - USMI (https://usmi.org/press-release-californians-used-private-mortgage-insurance-to-purchase-homes-in-a-challenging-real-estate-market)
- A Guide To Private Mortgage Insurance In California And Texas - JVM Lending (https://jvmlending.com/blog/private-mortgage-insurance-guide-california-texas)
- Understand the Role of PMI in Home Financing
- First-Time Homebuyer 101: Everything You Need to Know About PMI (https://myfirstoption.com/blog/101-pmi)
- Mostly First-Timers Benefit from PMI (https://nationalmortgageprofessional.com/news/mostly-first-timers-benefit-pmi)
- Private Mortgage Insurance: The Tool Helping Millions of Americans Buy Homes Sooner - USMI (https://usmi.org/private-mortgage-insurance-the-tool-helping-millions-of-americans-buy-homes-sooner)
- PMI By the Numbers Archives - USMI (https://usmi.org/filter_data/pmi-by-the-numbers)
- Trace the Origins and Evolution of PMI
- A Brief History of Mortgage Insurance - Mortgage Professor (https://mortgageprofessor.com/A - PMI/A Brief History of Mortgage Insurance.html)
- PMI By the Numbers Archives - USMI (https://usmi.org/filter_data/pmi-by-the-numbers)
- Explore Key Characteristics and Types of PMI
- Lender-Paid vs. Borrower-Paid PMI: Making the Right Choice in West Palm Beach - Premier Mortgage Associates (https://premiermtg.com/lender-paid-vs-borrower-paid-pmi-making-the-right-choice-in-west-palm-beach)
- Borrower-Paid vs Lender-Paid PMI: What's the Difference? (https://719lending.com/borrower-paid-vs-lender-paid-pmi)
- Private Mortgage Insurance (PMI) vs. Lender-Paid PMI: Which Saves More Money Over Time? (https://realtor.com/advice/buy/private-mortgage-insurance-pmi-vs-lender-paid-pmi-comparison)
- Lender-Paid Mortgage Insurance (LPMI): What It Is, How It Works & Whether It’s Worth It (https://redfin.com/blog/lender-paid-mortgage-insurance)
- How much is PMI (private mortgage insurance)? (https://mymortgageinsider.com/how-much-is-pmi-private-mortgage-insurance)
- Examine Real-Life Examples of PMI in Home Loans
- A Guide To Private Mortgage Insurance In California And Texas - JVM Lending (https://jvmlending.com/blog/private-mortgage-insurance-guide-california-texas)
- Press Release: California Ranks 3rd in Low Down Payment Homebuyers Using Private Mortgage Insurance in 2024 - USMI (https://usmi.org/press-release-california-ranks-3rd-in-low-down-payment-homebuyers-using-private-mortgage-insurance-in-2024)
- Mostly First-Timers Benefit from PMI (https://nationalmortgageprofessional.com/news/mostly-first-timers-benefit-pmi)
- Making Homeownership More Affordable: New Report Finds Private Mortgage Insurance Saved Homebuyers an Estimated $48,000 in Closing Costs in 2025 - USMI (https://usmi.org/making-homeownership-more-affordable-new-report-finds-private-mortgage-insurance-saved-homebuyers-an-estimated-48000-in-closing-costs-in-2025)
- PMI in 2026: When Private Mortgage Insurance Makes Sense - CUSO Home Lending (https://cusohl.com/pmi-in-2026-guide-maine-nh)