What You Need to Know About FHA Loan Closing Costs Inclusion

Introduction
Many first-time homebuyers are blindsided by the complexities of FHA loan closing costs, which can dramatically affect their financial plans. These costs can dramatically affect home affordability, encompassing various fees that often catch buyers off guard. The question of whether these closing costs can be included in an FHA loan raises critical considerations about budgeting and financial planning.
How can buyers effectively navigate these expenses to pave a smoother path to homeownership?
Define FHA Loan Closing Costs
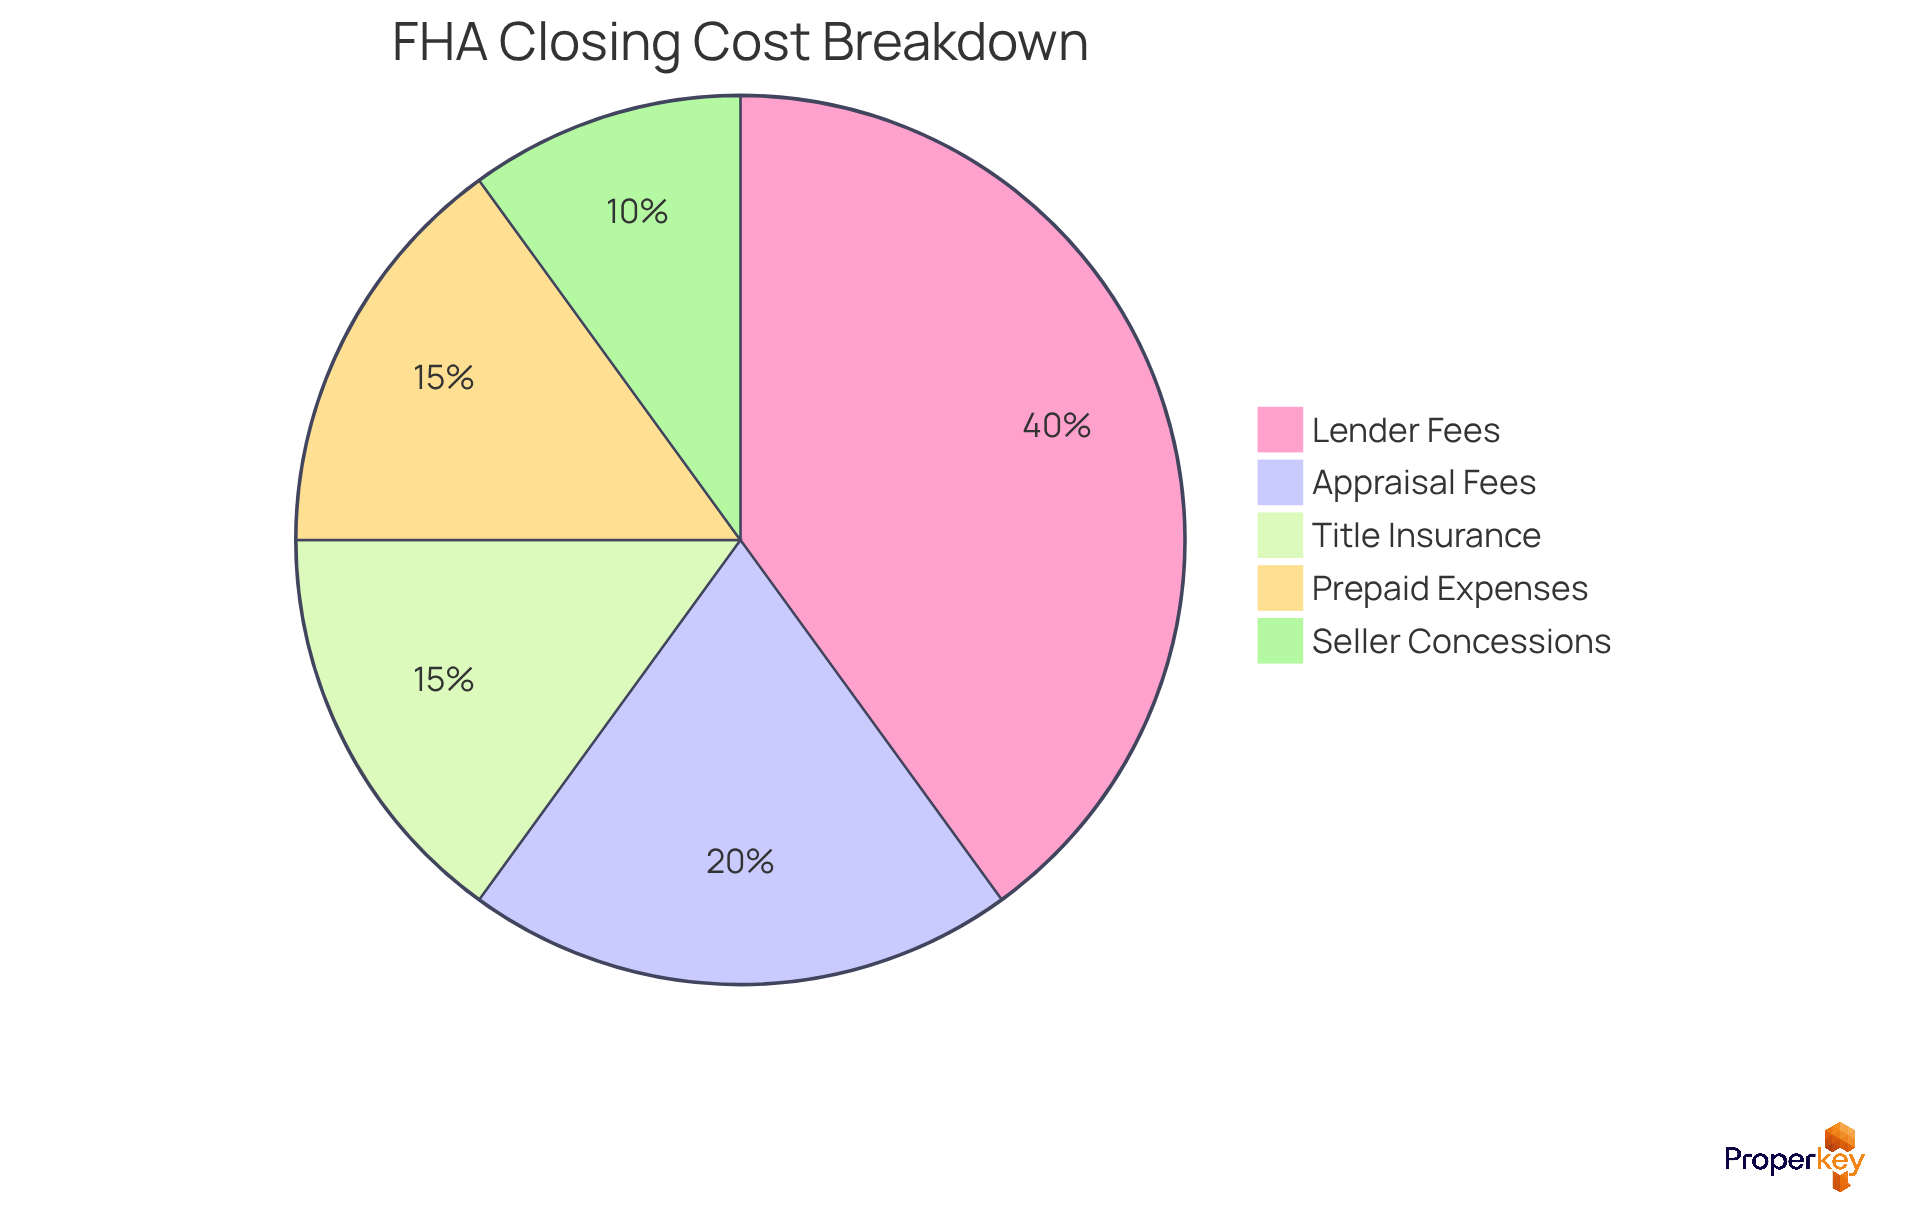
For many first-time buyers, navigating the complexities of FHA loan settlement charges raises the question of whether closing costs can be included in loan FHA. FHA loan settlement charges encompass various fees and expenses. These are costs borrowers must pay when finalizing their mortgage. Typically, these expenses range from 2% to 6% of the home's purchase price, contributing to the down payment. Key components include:
- Lender fees
- Appraisal fees
- Title insurance
- Prepaid expenses such as property taxes and homeowners insurance
For example, on a $400,000 house, final expenses could range from $8,000 to $24,000, depending on several factors.
Understanding these expenses is crucial, particularly for first-time buyers, as they can significantly impact the overall affordability of acquiring a home, especially when considering if closing costs can be included in loan FHA. In 2026, FHA fees are expected to average between $9,000 and $18,000 for a $300,000 loan. This highlights the importance of planning for these costs.
Additionally, buyers can explore ways to lower these costs: seller concessions allow sellers to contribute up to 6% of the home's price toward final expenses, covering lender fees and prepaid charges. This is particularly beneficial in balanced markets where negotiations are more favorable.
Integrating Closevana's efficient coordination of real estate transactions can further aid buyers in handling these expenses effectively. Their 4-Step Protection system for escrow guarantees document verification, funds protection, title clearance, and settlement, offering peace of mind throughout the transaction process.
Consider these case studies from California, Idaho, and Nevada, which illustrate the variability in final expenses: in California, a buyer might encounter higher charges due to state-specific regulations, while in Idaho, expenses may be reduced due to fewer local taxes. Understanding these regional variations empowers buyers to navigate the intricacies of FHA financing with confidence.
Contextualize FHA Closing Costs in Home Financing
For home buyers, understanding FHA fees is essential, particularly regarding whether closing costs can be included in an FHA loan, as these costs can significantly impact their financial planning. FHA fees play a crucial role in home financing, representing necessary expenses that enable property ownership transfer. For low-to-moderate-income borrowers, these expenses are vital. FHA mortgages typically require lower down payments, making them appealing options. However, the addition of final expenses can complicate the financial situation for buyers, especially when considering whether closing costs can be included in an FHA loan. Navigating these unexpected charges can lead to financial stress for buyers, necessitating a thorough understanding to budget effectively and avoid surprises at the end.
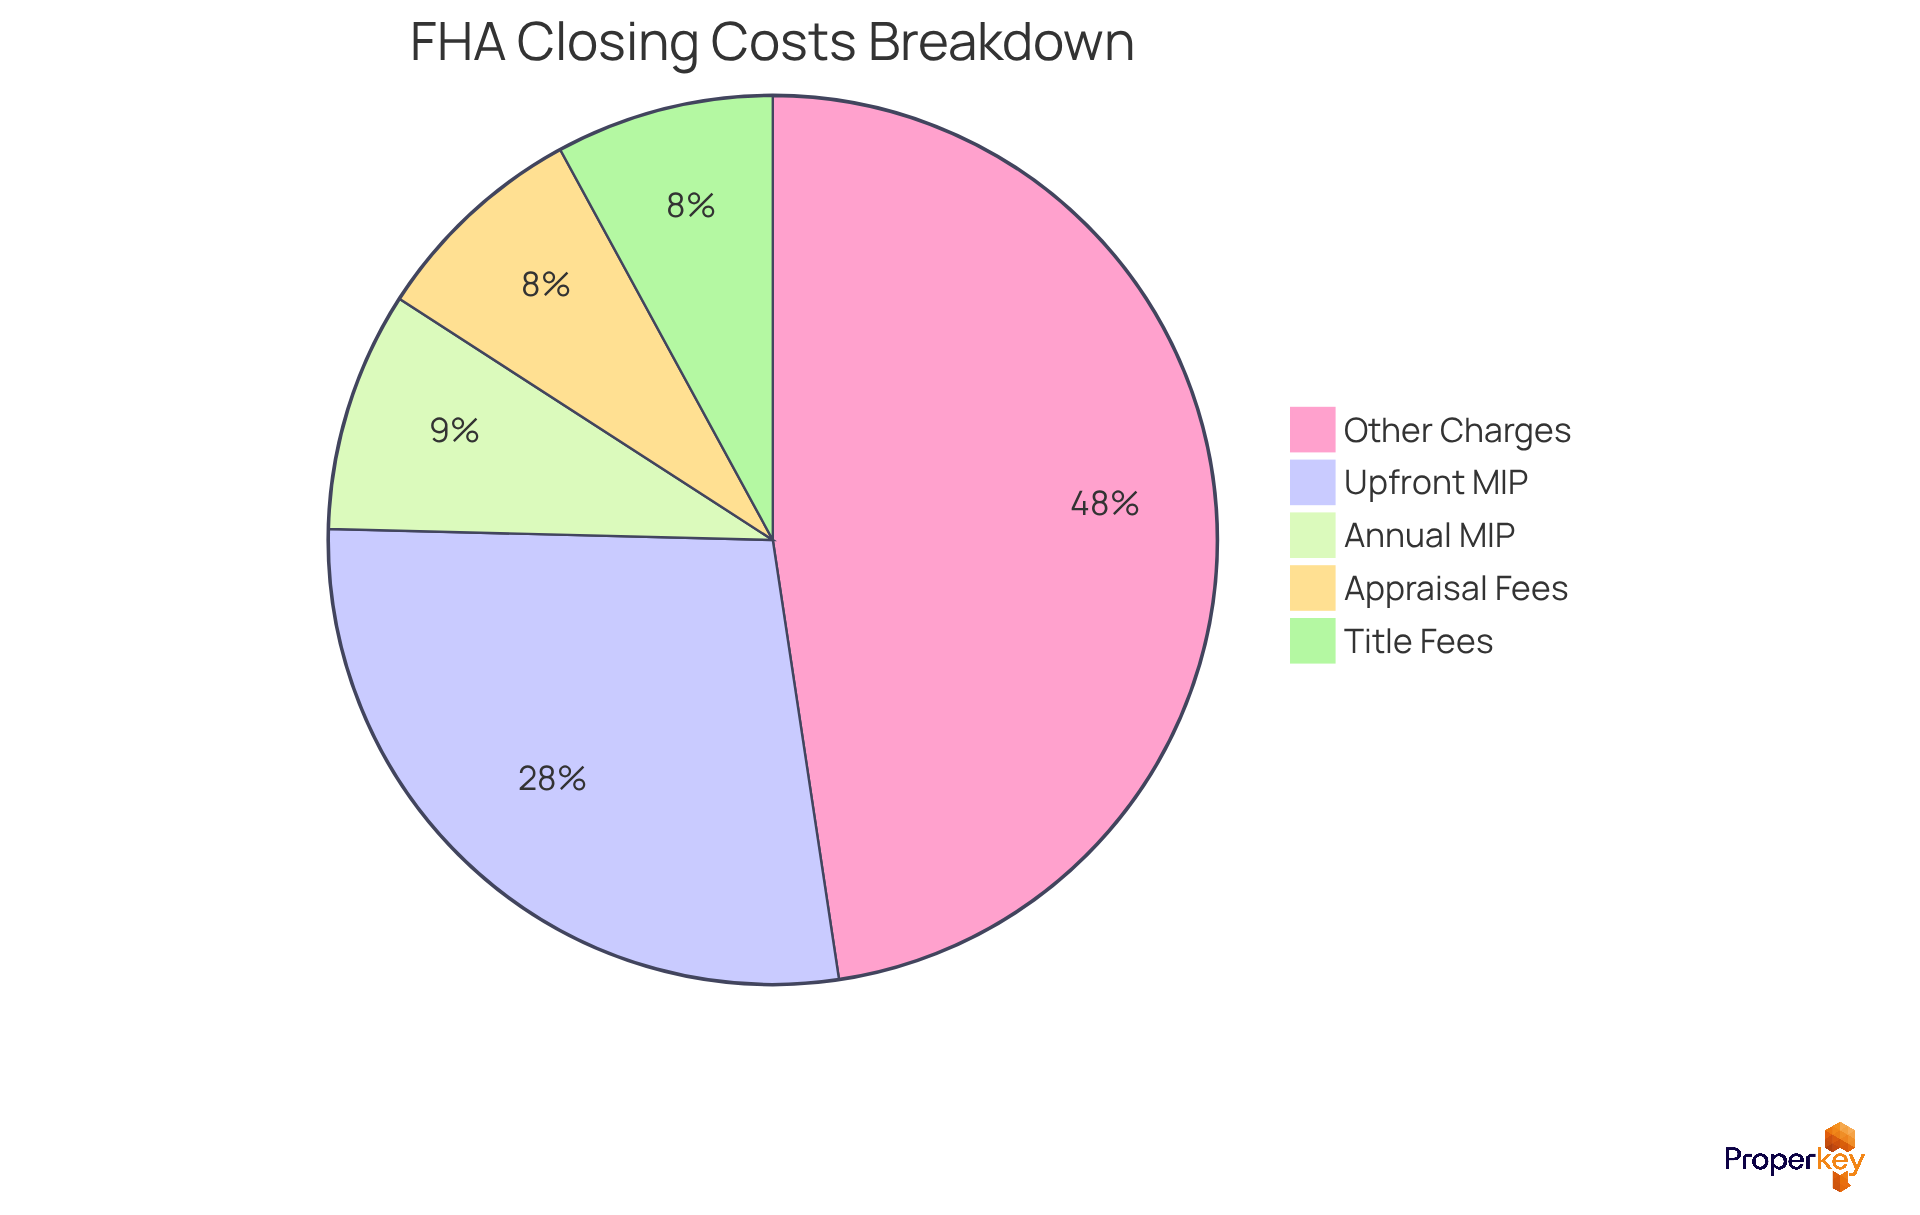
In California, Idaho, and Nevada, FHA final expenses usually vary from 3% to 6% of the mortgage amount. For example, on a $300,000 mortgage, purchasers might encounter closing expenses ranging from $9,000 to $18,000. This range encompasses various fees such as the upfront mortgage insurance premium (MIP), which is 1.75% of the principal amount, and annual MIP, typically around 0.55% of the total amount. Furthermore, third-party charges for services such as appraisals and title searches can contribute substantial expenses, with appraisal fees averaging between $400 and $800 and title fees varying from $500 to $2,000. It's important to keep in mind that the question of whether closing costs can be included in an FHA loan plays a key role in the FHA loan process.
Understanding these expenses is crucial; it allows borrowers to negotiate with sellers for contributions toward those final fees, particularly regarding whether closing costs can be included in an FHA loan. FHA regulations allow sellers to contribute up to 6% of the sales price toward qualifying expenses, which raises the question of how closing costs can be included in an FHA loan to ease some financial strain for buyers. This flexibility can be particularly beneficial in competitive markets, where every dollar counts.
Experts emphasize the importance of reviewing the Loan Estimate, which outlines projected expenses, monthly payments, and the cash required at settlement. As Jake Vehige, President of Mortgage Lending, notes, "Your Loan Estimate is the best place to start." By being aware of FHA fees, borrowers can navigate the home buying process with greater assurance, ensuring a smoother transaction and ultimately making more knowledgeable financial choices. Furthermore, borrowers should be aware that the upfront MIP can often be included in the total amount, offering additional options for managing their financing. By mastering these fees, buyers can not only navigate the complexities of home buying but also secure a more favorable financial future.
Trace the Evolution of FHA Loan Closing Costs
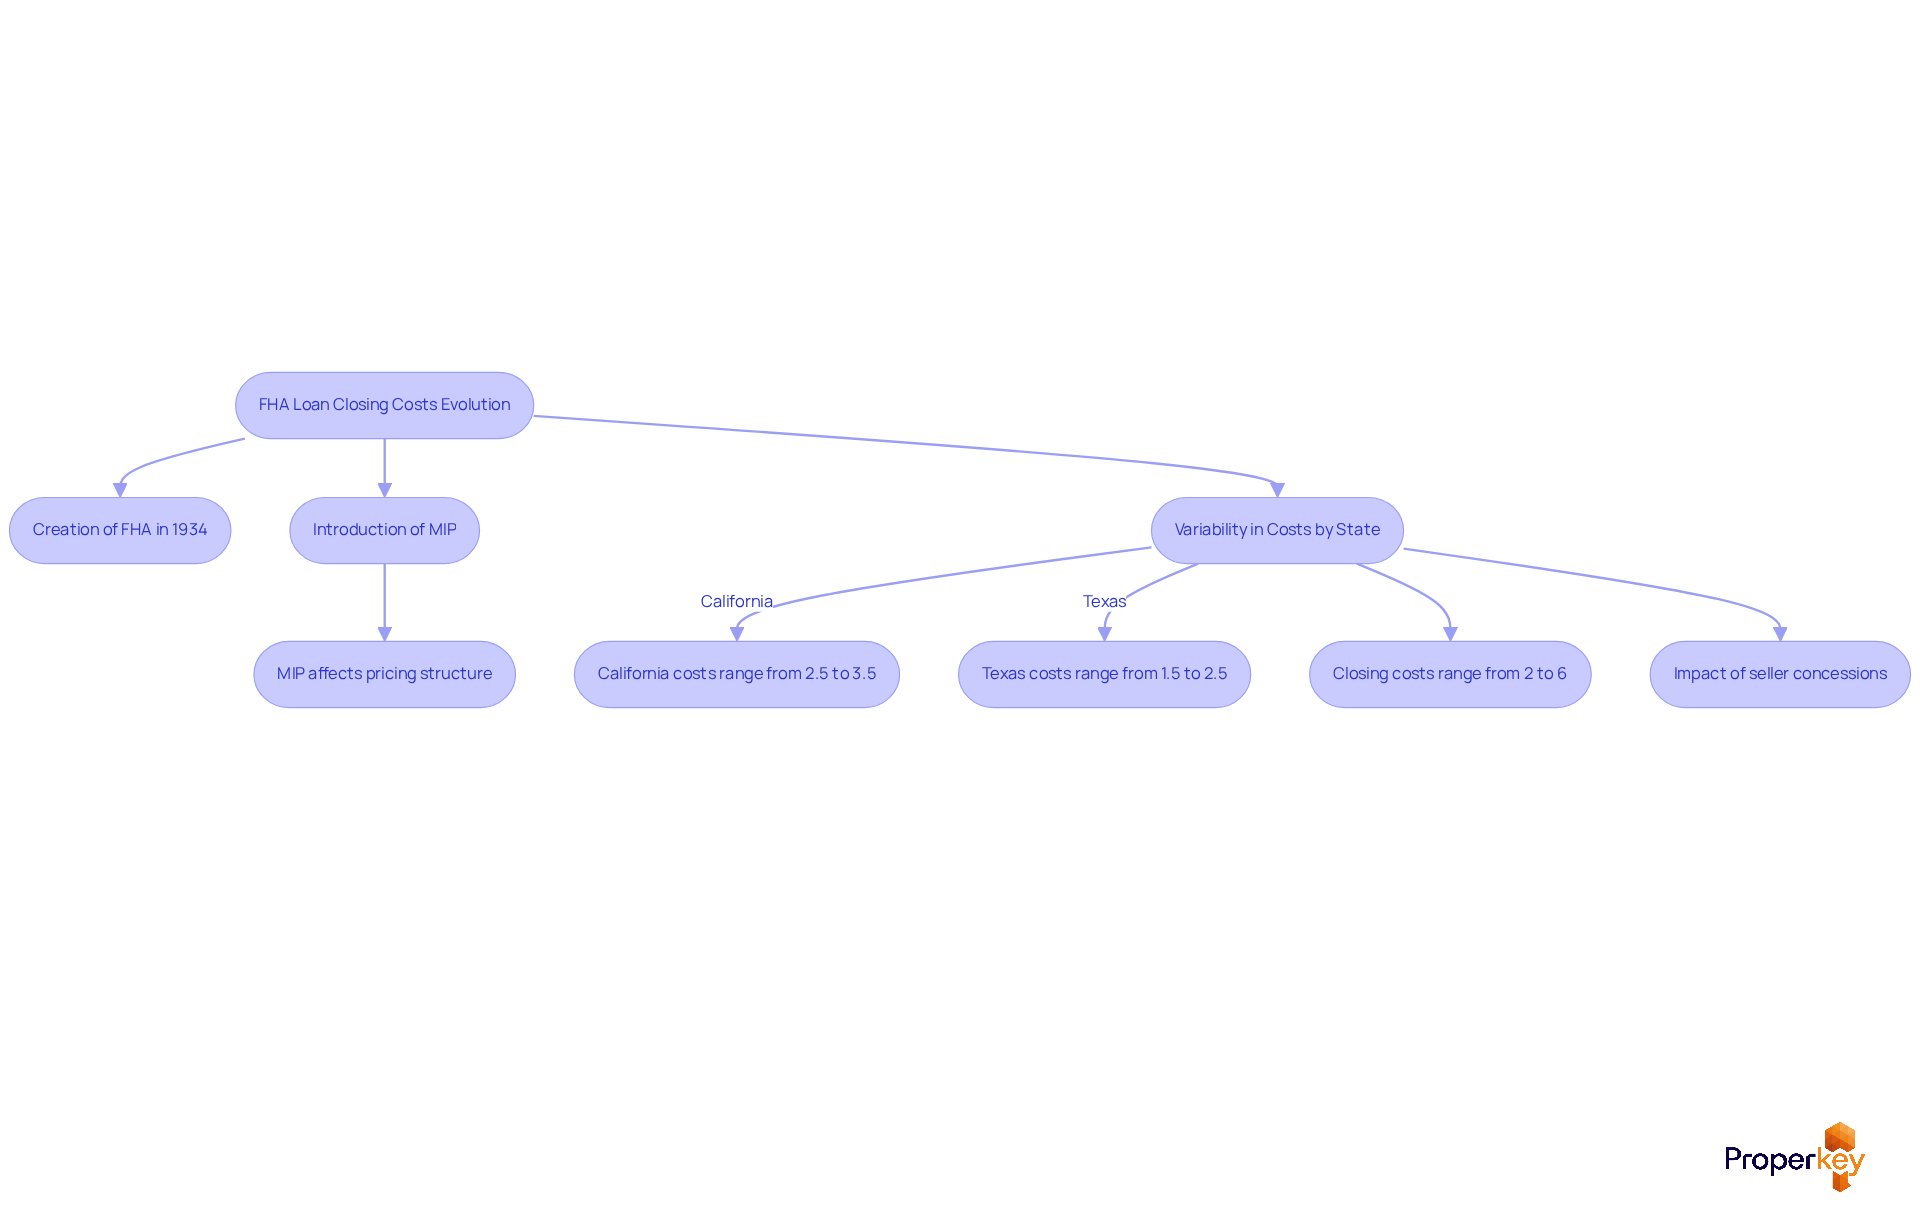
For many borrowers, navigating the maze of FHA mortgage expenses raises the question of whether closing costs can be included in an FHA loan. The development of FHA mortgage closing expenses began with the Federal Housing Administration's creation in 1934, aimed at expanding access to homeownership. Over the decades, these expenses have been shaped by various economic factors, including fluctuations in the housing market and changes in federal regulations. A significant advancement was the introduction of mortgage insurance premiums (MIP), which became a standard part of FHA financing, directly affecting the overall pricing structure. For example, the upfront MIP is currently set at 1.75% of the loan amount, which can be rolled into the mortgage, impacting monthly payments and total debt.
As the housing market evolves, so do the fees associated with final expenses. In California, for instance, these expenses can range from 2.5% to 3.5% of the home's purchase price, reflecting the higher costs of title insurance and recording fees compared to states like Texas, where expenses are lower due to different legal requirements. This variability highlights the need for transparency and affordability in the home buying process, a core principle of Closevana's escrow services that aim to streamline transactions and clarify fee structures.
Understanding this history helps borrowers navigate today’s FHA financing landscape, particularly regarding whether closing costs can be included in an FHA loan. For a $524,225 FHA mortgage, final expenses can range from $10,485 to $31,454, depending on factors like location and lender policies. By recognizing the evolution of these expenses and the role of services like Closevana in ensuring a clear process, borrowers can better understand if closing costs can be included in an FHA loan, allowing them to make informed decisions and prepare for the financial obligations involved in obtaining an FHA mortgage. Understanding these expenses empowers borrowers to make informed decisions and secure their financial future.
Identify Key Components of FHA Closing Costs
Navigating the maze of closing costs can feel daunting for many home buyers, especially when considering if closing costs can be included in an FHA loan, but understanding these key components is essential for a smooth transaction. Key components of FHA closing costs typically include:
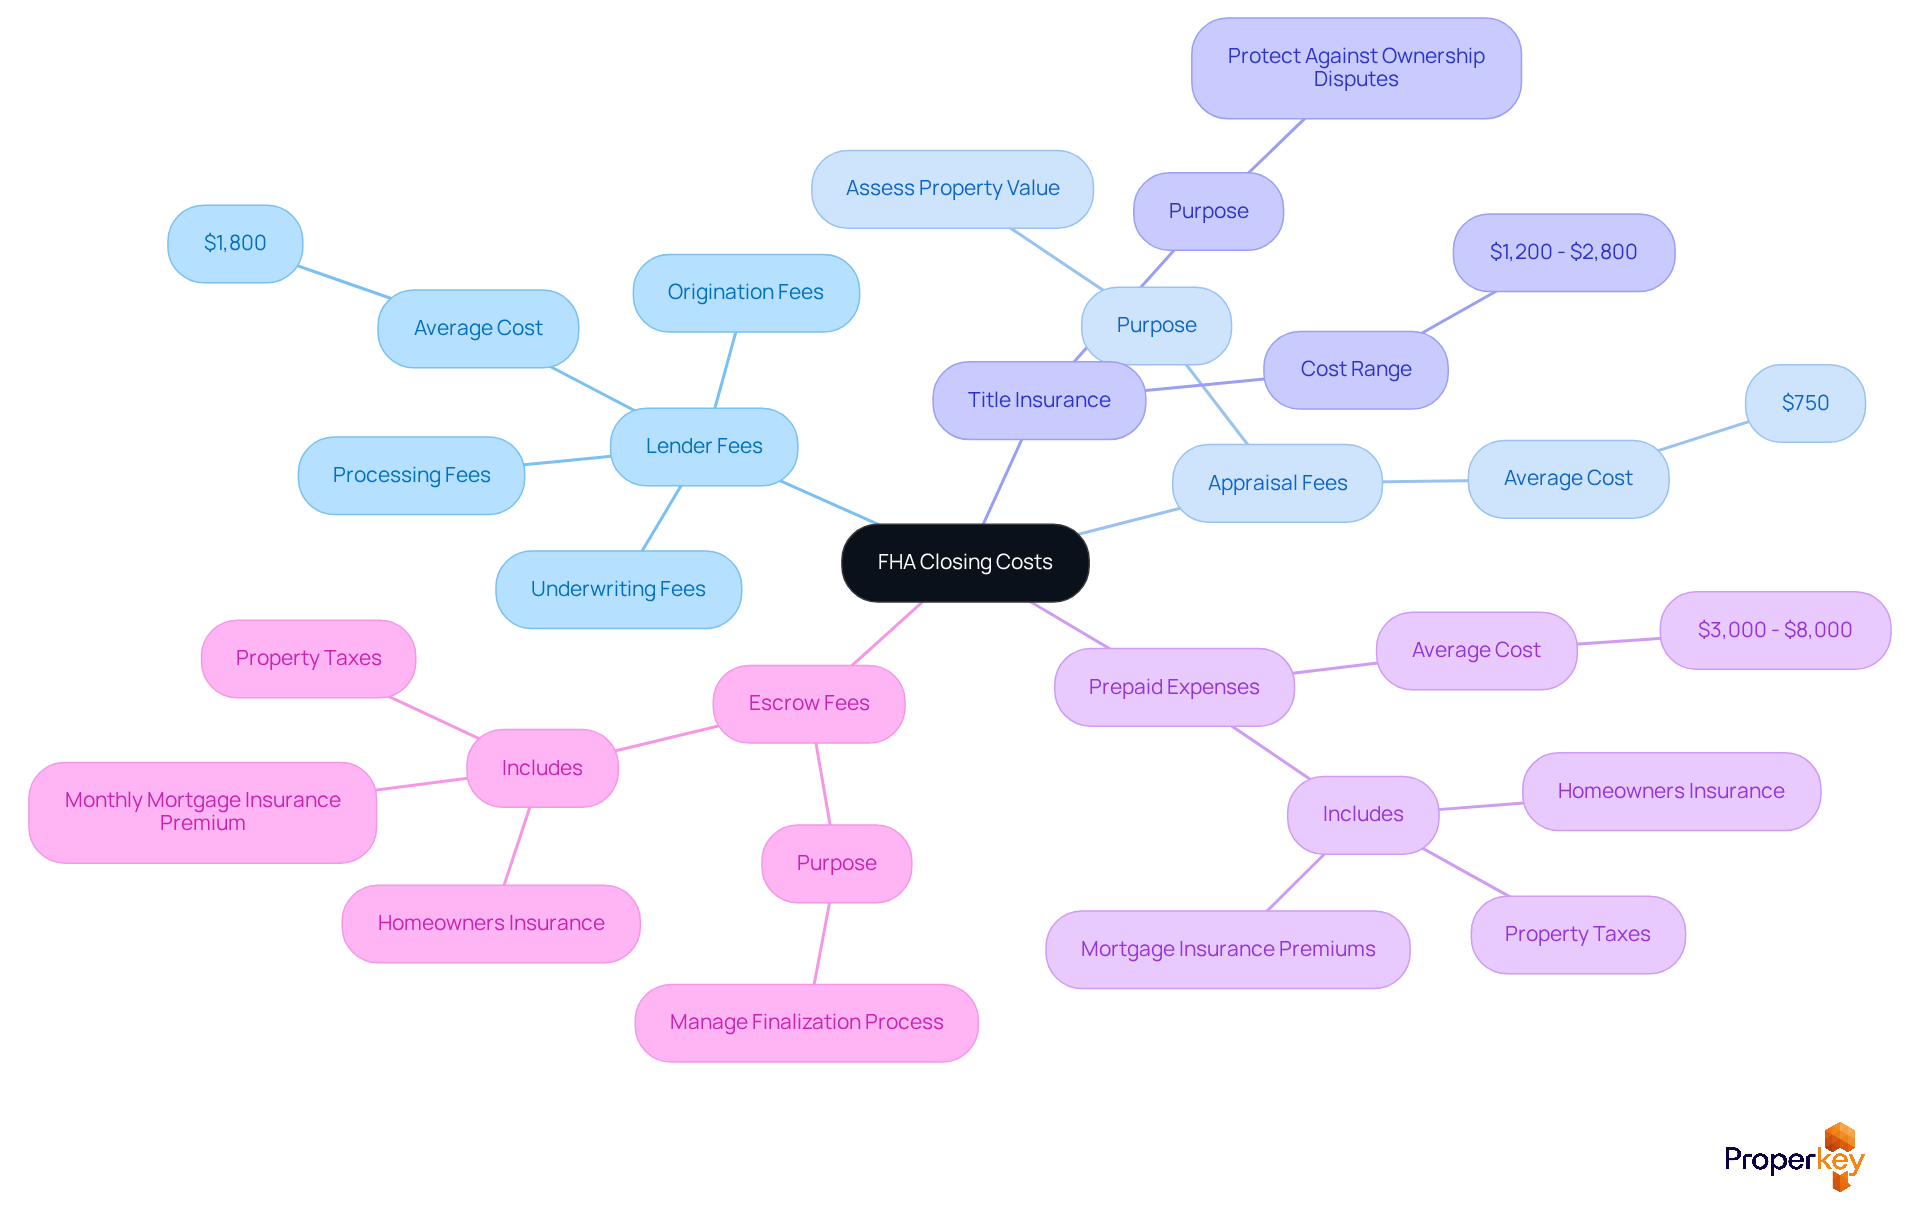
- Lender Fees: These encompass origination fees, underwriting fees, and processing fees, which compensate the lender for their services. For FHA mortgages, lender charges can average approximately $1,800, significantly adding to the total closing expenses.
- Appraisal Fees: Required to assess the property's value, these fees ensure that the home is worth the amount being financed. Appraisal and credit report fees can average about $750, which is essential for determining the loan amount.
- Title Insurance: This protects against potential disputes over property ownership and is a standard requirement in real estate transactions. Title insurance costs can vary widely, with quotes ranging from $1,200 to $2,800 for the same coverage, emphasizing the importance of obtaining multiple quotes.
- Prepaid Expenses: These encompass property taxes, homeowners insurance, and mortgage insurance premiums that are paid in advance at settlement. Prepaid property taxes typically require around six months' worth of taxes to be paid upfront, which can vary significantly based on local rates.
- Escrow Fees: Charged by the escrow company for managing the finalization process, these fees cover the handling of documents and funds. Escrow account fees can include homeowners insurance, monthly mortgage insurance premiums, and property taxes.
When you grasp these components, you can better anticipate your financial obligations and make informed decisions throughout the home buying journey, especially regarding whether closing costs can be included in an FHA loan. In California, for instance, closing costs can range from 2% to 6% of the home's purchase price. Meanwhile, in Idaho and Nevada, regional differences can significantly impact the total cash needed to finalize your transaction. By being aware of these expenses and utilizing strategies such as negotiating seller concessions or shopping for service providers, you can effectively manage your upfront outlays. Being informed about these costs not only prepares you for the financial commitment but also empowers you to negotiate better terms and save money in the long run.
Explain Inclusion of Closing Costs in FHA Loans
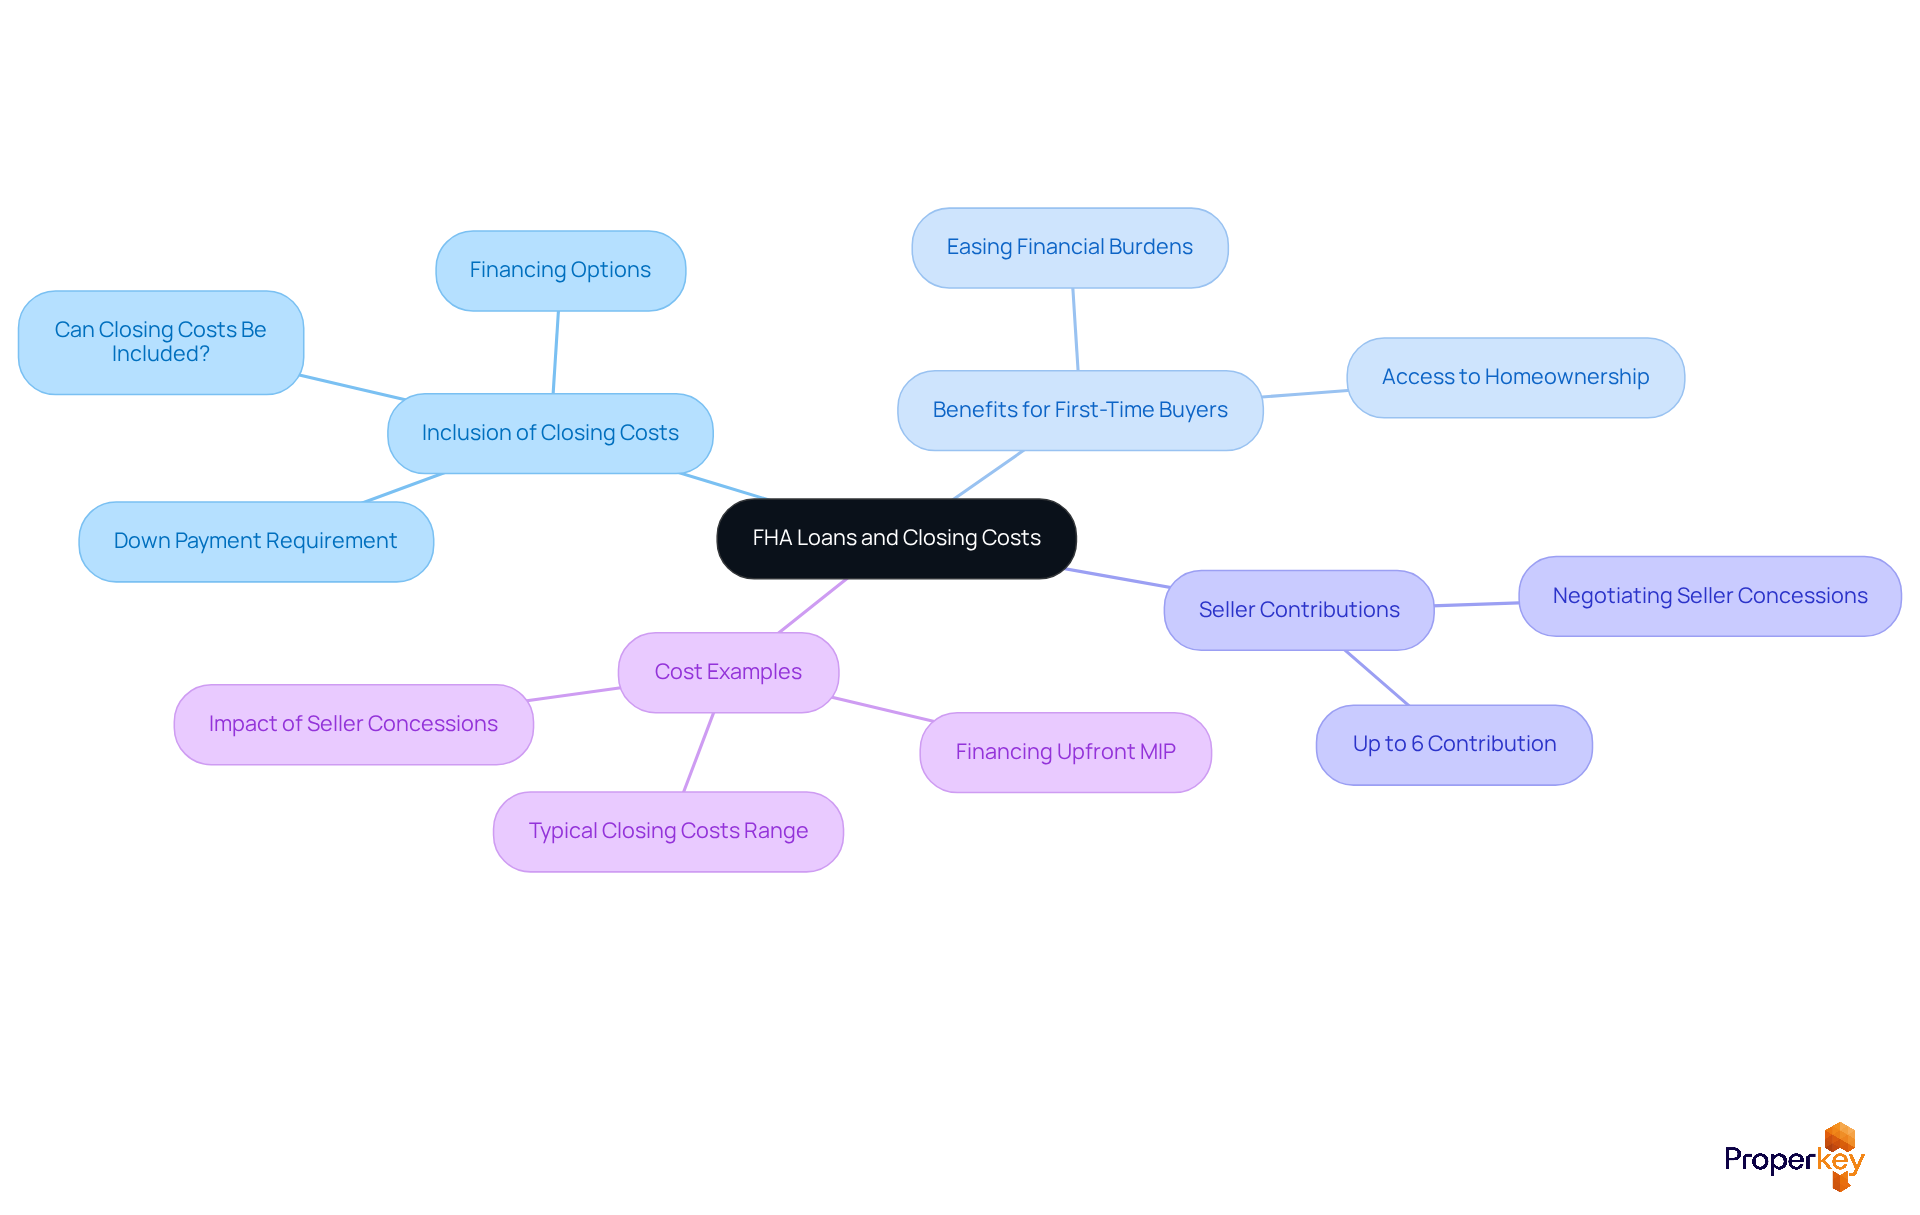
Navigating the financial landscape of homebuying can be overwhelming, especially for first-time buyers in California. FHA loans provide a distinct benefit by allowing borrowers to incorporate expenses into the total loan amount, leading to the question of can closing costs be included in loan FHA, which significantly eases the financial burden at closing. This feature is particularly helpful for first-time homebuyers in California with limited cash reserves. While borrowers can fund these expenses, it's crucial to remember that although can closing costs be included in loan FHA, they cannot be applied toward the minimum down payment requirement of 3.5%.
Moreover, FHA regulations permit sellers to contribute up to 6% of the purchase price toward the buyer's expenses at settlement, leading to the inquiry of how can closing costs be included in loan FHA. This provision helps reduce upfront costs, making it easier to achieve homeownership. For instance, on a $350,000 FHA mortgage, closing costs typically range from $10,500 to $14,000, with seller concessions potentially covering a significant portion of these expenses.
To help buyers navigate their financing options, Loanvana offers a tool that lets users apply once and compare hundreds of funding choices from different lenders. Understanding these financing options empowers buyers to make informed decisions and maximize the benefits of their FHA loans, ultimately leading to a smoother homebuying experience.
Conclusion
Navigating the complexities of FHA loan closing costs is a critical step for prospective homebuyers. When buyers understand the nuances of FHA closing costs, they can prepare for the expenses tied to their mortgage and make informed decisions that align with their financial goals.
Throughout this article, we’ve shared key insights regarding the components of FHA closing costs, including:
- lender fees
- appraisal fees
- title insurance
- prepaid expenses
It's important to note that these costs can range from 2% to 6% of the home's purchase price, influenced by factors such as location and market conditions. Moreover, the potential for seller concessions can alleviate some of these expenses, highlighting the need for buyers to negotiate effectively and explore all available options.
This knowledge not only prepares buyers for financial commitments but also empowers them to make confident choices in the home buying process. As the landscape of home financing continues to evolve, staying educated on these costs and leveraging available resources can lead to a more favorable and successful homeownership experience. By embracing this knowledge, buyers can transform their homeownership dreams into reality, paving the way for lasting financial stability.
Frequently Asked Questions
What are FHA loan closing costs?
FHA loan closing costs are various fees and expenses that borrowers must pay when finalizing their mortgage. These costs typically range from 2% to 6% of the home's purchase price and include lender fees, appraisal fees, title insurance, and prepaid expenses like property taxes and homeowners insurance.
How much can FHA closing costs amount to?
For a $400,000 house, FHA closing costs could range from $8,000 to $24,000, depending on several factors. For a $300,000 loan, these costs are expected to average between $9,000 and $18,000.
Can closing costs be included in an FHA loan?
Yes, FHA regulations allow sellers to contribute up to 6% of the sales price toward qualifying expenses, which can help cover closing costs. This flexibility can ease some financial strain for buyers.
What specific fees are included in FHA closing costs?
FHA closing costs can include the upfront mortgage insurance premium (MIP), which is 1.75% of the principal amount, annual MIP (around 0.55% of the total amount), appraisal fees (averaging between $400 and $800), and title fees (ranging from $500 to $2,000).
How can buyers lower their FHA closing costs?
Buyers can lower their closing costs through seller concessions, where sellers contribute a portion of the home's price toward final expenses. This is particularly beneficial in balanced markets where negotiations are more favorable.
Why is it important to understand FHA closing costs?
Understanding FHA closing costs is crucial for financial planning, as these expenses can significantly impact the overall affordability of acquiring a home. It allows buyers to budget effectively and avoid unexpected financial stress.
What should buyers review to understand their FHA closing costs?
Buyers should review the Loan Estimate, which outlines projected expenses, monthly payments, and the cash required at settlement. This document is essential for understanding the financial aspects of the FHA loan process.
How do FHA closing costs vary by region?
FHA closing costs can vary by region; for example, in California, buyers may encounter higher charges due to state-specific regulations, while in Idaho, expenses may be lower due to fewer local taxes. Understanding these regional variations helps buyers navigate FHA financing more confidently.
List of Sources
- Define FHA Loan Closing Costs
- FHA Loan Closing Costs (https://neighborsbank.com/fha-loans/closing-costs)
- Understanding FHA Loan Closing Costs (https://freedommortgage.com/learn/homebuying/fha-closing-costs)
- FHA Closing Costs: What They Are And How Much You’ll Pay | Bankrate (https://bankrate.com/mortgages/fha-closing-costs)
- FHA Loan Closing Costs in 2026: What to Expect and How to Save (https://amerisave.com/learn/fha-loan-closing-costs-in-what-to-expect-and-how-to-save)
- FHA Loan Closing Cost Requirements (https://lower.com/mortgages/fha-loan/fha-loan-closing-costs-guide)
- Contextualize FHA Closing Costs in Home Financing
- FHA Loan Closing Costs (https://neighborsbank.com/fha-loans/closing-costs)
- FHA Closing Costs: What They Are And How Much You’ll Pay | Bankrate (https://bankrate.com/mortgages/fha-closing-costs)
- Trace the Evolution of FHA Loan Closing Costs
- What Are FHA Closing Costs? (https://lendingtree.com/home/mortgage/fha-loan-closing-costs)
- FHA Loan Closing Costs: What You'll Pay and How To Save | Homeownership Hub (https://fairway.com/articles/fha-loan-closing-costs-what-youll-pay-and-how-to-save)
- Study: Nonfinancial Borrower Characteristics Raise FHA Loan Closing Costs (https://nlihc.org/resource/study-nonfinancial-borrower-characteristics-raise-fha-loan-closing-costs)
- FHA Loan Closing Costs 2026: Complete Breakdown (https://rebillion.ai/blog/2026/02/27/fha-loan-closing-costs)
- FHA Loan Closing Costs in 2026: What to Expect and How to Save (https://amerisave.com/learn/fha-loan-closing-costs-in-what-to-expect-and-how-to-save)
- Identify Key Components of FHA Closing Costs
- FHA Closing Costs: What They Are And How Much You’ll Pay | Bankrate (https://bankrate.com/mortgages/fha-closing-costs)
- FHA Loan Closing Costs: What You'll Pay and How To Save | Homeownership Hub (https://fairway.com/articles/fha-loan-closing-costs-what-youll-pay-and-how-to-save)
- What Are FHA Closing Costs? (https://lendingtree.com/home/mortgage/fha-loan-closing-costs)
- FHA Loan Closing Cost Requirements (https://lower.com/mortgages/fha-loan/fha-loan-closing-costs-guide)
- FHA Loan Closing Costs in 2026: What to Expect and How to Save (https://amerisave.com/learn/fha-loan-closing-costs-in-what-to-expect-and-how-to-save)
- Explain Inclusion of Closing Costs in FHA Loans
- FHA Loan Closing Costs: What You Need to Know | Chase (https://chase.com/personal/mortgage/education/financing-a-home/fha-loan-closing-costs)
- FHA Loans: What to Know in 2026 - NerdWallet (https://nerdwallet.com/mortgages/learn/fha-loan)
- FHA Loan Closing Cost Requirements (https://lower.com/mortgages/fha-loan/fha-loan-closing-costs-guide)
- FHA Loan Closing Costs in 2026: What to Expect and How to Save (https://amerisave.com/learn/fha-loan-closing-costs-in-what-to-expect-and-how-to-save)