Master the Refinance Divorce Buyout: Steps to Success in California
Introduction
Navigating the financial landscape of a divorce can feel overwhelming, especially when home ownership is involved. In this guide, we’ll explore the essential steps and strategies you need to successfully execute a refinance divorce buyout in California, addressing common challenges and the critical role of professional guidance. With the right strategies and expert support, individuals can confidently navigate this process and secure their financial future.
Define Refinance Divorce Buyout: Understanding the Basics
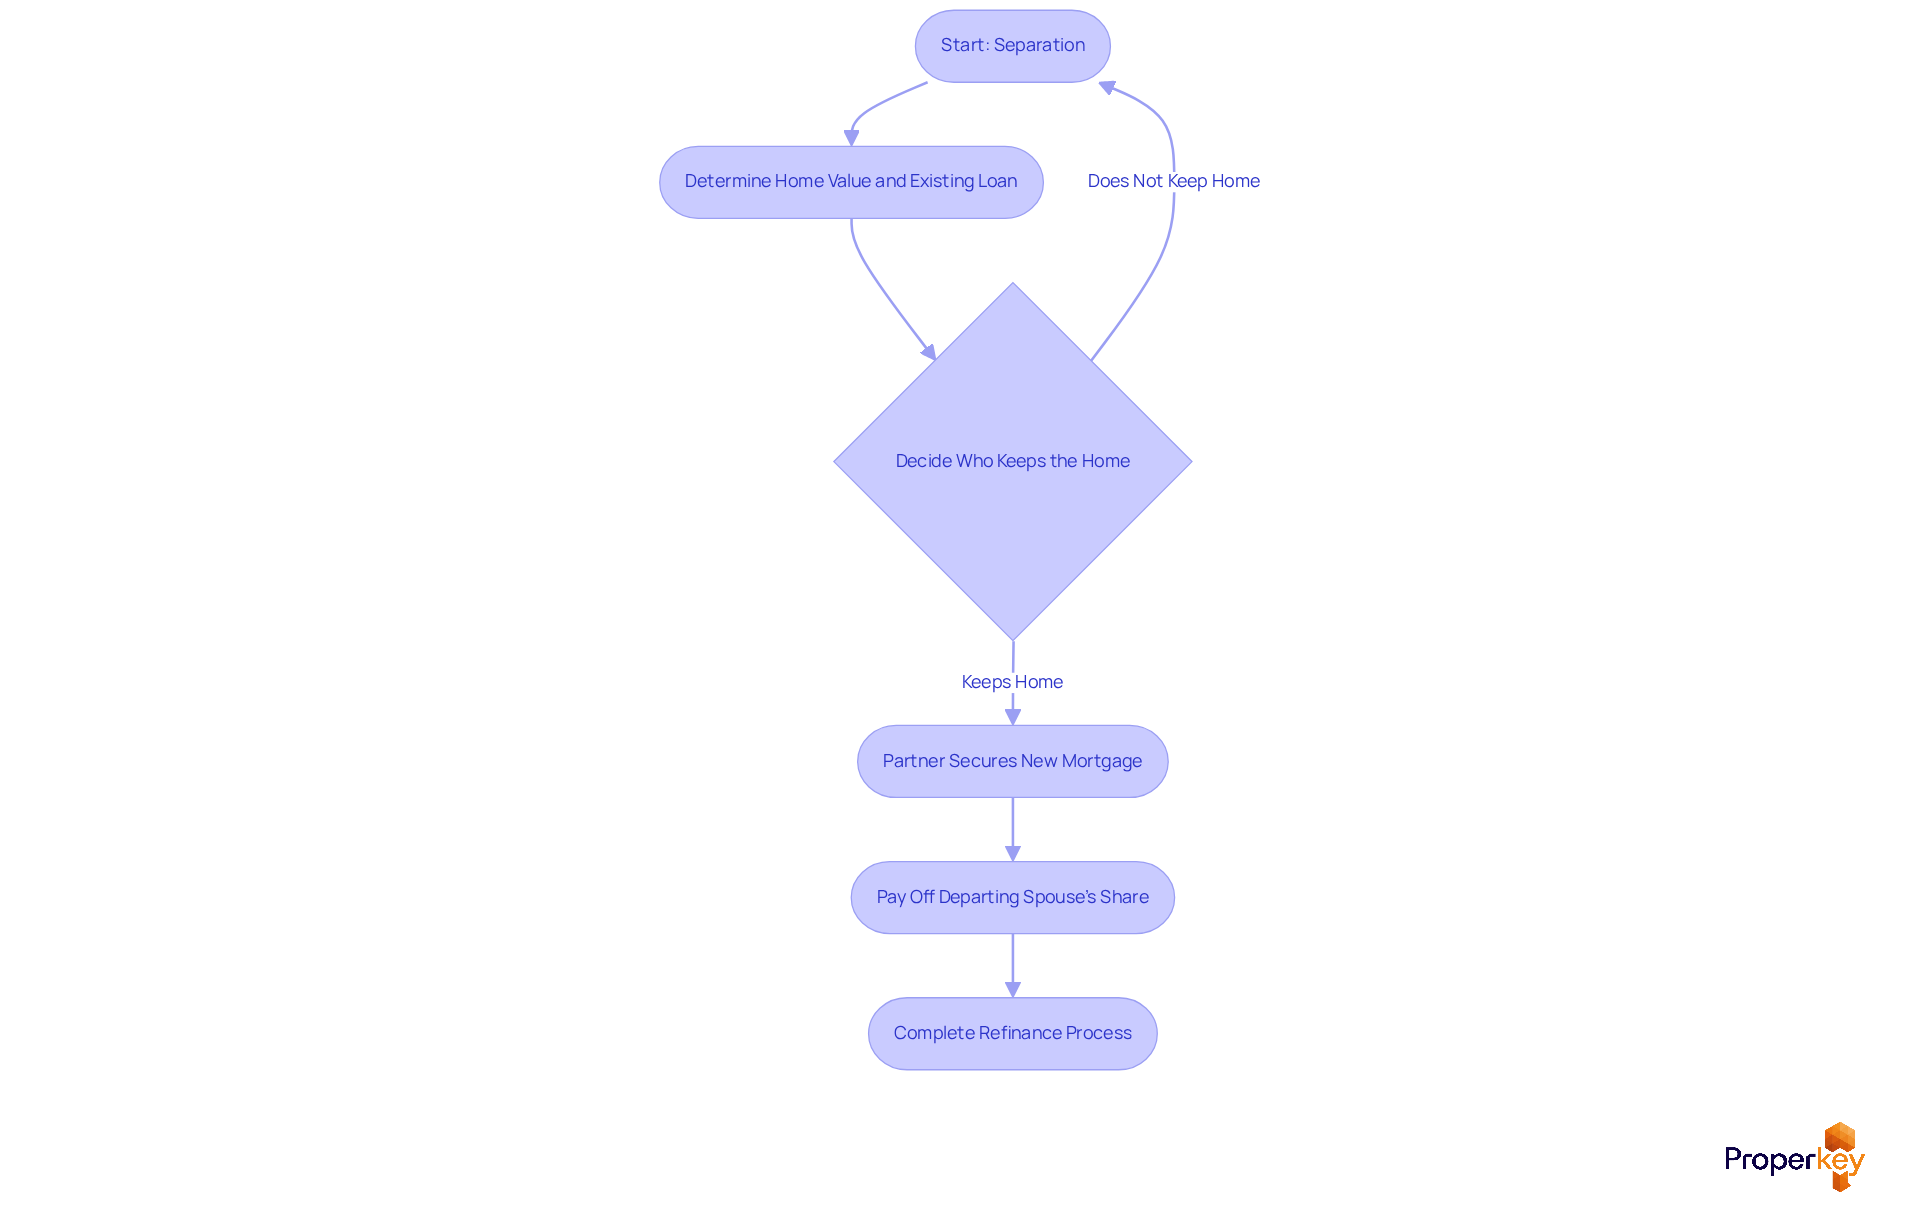
Navigating the complexities of a separation can be daunting, especially when it comes to financial obligations tied to your home. A refinance divorce buyout is an arrangement where one partner refinances the current loan to exclude the other partner from the obligation. This process usually requires the spouse who wants to keep the home to secure a new mortgage in their name. They can use the home equity to pay off the departing spouse's share. Grasping this concept is essential, as it includes both financial and legal implications of property division during a separation.
In California, the dissolution decree outlines the terms of the refinance divorce buyout, detailing the amount owed to the departing spouse and any conditions necessary for the refinance to proceed. For example, if a couple jointly possesses a residence valued at $1,200,000 with a $500,000 loan, the partner retaining the home may refinance into an $850,000 loan, settling the current debt and compensating the departing spouse with their $350,000 portion.
Did you know that refinancing after a separation can greatly enhance your financial stability? Many individuals choose this path to simplify their obligations and boost their credit scores. Getting in touch with a skilled loan expert early on can really help you navigate the refinancing process, ensuring adherence to California's separation settlement laws and clarifying the procedure of providing your most recent loan statement to potentially save money.
At Vana, we offer streamlined refinancing solutions that allow you to save money with quick qualification processes. By providing your most recent mortgage statement, we can show you how to save, and if you're already in the process, we can beat your written loan estimate. Our team can qualify you in just a few minutes and provide your Loan Qualification Letter immediately, or even a full Loan Approval Letter for free when qualified. Without the right guidance, you risk complicating your financial future, but with Vana, you can take control and simplify the process.
Outline the Steps for a Successful Refinance Divorce Buyout
Navigating the complexities of a divorce can be overwhelming, especially when it comes to property ownership.
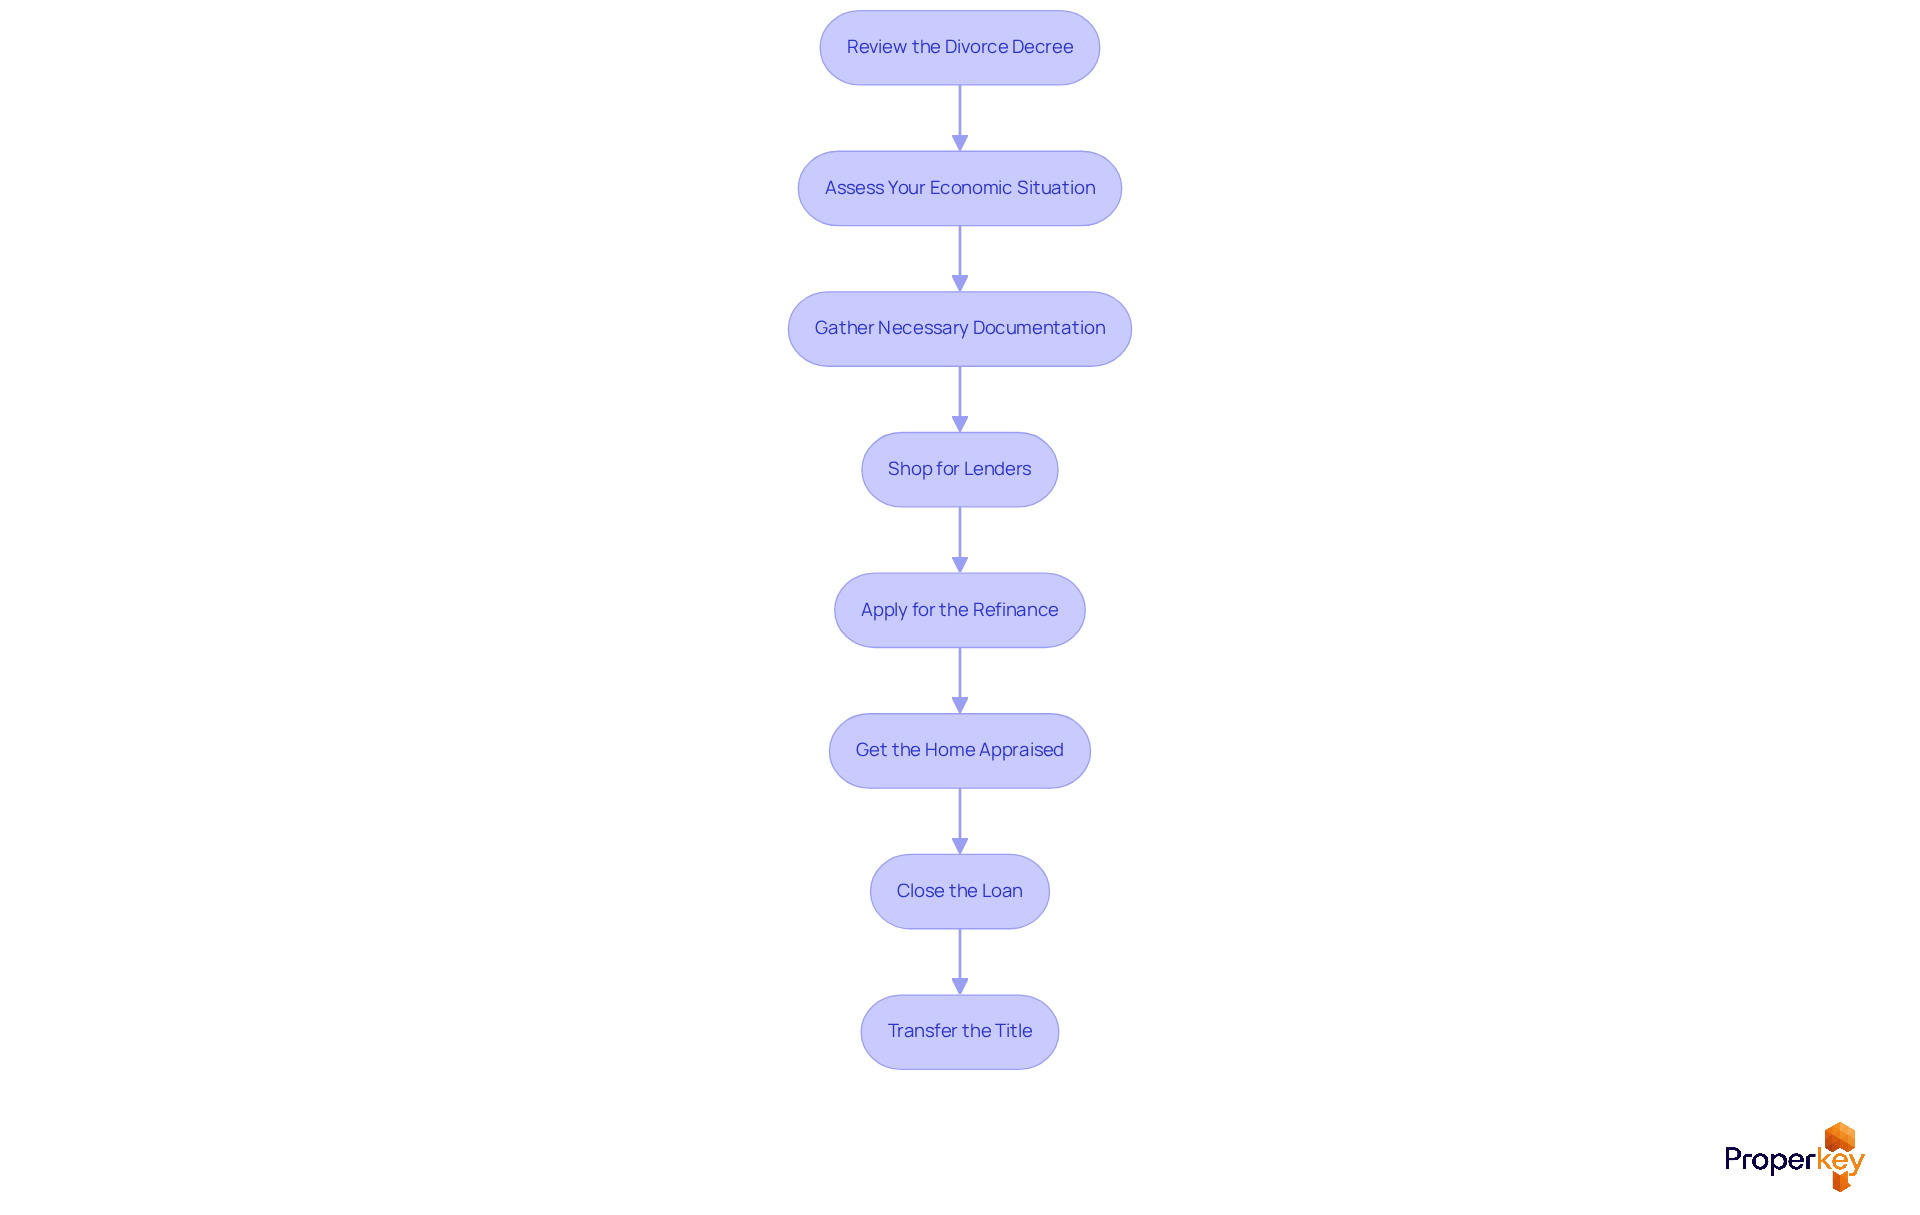
- Review the Divorce Decree: Begin by thoroughly examining the divorce decree to understand the buyout terms, including the amount owed to your ex-spouse and any stipulations regarding the property. Understanding these terms is vital for securing your sole ownership of the property.
- Assess Your Economic Situation: Evaluate your credit score, income, and overall economic health. Evaluating your financial health is essential to determine if you can refinance on your own, manage the equity acquisition, and ensure that the new payment fits your life post-divorce.
- Gather Necessary Documentation: Collect all required documents, such as tax returns, pay stubs, bank statements, and the dissolution decree. These documents will be essential for the lender's review and to ensure a smooth application process.
- Shop for Lenders: Investigate and contrast lenders who focus on separation acquisitions. Look for those with favorable terms and a solid understanding of the nuances involved in divorce-related refinancing, as this can significantly impact your experience. Utilize Loanvana's financing tool to apply once and compare hundreds of loan options side-by-side from multiple lenders, ensuring you find the best rates available.
- Apply for the Refinance: Submit your application along with the gathered documentation. Be prepared to explain your situation and the terms of the divorce decree to the lender, as this transparency can facilitate the approval process.
- Get the Home Appraised: The lender will require an appraisal to determine the current market value of the home. This step is crucial for calculating the equity available for the buyout, especially in California's competitive real estate market. For instance, if the home is valued at $500,000, the departing spouse's share of equity could be $90,000 based on a 50/50 split.
- Close the Loan: Once approved, you will close on the new loan. The funds will be used to settle the current loan and compensate your ex-spouse for their equity share. Typically, a post-divorce refinance takes about 30-45 days from application to closing.
- Transfer the Title: After closing, ensure that the title is updated to reflect your sole ownership of the property. This may involve filing an interspousal transfer deed with the county recorder's office, ensuring that all legal requirements are met for a clean title transfer.
Taking these steps not only secures your financial future but also empowers you to move forward confidently post-divorce.
Identify Common Challenges and Solutions in the Buyout Process
Selling your home can be a daunting task, especially when faced with financial hurdles that complicate the refinance divorce buyout. Here are some common challenges and how to navigate them effectively:
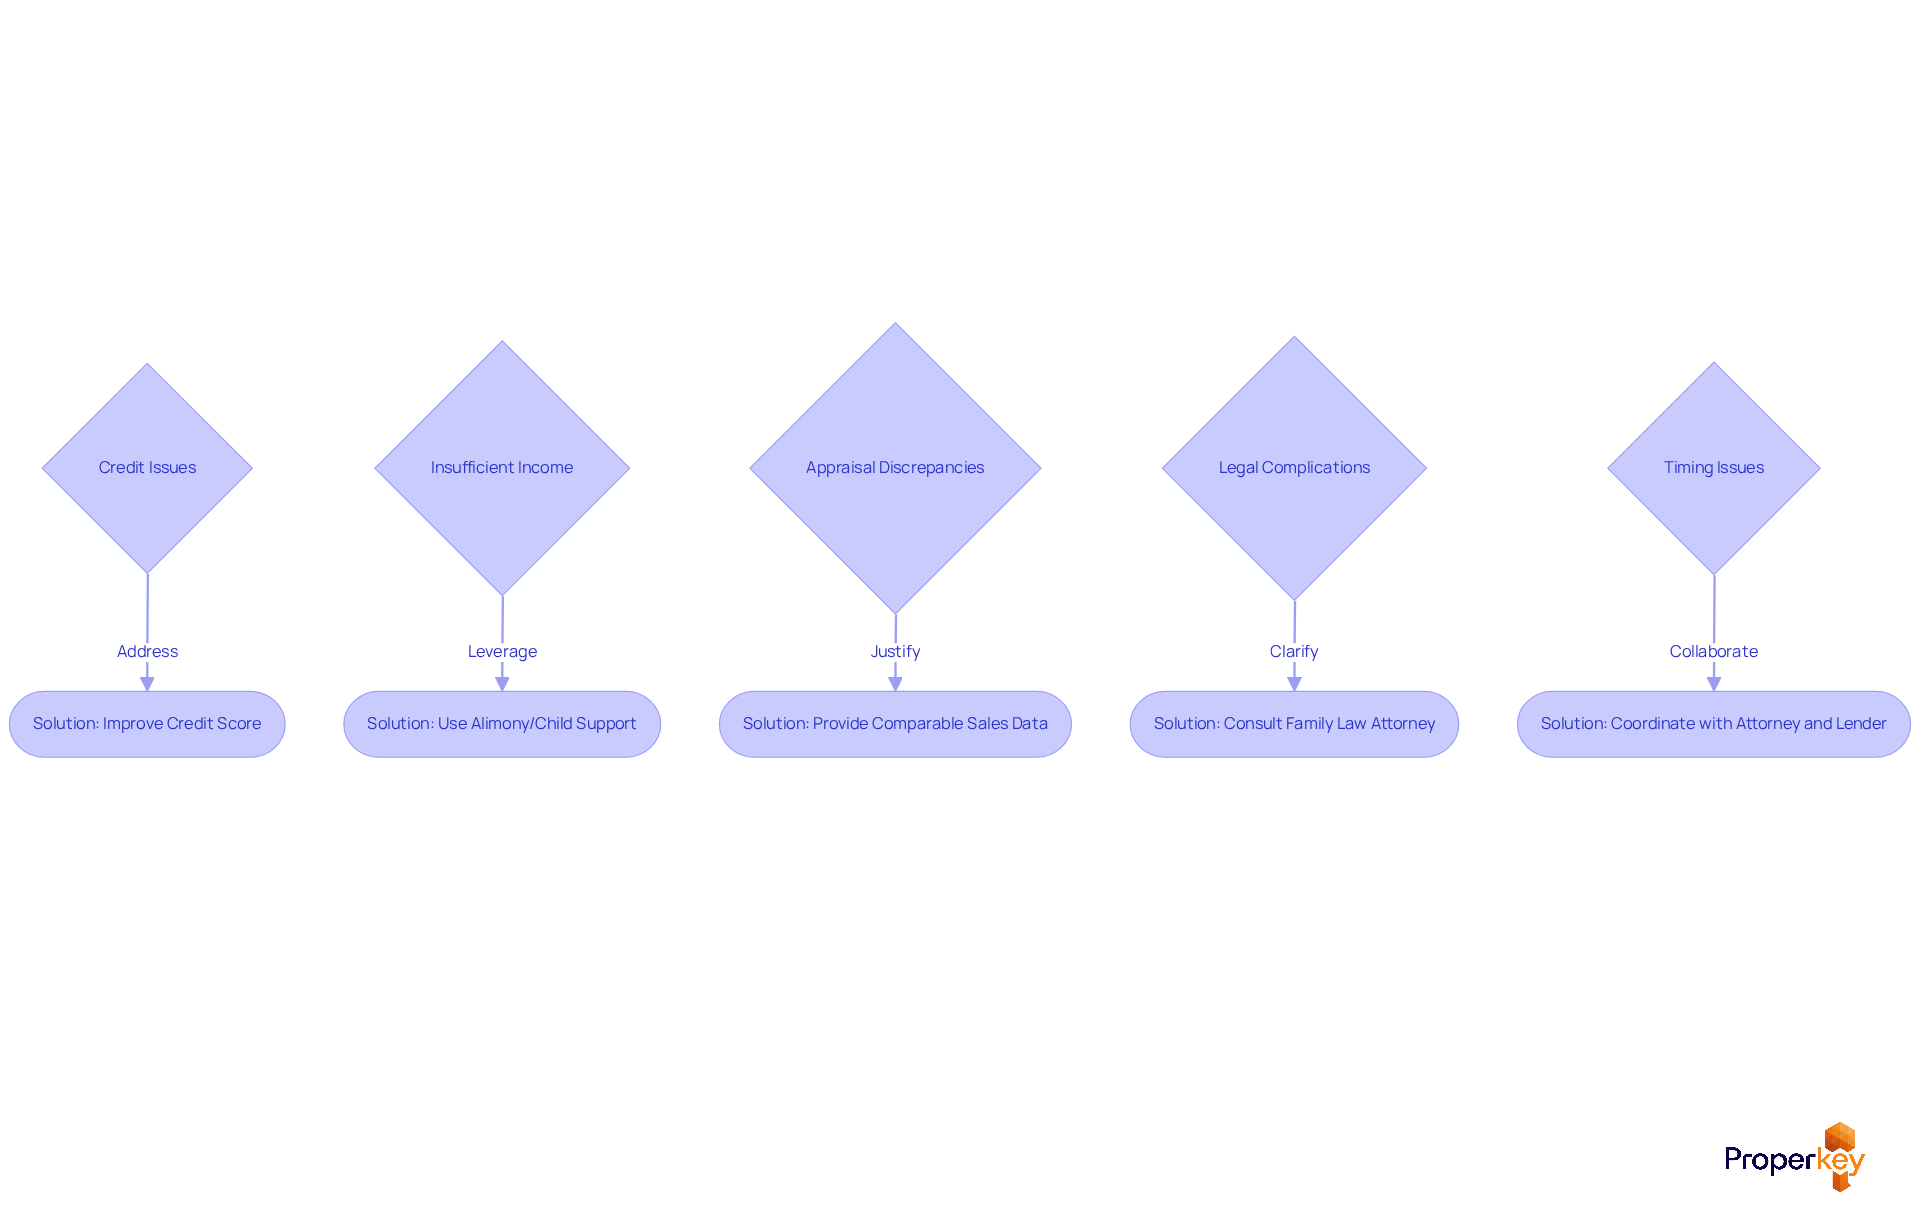
- Credit Issues: Qualifying for a refinance on a single income can be one of the toughest challenges you face. If your credit score is below the acceptable threshold of 620, focus on improving it before applying. Strategies like paying down existing debts and ensuring timely payments on all bills can significantly enhance your credit profile.
- Insufficient Income: Is your income falling short for that new mortgage? Consider leveraging alimony or child support as qualifying income. Many lenders accept these payments as part of your income calculation, which can help bridge the gap in your financial profile.
- Appraisal Discrepancies: A common issue arises when the home appraisal comes in lower than anticipated, impacting the buyout amount. To counter this, provide the appraiser with recent comparable sales data and document any improvements made to the property. This can help justify a higher valuation. Be aware that appraisal costs typically range from $500 to $750, which can add to your overall expenses.
- Legal Complications: Clarity in the dissolution decree is crucial. Ambiguities can lead to disputes during the refinancing process. Consulting with a family law attorney can help ensure that all legal terms are clearly defined, reducing the risk of complications later on.
- Timing Issues: Coordinating the timing of the refinance with the separation proceedings can be challenging. Refinancing usually requires 30 to 45 days, making it crucial to collaborate closely with both your attorney and lender to ensure that the refinance coincides with the separation timeline, avoiding unnecessary delays or complications.
Addressing these challenges head-on can pave the way for a smoother refinance divorce buyout experience and ultimately lead to a successful sale.
Seek Professional Guidance: The Role of Experts in Your Buyout
Navigating the refinance divorce buyout process during a separation can feel like a daunting task, but the right professionals can make all the difference.
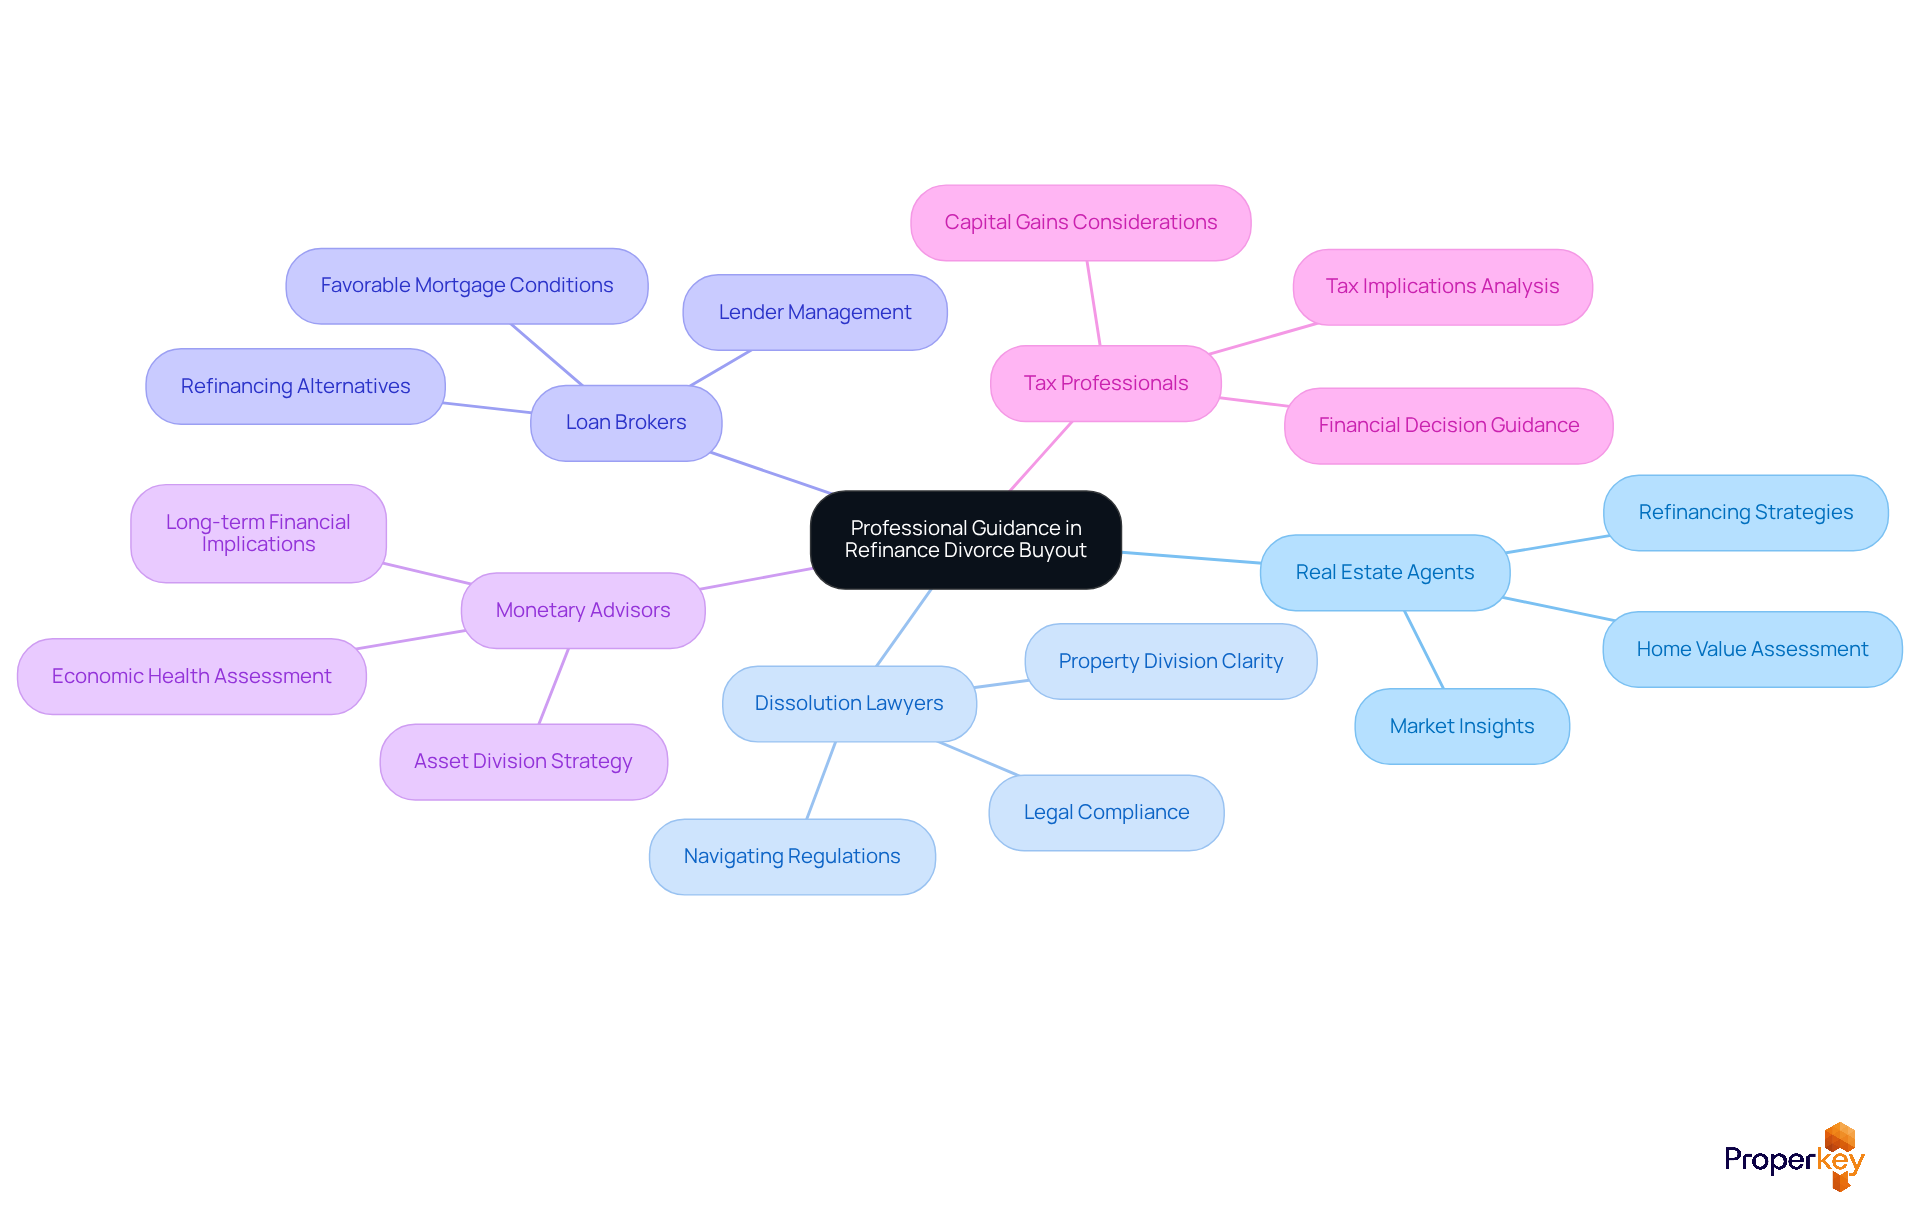
- Real Estate Agents: A knowledgeable real estate agent plays a crucial role in the refinancing process during a separation. They provide insights into the local market, helping you assess your home's value and identify the best refinancing strategies. With 61% of separations leading to the sale of the marital residence, having a specialist who understands the intricacies of refinance divorce buyout can greatly influence your financial outcome. With Properkey's dedicated local agents, you’ll have a trusted partner by your side, guiding you through every step of your home buying and selling journey for a seamless experience.
- Dissolution Lawyers: Hiring a dissolution lawyer who focuses on property division guarantees that your separation decree is clear and enforceable. This legal clarity is essential for safeguarding your interests during the refinance divorce buyout process, particularly considering California's changing regulations concerning loan assumptions in separation cases. Properkey can assist in connecting you with attorneys who understand these complexities.
- Loan Brokers: A loan broker can be essential in discovering refinancing alternatives suited to your particular circumstances. Their knowledge of separation settlements enables them to manage lender requirements efficiently, ensuring you can successfully refinance divorce buyout and obtain the most favorable conditions for your new mortgage. Properkey's integrated services simplify this process, providing access to a range of financing options.
- Monetary Advisors: Consulting a monetary advisor is essential for understanding the long-term implications of a refinance divorce buyout on your economic health. They can assist you in making informed choices that align with your overall monetary strategy, particularly in the context of asset division during divorce proceedings. Properkey's monetary tools can help you evaluate your options more effectively.
- Engaging a tax professional can clarify any tax implications related to the refinance divorce buyout. Comprehending possible liabilities or advantages is essential, particularly as the timing of the home sale can influence capital gains taxes and overall economic results. With the right guidance, you can navigate these complexities and make decisions that safeguard your financial future. Properkey can connect you with tax professionals who specialize in real estate transactions.
With the right team by your side, you can confidently navigate the refinancing landscape and secure your financial future.
Conclusion
Understanding the refinance divorce buyout process in California is crucial for securing your financial future after separation. This process involves understanding legal and financial implications. It also requires careful planning and execution for a smooth transition. When you understand refinancing and the value of professional help, you can take control of your circumstances and make informed decisions.
Key steps in the refinance divorce buyout process include:
- Reviewing the divorce decree
- Assessing financial health
- Gathering necessary documentation
- Selecting the right lenders
Navigating credit issues, appraisal discrepancies, and legal complications can be daunting, but with expert guidance, you can turn these challenges into manageable steps. Engaging with professionals like real estate agents, dissolution lawyers, loan brokers, and monetary advisors can provide invaluable support, ensuring that all aspects of the refinance are handled efficiently and effectively.
The refinance divorce buyout process goes beyond financial transactions. It’s about reclaiming your independence and stability after a significant life change. Taking these steps not only secures your financial future but also empowers you to embrace new opportunities ahead. Embracing this journey with the right knowledge and support can lead to a successful resolution, allowing for a fresh start and renewed focus on personal goals.
Frequently Asked Questions
What is a refinance divorce buyout?
A refinance divorce buyout is an arrangement where one partner refinances the current loan to exclude the other partner from the obligation, allowing the spouse who wants to keep the home to secure a new mortgage in their name and use home equity to pay off the departing spouse's share.
What are the financial implications of a refinance divorce buyout?
The financial implications include the need for the spouse retaining the home to refinance the mortgage, which may involve taking on a larger loan to pay off the departing spouse's share of the home equity.
How does the dissolution decree affect the refinance divorce buyout process in California?
The dissolution decree outlines the terms of the refinance divorce buyout, including the amount owed to the departing spouse and any conditions necessary for the refinance to proceed.
Can you provide an example of how a refinance divorce buyout works?
For instance, if a couple jointly owns a home valued at $1,200,000 with a $500,000 loan, the partner keeping the home may refinance into an $850,000 loan to pay off the existing debt and compensate the departing spouse with their $350,000 share.
How can refinancing after a separation improve financial stability?
Refinancing after a separation can simplify financial obligations and potentially boost credit scores, making it a beneficial option for individuals navigating a divorce.
What should individuals do to navigate the refinancing process effectively?
It is advisable to contact a skilled loan expert early on to ensure adherence to California's separation settlement laws and to clarify the refinancing process.
What services does Vana offer for refinancing?
Vana offers streamlined refinancing solutions with quick qualification processes, the ability to show potential savings, and immediate provision of Loan Qualification Letters or full Loan Approval Letters for free when qualified.
List of Sources
- Define Refinance Divorce Buyout: Understanding the Basics
- Divorce Mortgage in California: Buyout & Refinance (https://mycahomeloan.com/equity-buyout-refinance-california-divorce)
- Refinancing a Divorce Buyout in California: What You Need to Know (https://landifyr.com/refinancing-a-divorce-buyout-in-california-what-you-need-to-know)
- How To Refinance Your Mortgage After A Divorce (https://lower.com/mortgages/how-to-refinance-your-mortgage-after-a-divorce)
- Divorce Buyout Refinance in California | How to Qualify Solo (https://collinscoastalhomes.com/blog/post/divorce-buyout-refinance-qualify-solo-california.html)
- Divorce Mortgage Buyout in California: How It Actually Works (https://northbaycap.com/blog/divorce-mortgage-buyout-remove-spouse-california)
- Outline the Steps for a Successful Refinance Divorce Buyout
- Rate-and-Term Refinance After Divorce: Buyout Guide (https://shouldirefinanceyet.com/blog/rate-and-term-refinance-after-divorce-buyout-guide)
- Divorce & Mortgage CA: Buyout Options | Mortgage Guide CA (https://mortgageguidecalifornia.com/scenarios/divorce-mortgage)
- Refinancing After Divorce: A Step-by-Step Guide (https://contourmortgage.com/news/refinancing-after-divorce-a-step-by-step-guide)
- Refinancing a Divorce Buyout in California: What You Need to Know (https://landifyr.com/refinancing-a-divorce-buyout-in-california-what-you-need-to-know)
- Divorce Buyout Refinance in California | How to Qualify Solo (https://collinscoastalhomes.com/blog/post/divorce-buyout-refinance-qualify-solo-california.html)
- Identify Common Challenges and Solutions in the Buyout Process
- Refinancing a Divorce Buyout in California: What You Need to Know (https://landifyr.com/refinancing-a-divorce-buyout-in-california-what-you-need-to-know)
- Mortgage After Divorce 2026: Refinance, Buyout & Removal Guide (https://mortgage-info.com/blog/mortgage-after-divorce-2025-complete-guide)
- Refinancing After Divorce in California: Complete 2026 Guide (https://haslamperrilawfirm.com/refinancing-after-divorce-california)
- Refinancing Your Mortgage After Divorce in California (2026 Guide) (https://divorce.law/guides/refinancing-mortgage-after-divorce/california)
- Keeping the House After Divorce: How to Buy Out Your Ex & Protect Your Financial Future (https://contourmortgage.com/news/keeping-the-house-after-divorce-how-to-buy-out-your-ex-and-protect-your-financial-future)
- Seek Professional Guidance: The Role of Experts in Your Buyout
- California's New Divorce Mortgage Law: What Splitting Couples Need to Know Before 2027 (https://dailynewsonline.com/californias-new-divorce-mortgage-law-what-splitting-couples-need-to-know-before-2027)
- I'm a Divorce Real Estate Expert—How To Navigate Separating Your Assets (https://realtor.com/advice/sell/divorce-real-estate-assets)
- Breaking Down the Divorce Market (https://divorcelendingassociation.com/library/breaking-down-the-divorce-market.cfm)
- California Code 2951: New Rules for Mortgages in a Divorce - Lewitt Hackman (https://lewitthackman.com/california-code-2951-new-rules-for-mortgages-in-a-divorce)



