Should I Get Owner's Title Insurance? A Step-by-Step Guide

Introduction
Homeowners often find themselves at risk of losing their investments due to hidden threats like undisclosed liens and fraudulent claims. The question of whether to secure owner's title insurance looms large, as it serves as a crucial safeguard against potential ownership disputes.
Let’s explore the essential benefits of title insurance together, examining its coverage, costs, and the long-term value it provides. Understanding the necessity of title insurance could be the difference between safeguarding your investment and facing unforeseen challenges.
Understand Owner's Title Insurance Basics
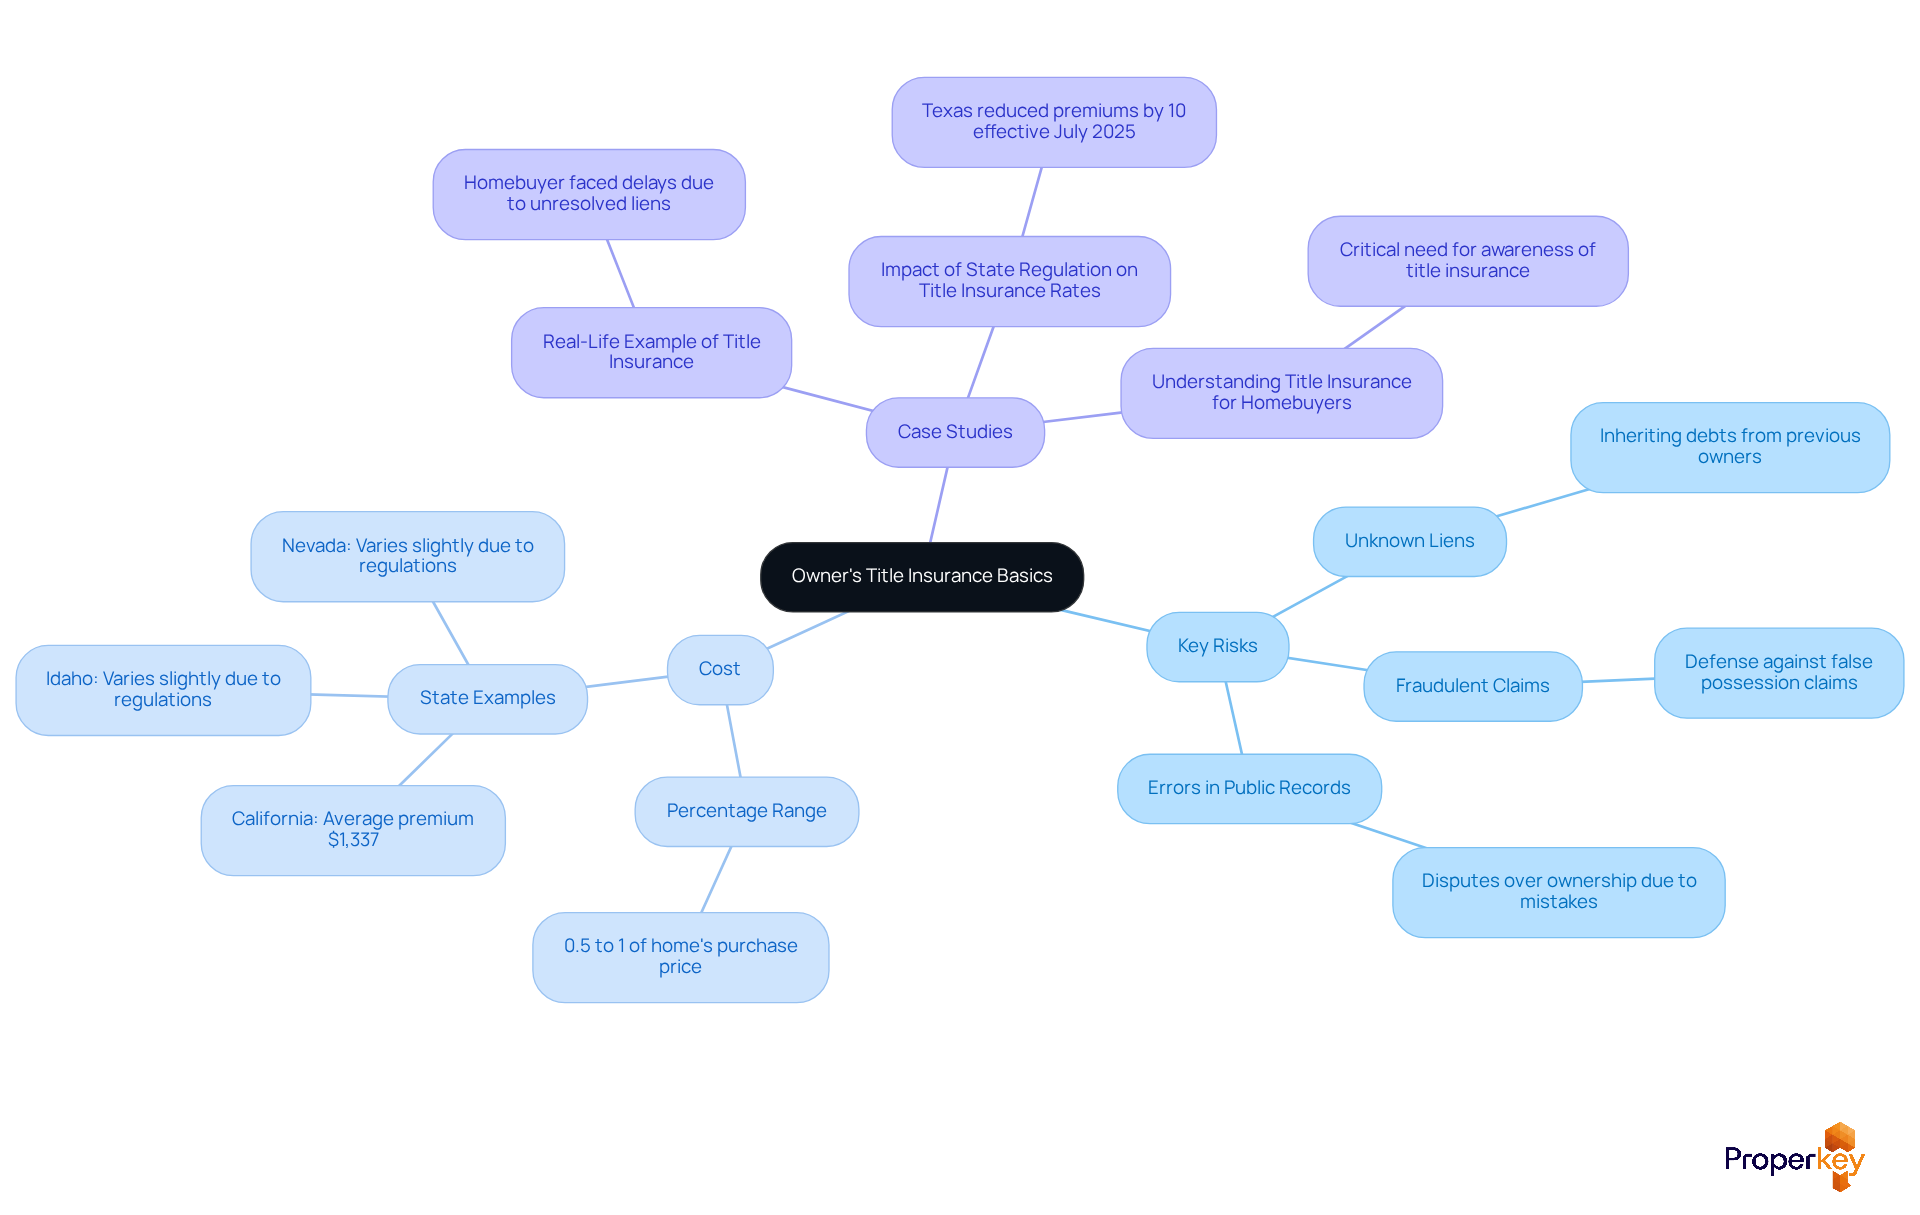
Are you aware that your property could be at risk from hidden claims and ownership disputes? Homeowners often wonder, should I get owner's title insurance, as it serves as an essential safeguard against possible claims related to ownership issues. Unlike conventional coverage agreements that necessitate continuous payments, title protection for property is a single charge made at closing, offering lifetime security. Let’s explore the key risks this policy protects you from:
- Unknown Liens: Imagine inheriting debts from a previous owner, leaving you financially vulnerable. If a previous owner had debts secured by the property, these could become your responsibility, potentially leading to financial strain.
- Fraudulent Claims: In situations where an individual falsely asserts possession of the property, the coverage can assist in defending against such claims, ensuring your interests are safeguarded.
- Errors in Public Records: Mistakes in public records can lead to disputes over ownership, and ownership protection offers a safety net against these unforeseen legal challenges.
In states like California, Idaho, and Nevada, property coverage typically costs between 0.5% and 1% of the home's purchase price. This can vary based on local market conditions. For instance, in California, the average premium is approximately $1,337, while costs in Idaho and Nevada may differ slightly due to state regulations and property values. It's reassuring to note that only 3-5% of policy agreements result in claims. This low claim rate means that most homeowners can rest easy, knowing their investment is well protected.
Real estate case studies in these states raise the question of whether I should get owner's title insurance due to its advantages. For instance, a homeowner in California encountered delays in closing because of undisclosed liens, which were discovered by the documentation company. This enabled the seller to address these matters prior to completing the sale. This scenario highlights the significance of ownership protection in facilitating smooth transactions and safeguarding investments, as it can help identify liens that need to be cleared before finalizing a purchase.
Now that you understand the importance of title protection, take the next step to secure your investment today.
Identify Coverage and Protection Offered
Are you aware that your ownership rights could be at risk without the right insurance coverage? Homeowners often wonder, should I get owner's title insurance, as it provides essential protection by covering various potential issues that could jeopardize ownership rights. Key areas of coverage include:
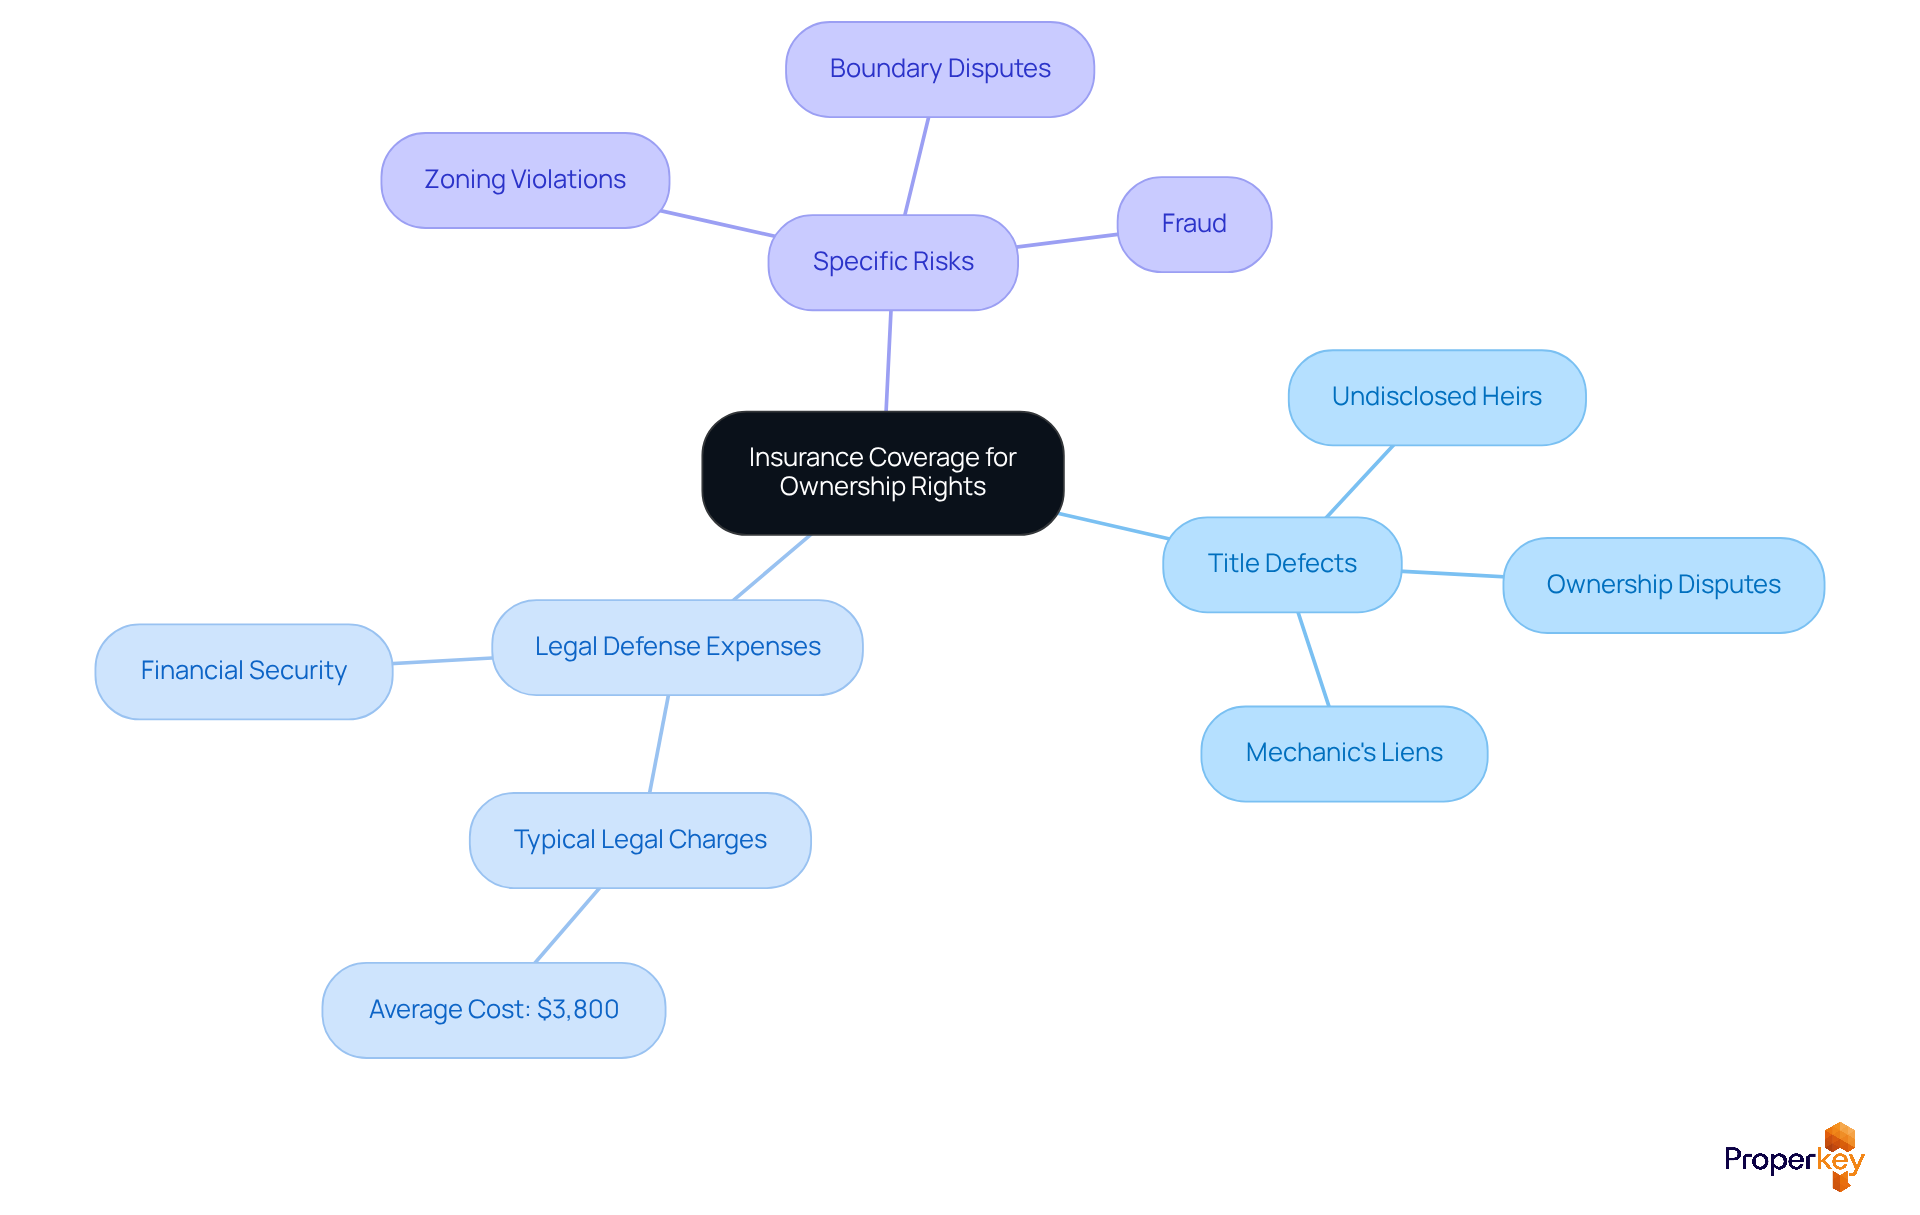
- Title Defects: This encompasses problems that existed prior to the purchase, such as undisclosed heirs, prior ownership disputes, or mechanic's liens due to unpaid work by previous owners. Frequent ownership defects include lost, forged, or improperly filed deeds, which can result in substantial legal claims against a property. In California, unresolved contractor disputes can lead to expensive legal battles.
- Legal Defense Expenses: If a claim occurs against your ownership, the coverage includes legal fees related to defending your rights. The typical expense of legal charges associated with ownership protection claims is around $3,800, highlighting the financial security provided by the coverage. Navigating legal disputes can drain your resources and time, leaving you vulnerable.
- Specific Risks: Depending on the agreement, coverage may extend to issues like zoning violations, boundary disputes, and even fraud. For example, in Idaho, homeowners have faced challenges related to boundary encroachments, which can complicate property ownership. Furthermore, it is crucial to recognize the possibility of fraud in ownership insurance, as this can greatly affect ownership rights.
It's crucial to understand if I should get owner's title insurance regarding my policy's specific terms. Coverage can vary widely between providers. In Nevada, for example, homeowners should be aware of the typical ownership defects that can occur, such as forged documents or improperly filed deeds. Furthermore, it is essential to verify that the company handling the documentation is licensed in your state to ensure that you are protected. Without adequate protection, you could face unexpected legal claims that threaten your investment. Remember to keep a copy of your ownership document and closing protection letter in a secure location, as these papers are essential for safeguarding your interests. Protecting your property isn't just smart; it's essential for safeguarding your financial future.
Evaluate Costs and Long-Term Value
Navigating the complexities of property ownership can be daunting, especially when unexpected challenges arise. The cost of homeowner's coverage varies based on several factors, including the property's acquisition price and location. On average, in California, Idaho, and Nevada, this cost typically ranges from 0.5% to 1% of the property's value. Here are key considerations when evaluating these costs:
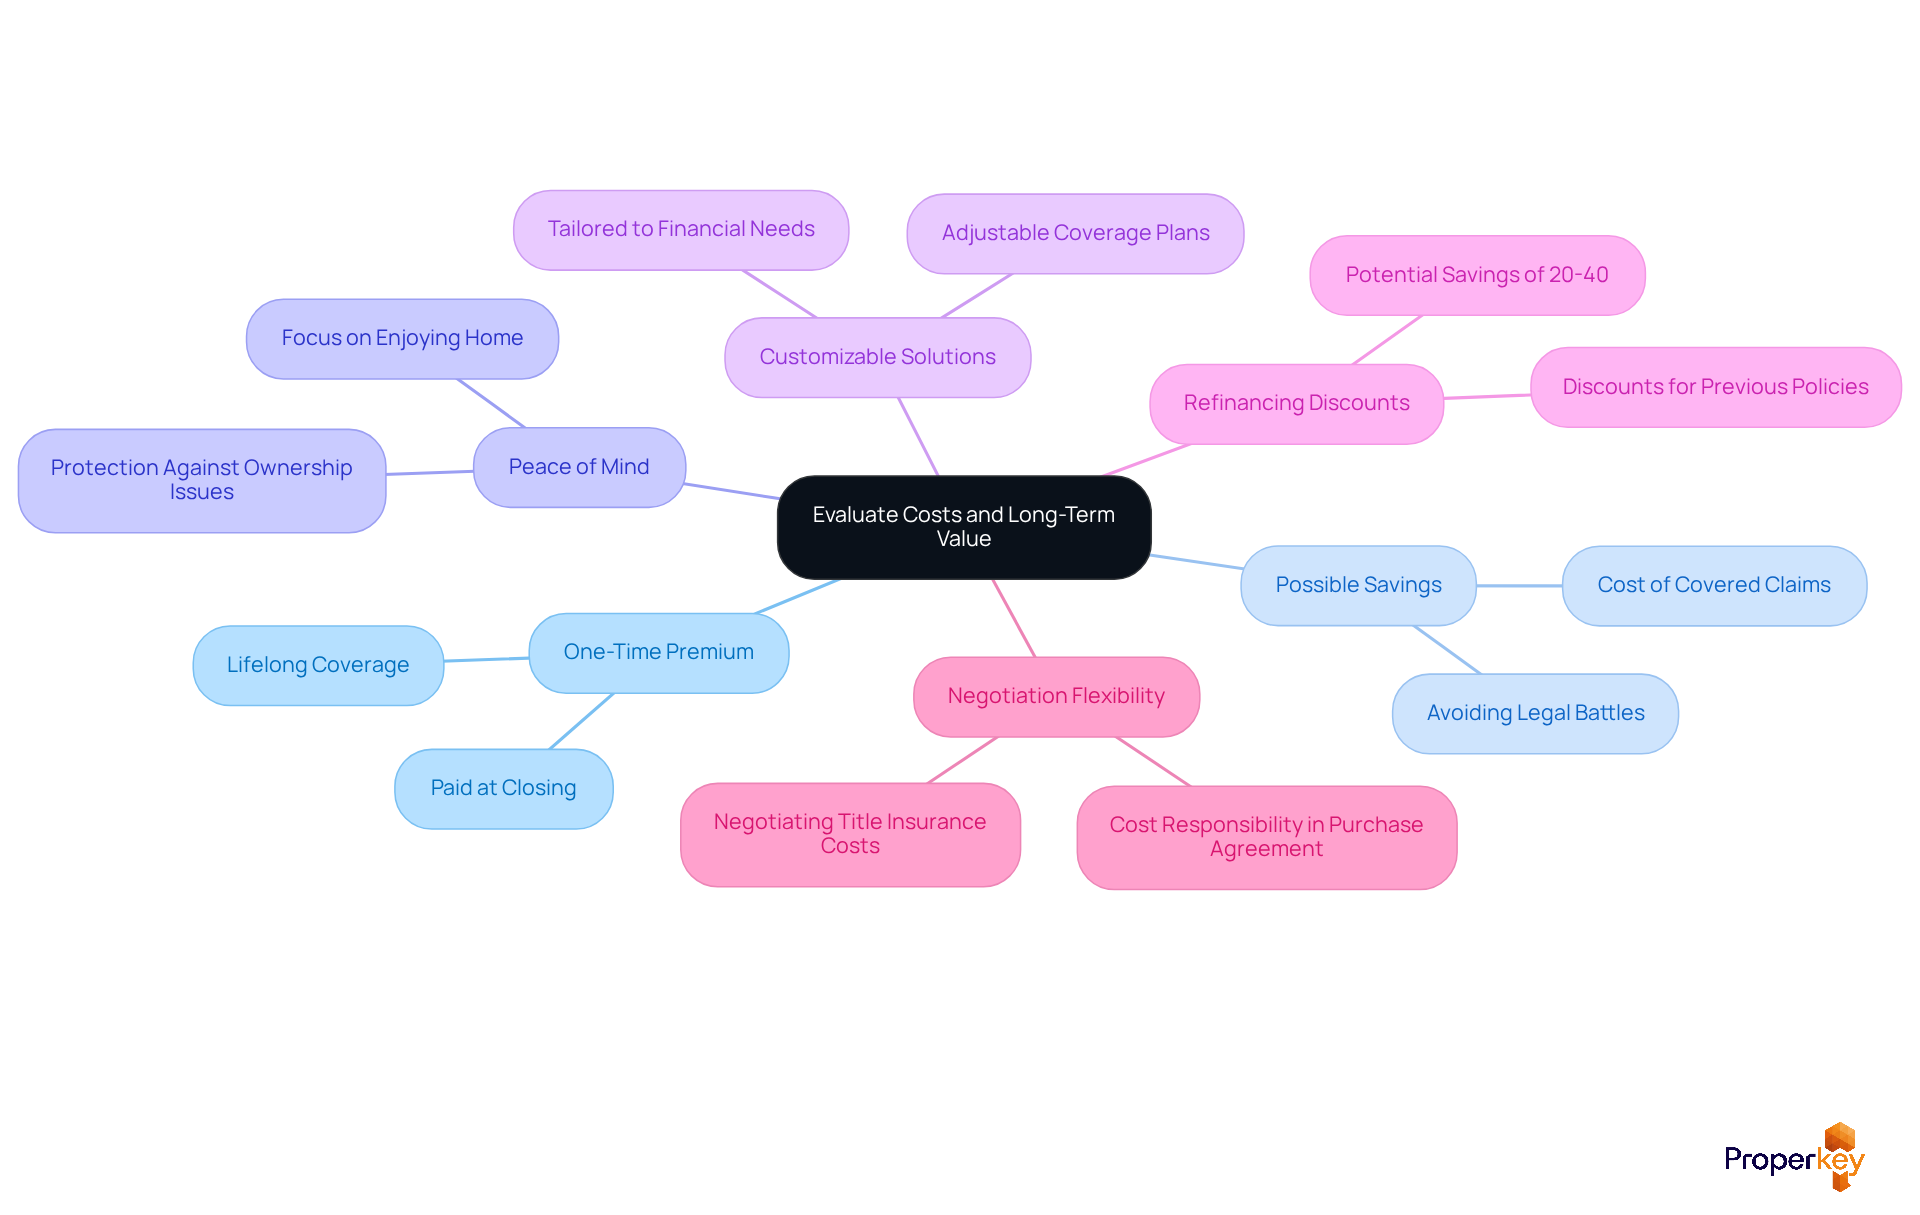
- One-Time Premium: Unlike other insurance policies that require ongoing monthly payments, owner's title insurance is a one-time fee paid at closing. This premium offers lifelong coverage for as long as you own the property, ensuring protection against potential ownership issues.
- Possible Savings: Imagine facing a costly legal battle over ownership that could have been avoided with proper coverage. In disputes, legal costs and potential decreases in property value can far exceed the initial premium. A single covered claim can cost tens of thousands of dollars to defend, making the initial investment in ownership protection a wise decision.
- Peace of Mind: Knowing you’re safeguarded against unexpected ownership problems can provide considerable peace of mind, especially for first-time homebuyers. The assurance that your ownership rights are protected allows you to focus on enjoying your new home without the worry of hidden claims.
- Vana's Customizable Solutions: Vana offers adjustable coverage plans tailored to your specific needs and financial considerations. This flexibility ensures you receive the protection that best safeguards your investment.
- Refinancing Discounts: If you’ve had a policy on the same property within the past 5 to 10 years, you may qualify for a discount when refinancing, potentially saving you 20% to 40% on the premium.
- Negotiation Flexibility: The responsibility for covering the cost of ownership protection can often be negotiated in the purchase agreement, allowing for flexibility in expenses related to ownership protection.
As you consider property protection, weigh the upfront costs against the potential risks and long-term benefits. This understanding is crucial for a successful real estate transaction.
Consult Professionals for Personalized Advice
Understanding the intricacies of owner's title insurance should I get owner's title insurance is crucial for home sellers, yet many find themselves overwhelmed by the details. Here are key steps to take:
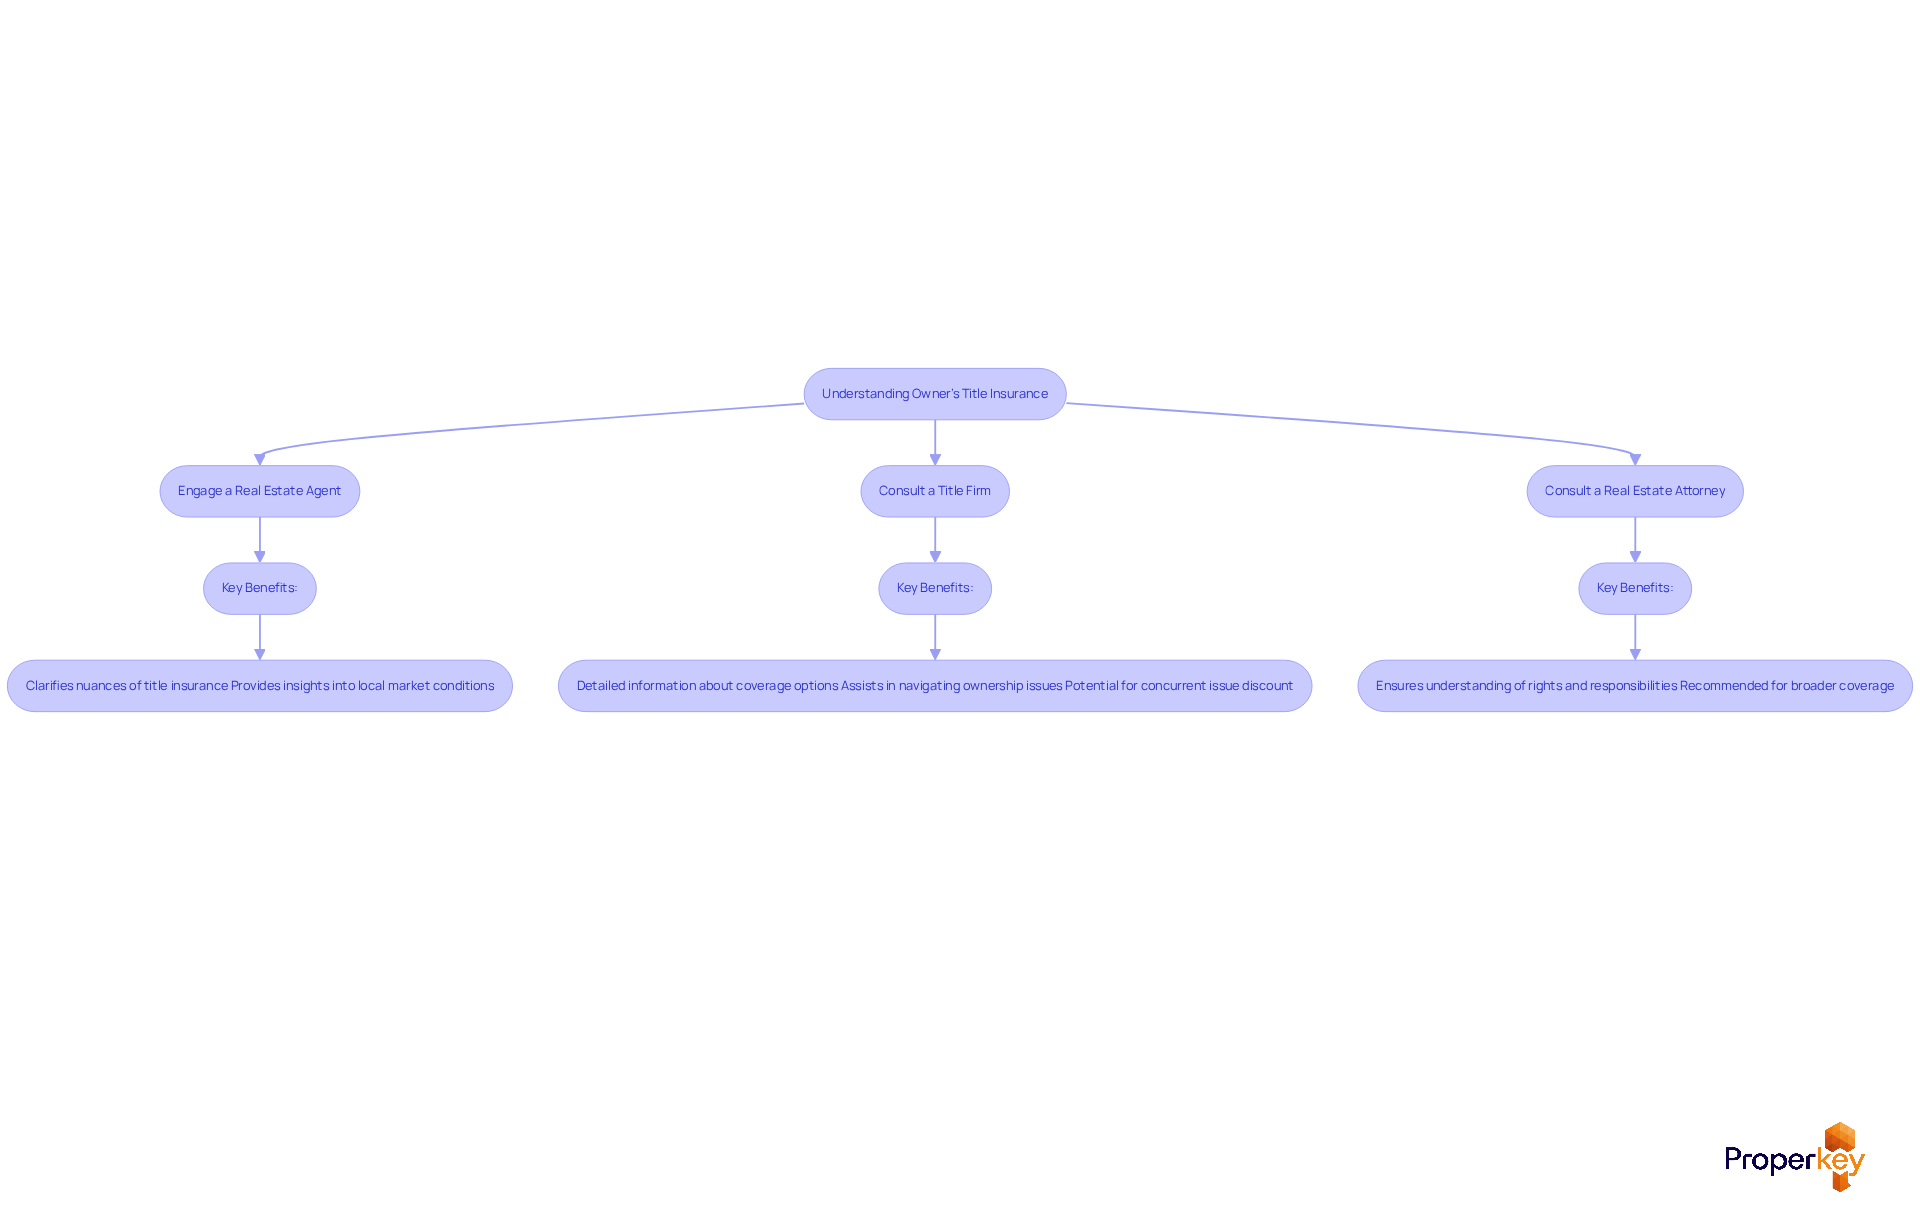
- Engage a Real Estate Agent: A knowledgeable agent can clarify the nuances of title insurance, helping you understand its significance in your specific transaction. They can also provide insights into local market conditions that may affect your decision. In California, Idaho, and Nevada, a significant percentage of homebuyers seek advice from real estate agents regarding property coverage, reflecting the importance of expert guidance in these transactions.
- Consult a Title Firm: These companies specialize in ownership-related insurance and can provide detailed information about coverage options, costs, and the claims process. They assist you in navigating the complexities of ownership issues that may arise during a transaction. When you issue both owner’s and lender’s policies together, you might qualify for a concurrent issue discount, helping to lower your overall costs. Vana offers extensive protection that adapts to your requirements, guaranteeing you obtain the most favorable rates and securing coverage prior to closing, along with combined services for escrow and closing.
- If you have concerns about potential ownership issues, you might be wondering, should I get owner's title insurance, and consulting a real estate attorney can provide additional peace of mind. They’ll make sure you fully understand your rights and responsibilities when it comes to protecting your ownership. Additionally, the ALTA Homeowner’s policy is recommended for most California homebuyers financing a primary residence due to its broader coverage.
By seeking professional advice, you can gain a clearer understanding of your options. With Vana's integrated services, you can streamline your real estate transaction and ensure your investment is well protected, leaving no room for uncertainty.
Conclusion
Are you aware of the hidden risks that could threaten your property investment? Understanding the importance of owner's title insurance is crucial for any homeowner looking to protect their investment. Owner's title insurance is a crucial safeguard. It protects against ownership disputes and hidden claims that could threaten your property rights. By securing owner's title insurance, homeowners can enjoy peace of mind knowing they are protected from unforeseen legal challenges that may arise after the purchase.
Throughout this guide, we've highlighted key points, including the various risks covered by owner's title insurance, such as:
- Unknown liens
- Fraudulent claims
- Errors in public records
It's also worth noting the cost-effectiveness of a one-time premium compared to the potential financial burden of legal disputes. Consulting professionals like real estate agents and title firms can provide valuable insights and personalized advice, ensuring that homeowners make informed decisions regarding their coverage.
Ultimately, investing in owner's title insurance is not just a smart financial move; it is an essential step in safeguarding one's property and future. Consider the benefits of this coverage carefully; the risks of going without it could be significant. By taking proactive measures to secure their ownership rights, individuals can focus on enjoying their homes without the looming threat of unexpected claims. By securing owner's title insurance, you not only protect your investment but also ensure a worry-free future in your home.
Frequently Asked Questions
What is owner's title insurance?
Owner's title insurance is a policy that protects homeowners from potential claims related to ownership issues, such as hidden claims and ownership disputes.
Why should I consider getting owner's title insurance?
Owner's title insurance serves as a safeguard against risks like unknown liens, fraudulent claims, and errors in public records that could affect your ownership of the property.
How does owner's title insurance differ from conventional insurance?
Unlike conventional insurance that requires continuous payments, owner's title insurance involves a one-time charge made at closing, providing lifetime security for the homeowner.
What risks does owner's title insurance protect against?
It protects against unknown liens, fraudulent claims of ownership, and errors in public records that could lead to disputes over property ownership.
How much does owner's title insurance typically cost?
In states like California, Idaho, and Nevada, the cost usually ranges from 0.5% to 1% of the home's purchase price, with California's average premium around $1,337.
What is the claim rate for owner's title insurance policies?
Only 3-5% of policy agreements result in claims, indicating that most homeowners can feel secure knowing their investment is well protected.
Can you provide an example of the importance of owner's title insurance?
A homeowner in California faced delays in closing due to undisclosed liens, which were identified by the documentation company. This allowed the seller to resolve the issues before completing the sale, demonstrating the value of ownership protection in facilitating smooth transactions.
List of Sources
- Understand Owner's Title Insurance Basics
- Title Insurance Protects Property Rights (https://alta.org/advocacy/protects)
- Title insurance: What you need to know (https://rocketmortgage.com/learn/title-insurance)
- How much is title insurance? Costs, fees and savings (https://rocketmortgage.com/learn/title-insurance-cost)
- Title Insurance Costs in 2026: 12 Things Buyers Need to Know Before You Close (https://amerisave.com/learn/title-insurance-costs-in-things-buyers-need-to-know-before-you-close)
- Exploring Title Insurance, Consumer Protection, and Opportunities for Potential Reforms (https://home.treasury.gov/news/featured-stories/exploring-title-insurance-consumer-protection-and-opportunities-for-potential-reforms)
- Identify Coverage and Protection Offered
- Title insurance is burning through homebuyers' pockets — and filling up their lawyers' (https://npr.org/2022/11/27/1139307743/title-insurance-is-burning-through-homebuyers-pockets-and-filling-up-their-lawye)
- Exploring Title Insurance, Consumer Protection, and Opportunities for Potential Reforms (https://home.treasury.gov/news/featured-stories/exploring-title-insurance-consumer-protection-and-opportunities-for-potential-reforms)
- The Vitals on Title Insurance: What you need to know (https://content.naic.org/article/consumer-insight-vitals-title-insurance-what-you-need-know)
- What is owner's title insurance? | Consumer Financial Protection Bureau (https://consumerfinance.gov/ask-cfpb/what-is-owners-title-insurance-en-164)
- Why Title Insurance Matters (https://oldrepublictitle.com/blog/why-title-insurance-matters)
- Evaluate Costs and Long-Term Value
- First American Warns Against Title Insurance Cuts (https://nationalmortgageprofessional.com/news/first-american-warns-against-title-insurance-cuts)
- How much is title insurance? 805title’s Trusted Advice (https://805title.com/title-insurance-cost-guide)
- How much is title insurance? Costs, fees and savings (https://rocketmortgage.com/learn/title-insurance-cost)
- Industry News (https://alta.org/news-and-publications/industry-news)
- Consult Professionals for Personalized Advice
- Industry News (https://alta.org/news-and-publications/industry-news)
- How much is title insurance? 805title’s Trusted Advice (https://805title.com/title-insurance-cost-guide)
- Our Blog | Title Underwriters | Conestoga Title (https://conestogatitle.com/blog)
- Looking Ahead: What 2026 May Hold for Title Insurance, Real Estate and the Built World (https://linkedin.com/pulse/looking-ahead-what-2026-may-hold-title-insurance-real-dpf1c)


