How to Get a $400K Mortgage: 4 Essential Steps to Follow

Introduction
Securing a $400K mortgage can feel like navigating a maze, with numerous twists and turns that can easily overwhelm even the most determined buyers. To successfully navigate this process, buyers must understand the intricacies of:
- Income requirements
- Down payment options
- Monthly payment calculations
Yet, many buyers feel overwhelmed by the many factors that can affect mortgage approval. So, what steps do you need to take to secure that $400K mortgage and meet all the necessary requirements?
Determine Your Required Income for a $400K Mortgage
Navigating the complexities of mortgage requirements can be overwhelming for many home sellers, but knowing how to get a 400k mortgage is crucial for success. Here’s how to determine what you need:
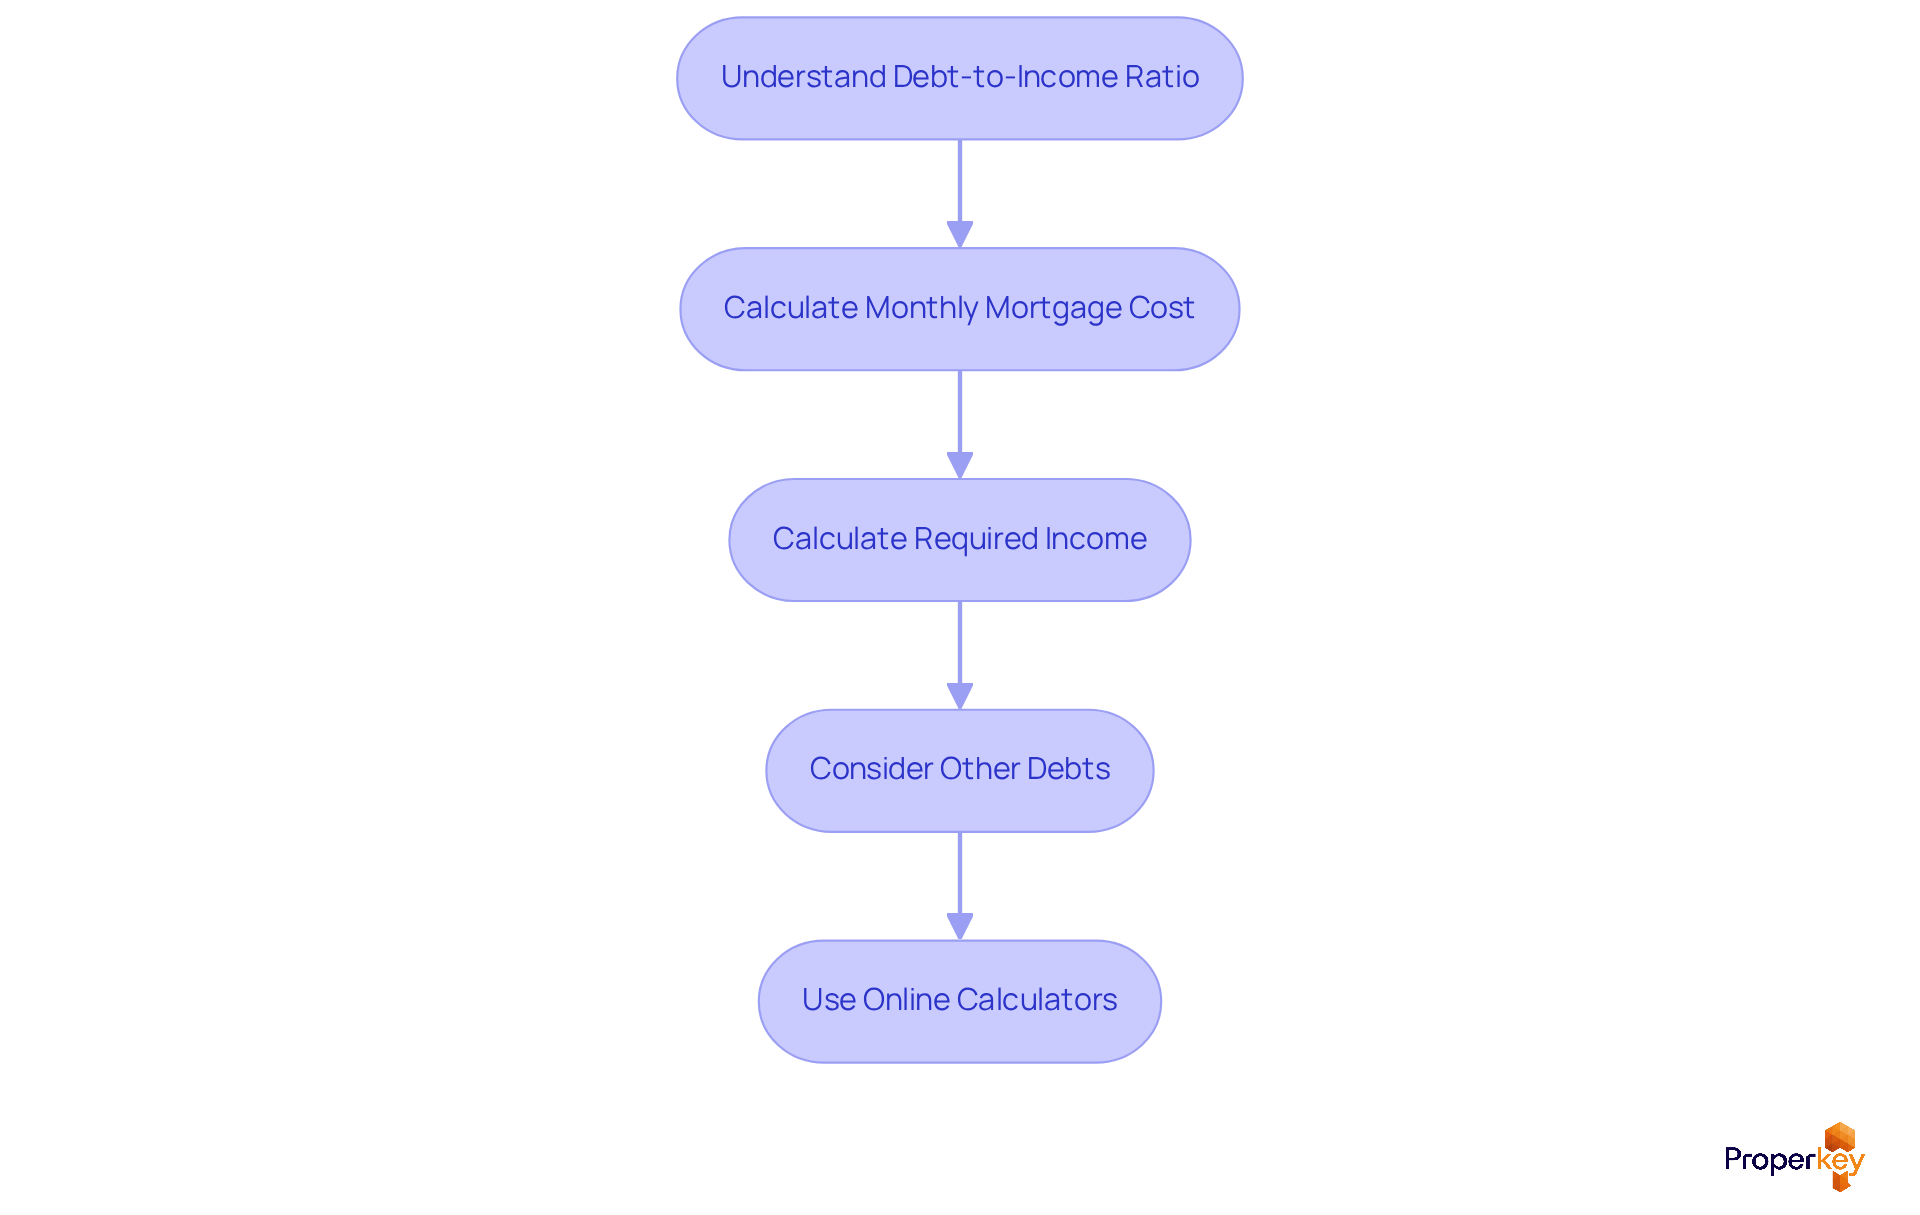
- Understand the Debt-to-Income Ratio (DTI): Most lenders like to see a DTI ratio of 43% or lower, and many aim for 36% to offer you the best terms. This means your total monthly debt obligations, including the mortgage, should not exceed 36% of your gross income.
- Calculate Monthly Mortgage Cost: For a $400K mortgage, you’ll want to estimate your recurring charge. At a 6.5% interest rate over 30 years, your principal and interest payment would be around $2,528. When you add property taxes and insurance, which can range from $500 to $800 each month, your total monthly payment could be approximately $3,200.
- Calculate Required Income: To understand how to get a 400k mortgage, simply divide your total housing costs by 0.36. For instance, if your total monthly payment is $3,200, you would need a gross monthly income of about $8,889, translating to an annual income of $106,667.
- Consider Other Debts: If you have additional obligations, like car loans or student debts, make sure to factor these into your DTI calculation. Adjust your required income accordingly to stay within that 36% threshold.
- Use online calculators on financial websites to input your specific numbers, which will help you understand how to get a 400k mortgage by providing a tailored estimate of the income required. Additionally, consider using Loanvana's financing tool, which allows you to apply once and compare hundreds of loan options side-by-side from multiple lenders. This can help you visualize your financial situation and make informed choices about your loan options.
Explore Down Payment Options for a $400K Mortgage
Understanding how to get a 400k mortgage in California can be daunting, especially when navigating down payment options. Here’s a breakdown of the various avenues you can explore:
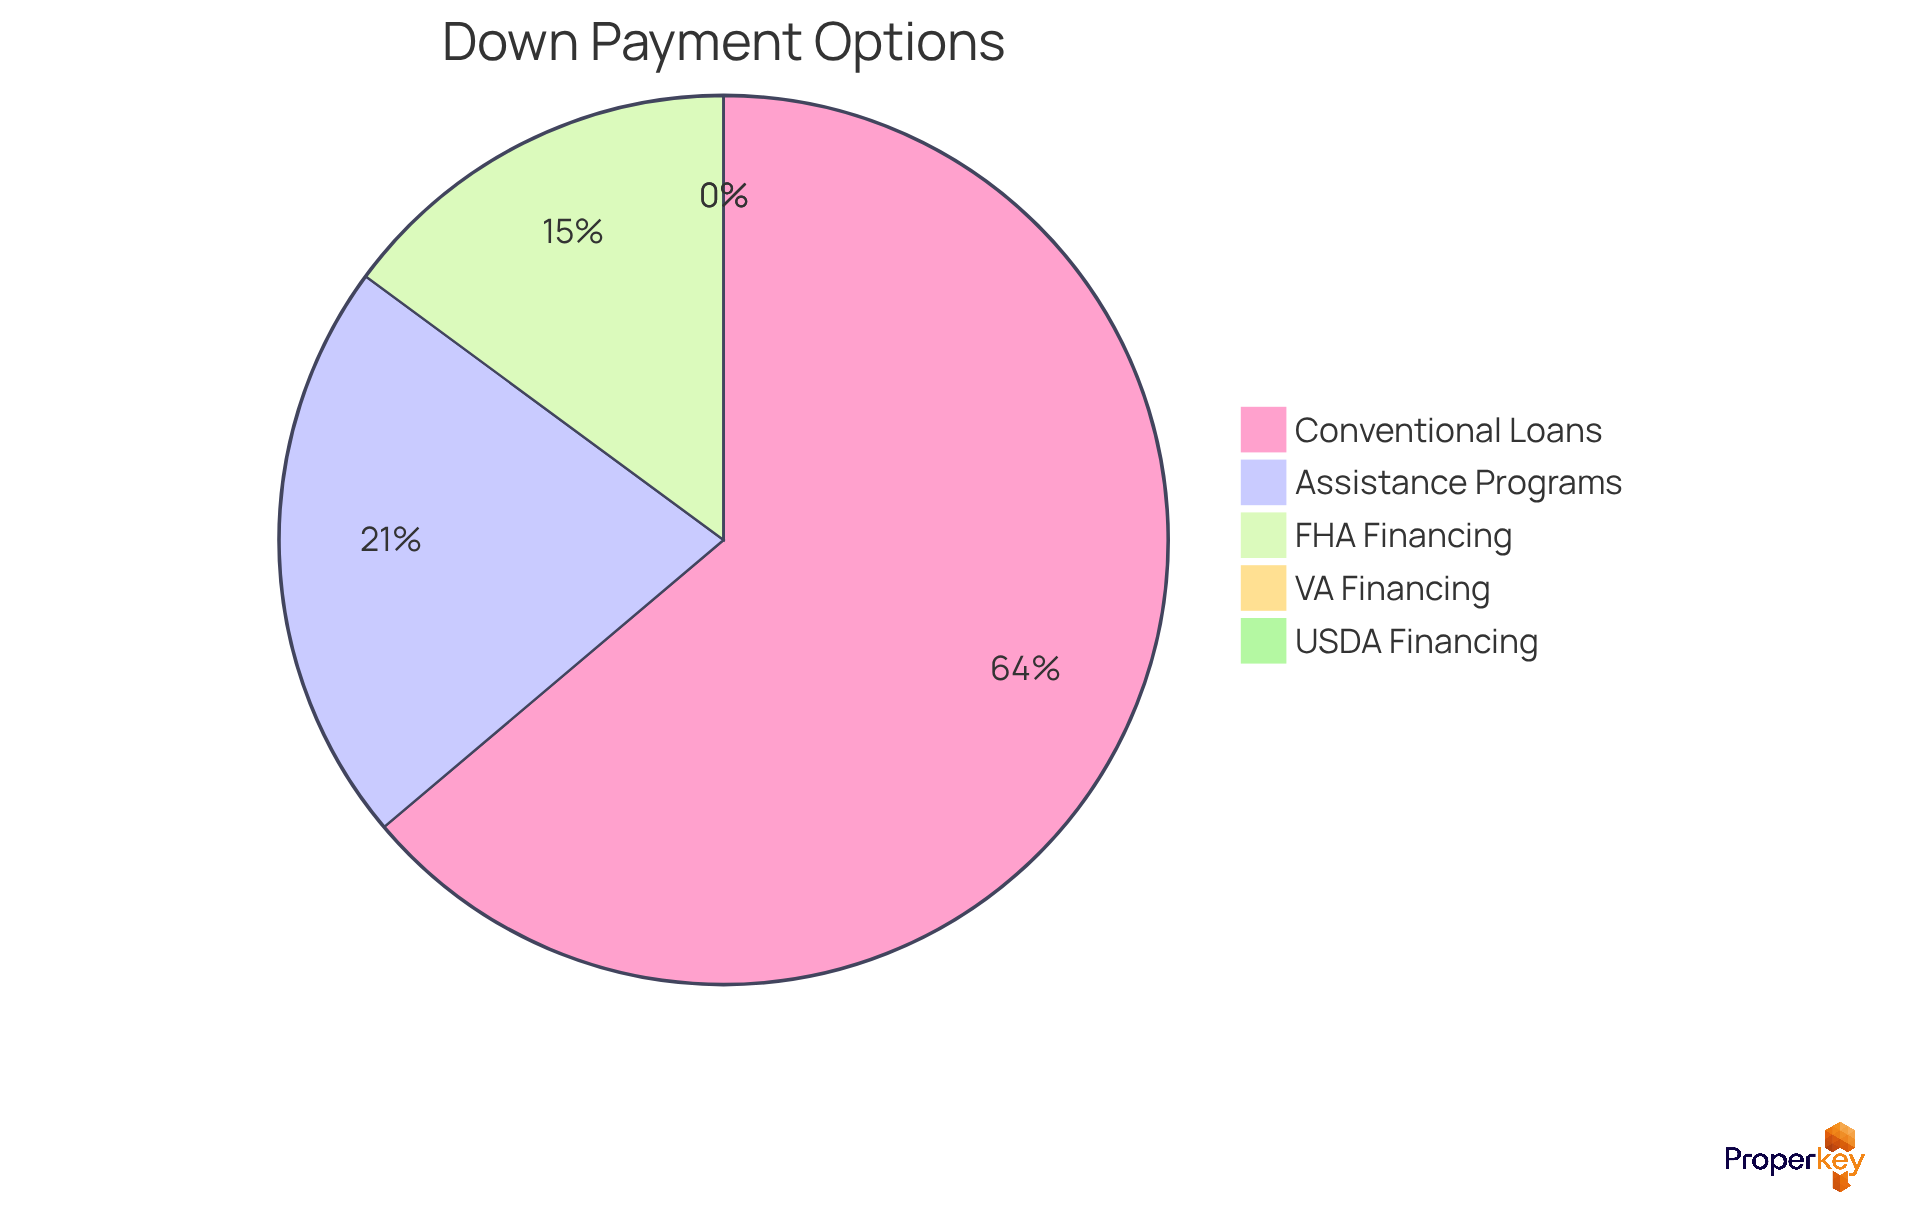
- Conventional Loans: These loans typically require a down payment ranging from 5% to 20%. For a $400K home, that translates to a down payment of $20,000 to $80,000. Opting for a larger initial deposit can help you avoid private mortgage insurance (PMI), which can add to your monthly expenses.
- FHA Financing: Designed for first-time homebuyers, FHA financing allows for a lower down payment, often as low as 3.5%. This means you could put down just $14,000 on a $400K home, which is an enticing prospect for many first-time buyers who are learning how to get a 400k mortgage. However, keep in mind that FHA loans come with insurance premiums that can increase your monthly costs over time.
- VA Financing: If you’re a veteran or an active-duty service member, you may qualify for VA financing, which often requires no down payment. This option can significantly reduce your upfront costs, making homeownership more accessible. For more details on VA financing, visit the VA portal, which offers essential resources for veterans.
- USDA Financing: For those looking to buy in qualifying rural areas, USDA financing offers 0% down options. This is particularly advantageous for buyers focused on rural properties, allowing them to enter the housing market without the burden of an initial deposit.
- Down Payment Assistance Programs: Investigate local and state down payment assistance programs that can provide grants or loans to help cover your upfront costs. These programs can greatly alleviate the financial strain of homeownership, making it more attainable for first-time buyers. Additionally, HUD guidelines can offer valuable insights into available assistance options.
- Gift Funds: If you have family members willing to assist, you can utilize gift funds for your down payment. Just ensure you document these funds properly to meet lender requirements, as this can be a valuable resource for many buyers.
In California, the average down payment for first-time homebuyers in 2026 is expected to be around 9%, with many utilizing assistance programs to bridge the gap. By understanding these options and planning accordingly, you can significantly reduce your financial burden and make homeownership a reality, transforming your aspirations into achievable goals.
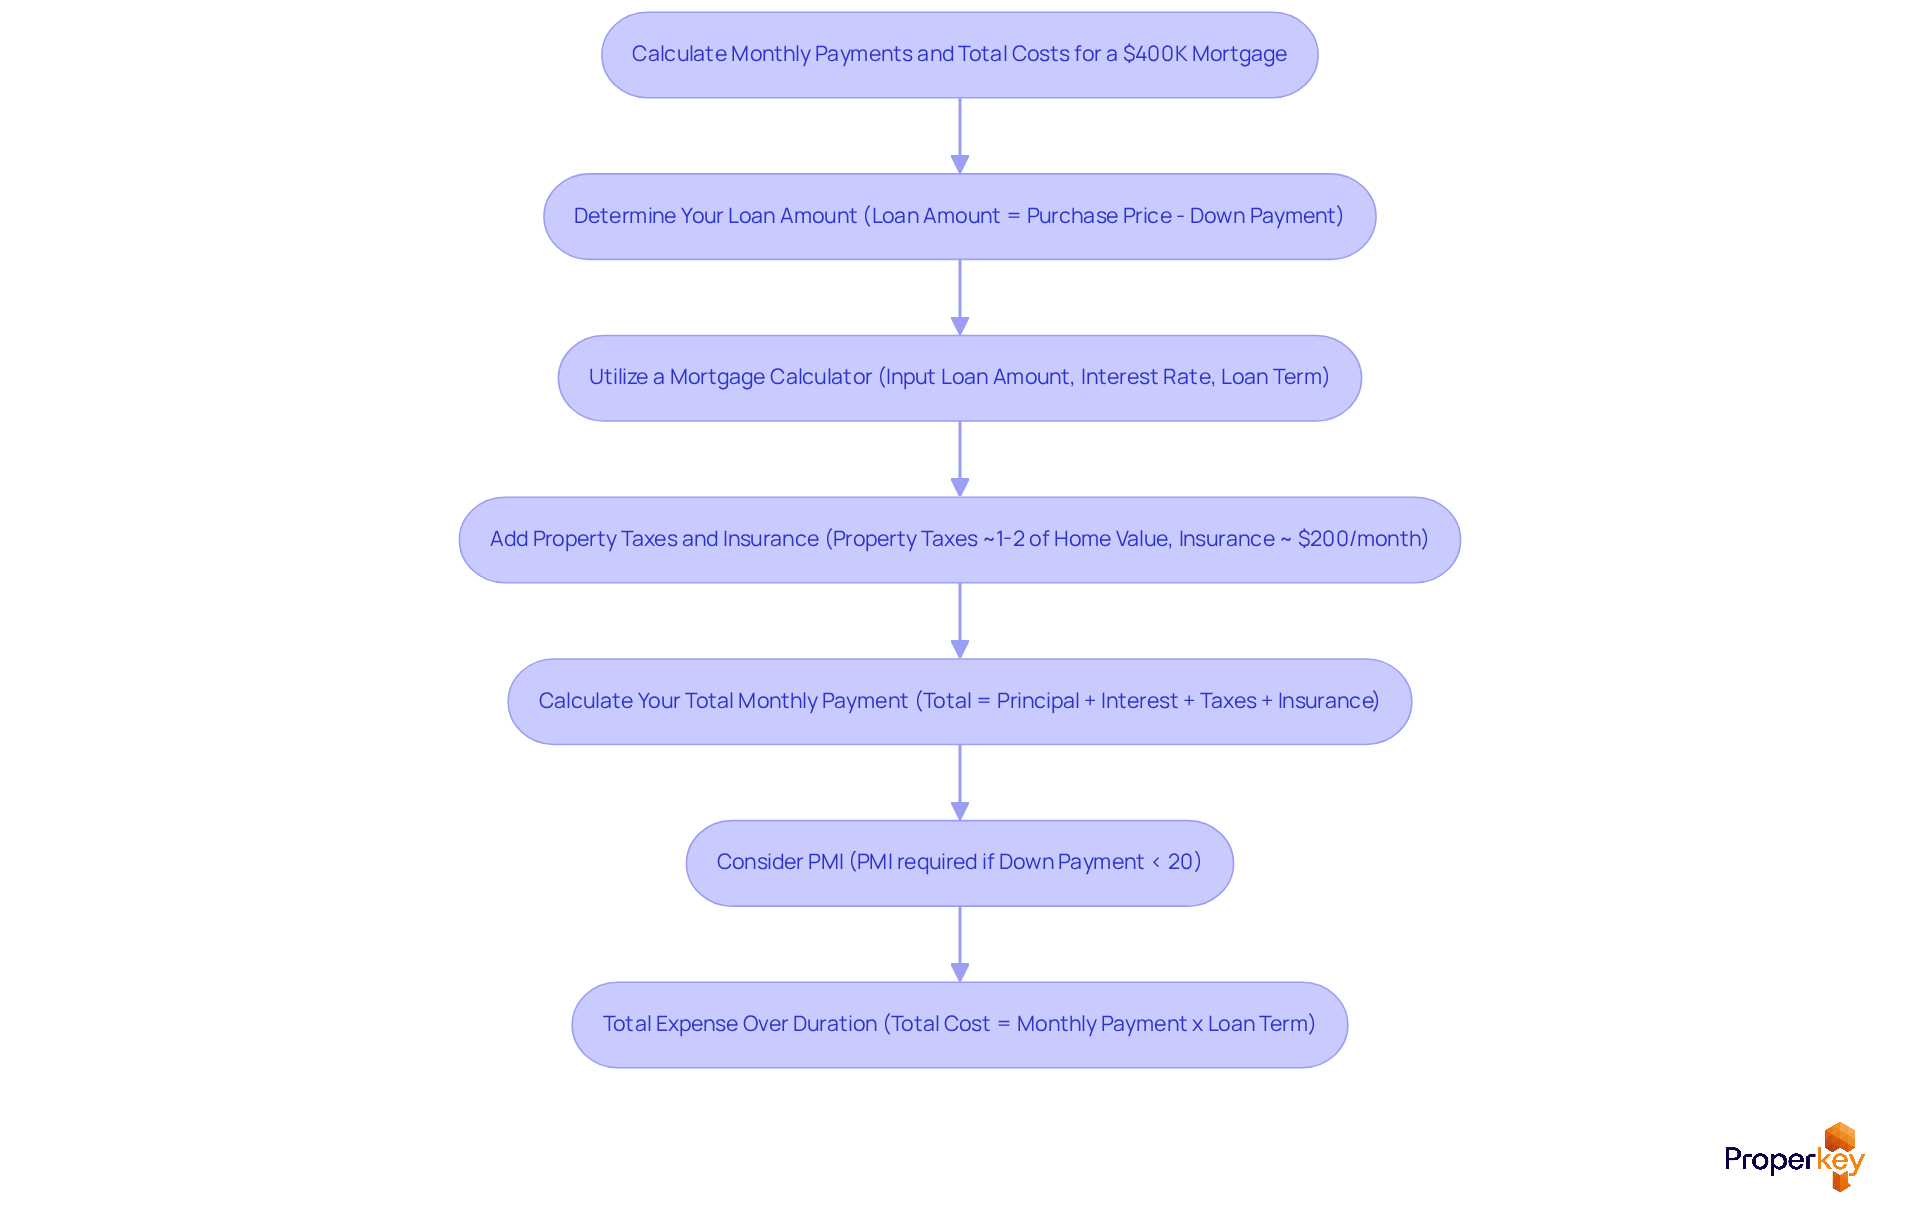
Calculate Monthly Payments and Total Costs for a $400K Mortgage
Navigating the intricacies of mortgage payments can be overwhelming for many home sellers, but understanding the process is crucial for making informed decisions. Here’s how to calculate your monthly payments and total costs for a $400K mortgage:
- Determine Your Loan Amount: Start by subtracting your down payment from the purchase price to understand your borrowing capacity. For instance, if you contribute 20% ($80,000), your borrowing amount would be $320,000.
- Utilize a Mortgage Calculator: Input your borrowing amount, interest rate, and loan term into a mortgage calculator to get a clearer picture of your monthly obligations. For a $320,000 loan at a 6% interest rate over 30 years, your principal and interest payment would be approximately $1,919 to $2,326.
- Add Property Taxes and Insurance: Don’t forget to factor in property taxes, which usually range from 1% to 2% of your home’s value each year. When considering how to get a 400k mortgage, it's important to note that property taxes for a $400K home could be around $4,400 annually, or about $367 per month. Additionally, homeowners insurance might add another $200 each month, bringing the total insurance cost to about $2,400 yearly.
- Calculate Your Total Monthly Payment: Combine your principal, interest, property taxes, and insurance to get your total monthly obligation. Using the previous example, your total charge for the month would be approximately $2,586 ($1,919 + $367 + $200).
- Consider PMI: If your down payment is less than 20%, you’ll need to account for Private Mortgage Insurance (PMI), which can add to your monthly costs, varying from $158 to $317 depending on your loan amount and lender.
- Total Expense Over Duration: To grasp the full cost of your loan, multiply your monthly payment by the total number of months in your loan term (360 months for a 30-year loan). For a total monthly payment of $2,586, the total cost over 30 years would be approximately $930,960.
By mastering these calculations, you can avoid unexpected financial burdens and confidently move forward in your home-selling journey.
Follow Steps to Apply for a $400K Mortgage
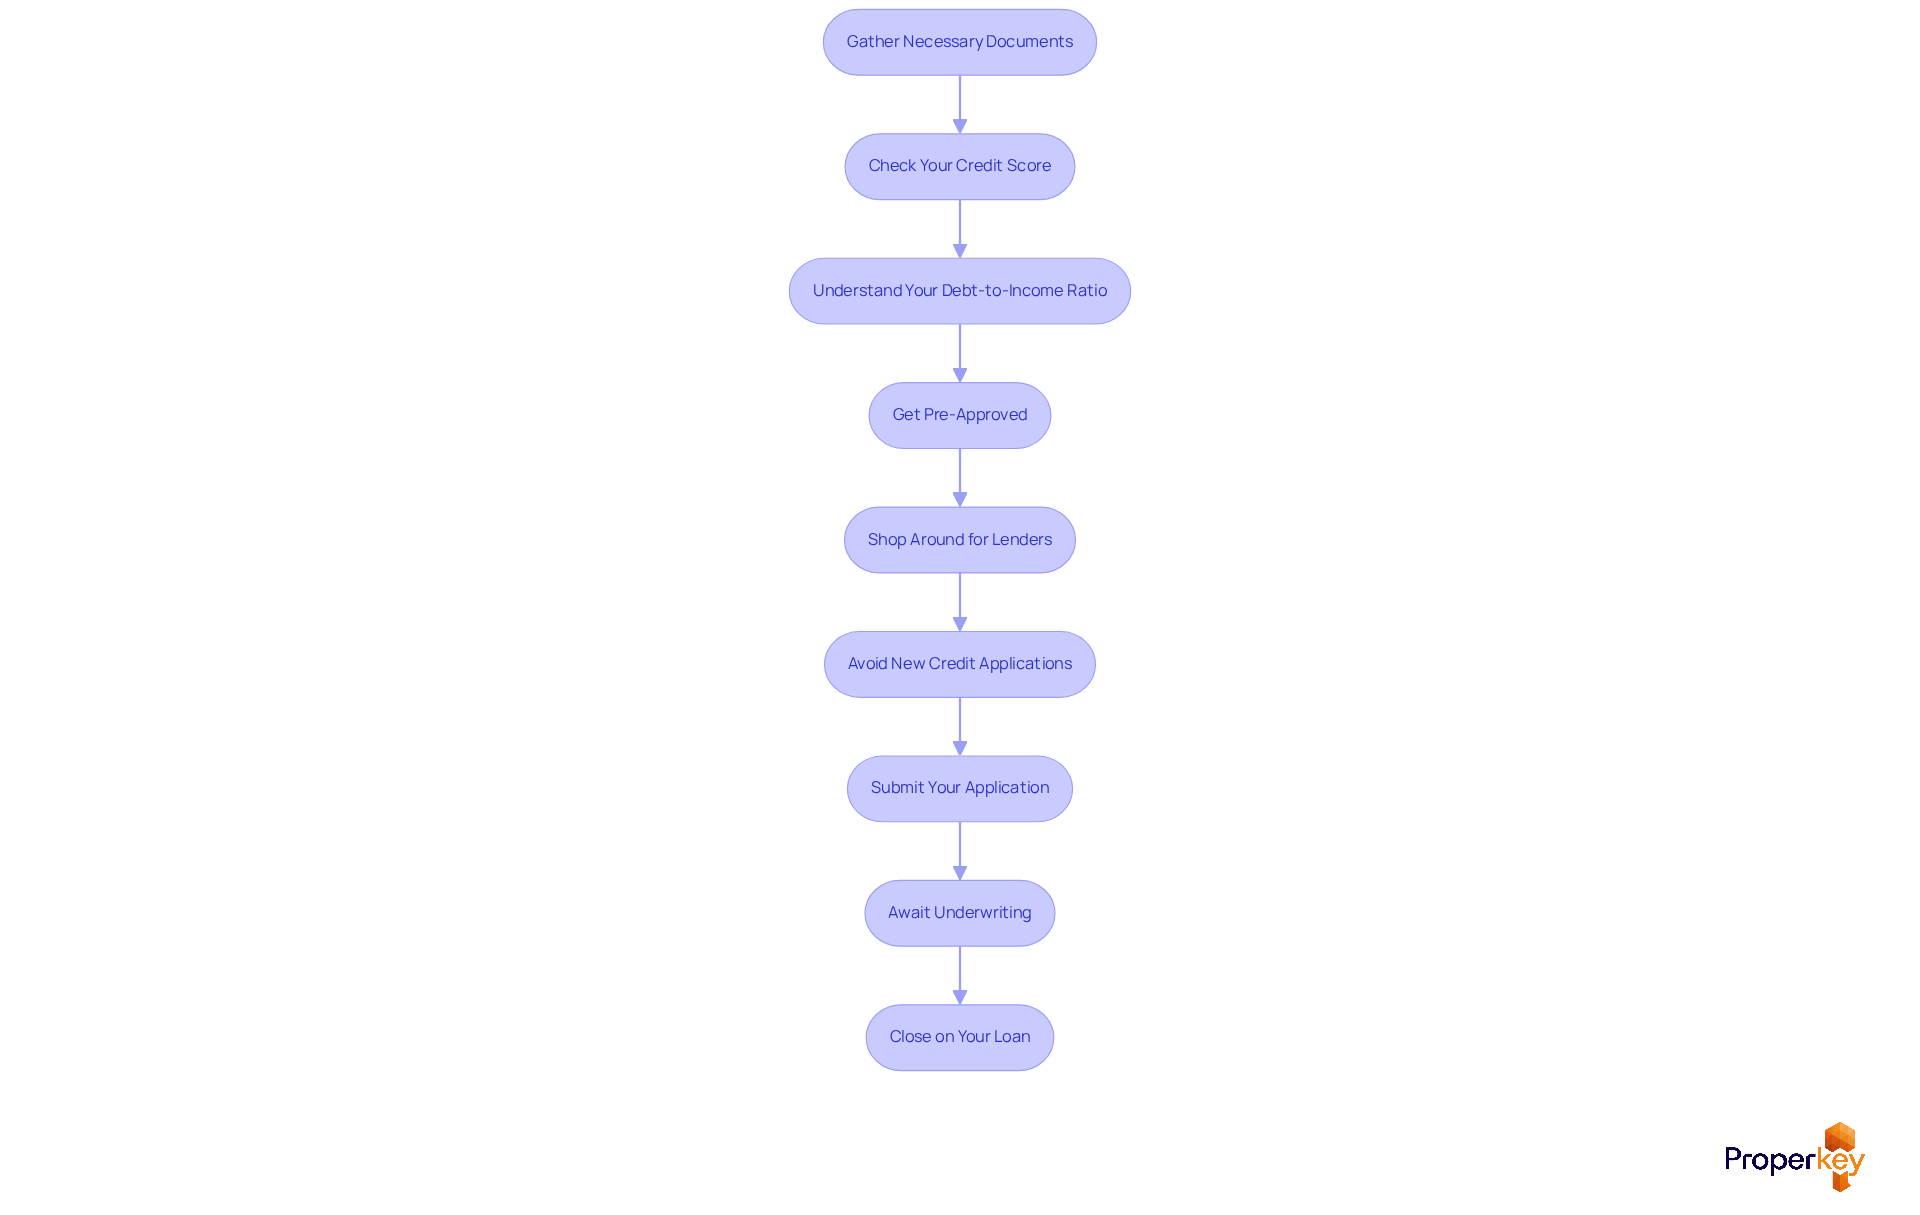
To apply for a $400K mortgage, follow these essential steps:
- Gather Necessary Documents: Prepare your financial documents, including W-2s, tax returns, bank statements, and proof of income. Lenders require these to assess your financial situation and determine your eligibility.
- Check Your Credit Score: Obtain your credit report and check your score. Aim for a score of at least 620 to qualify for most conventional loans. If your score is lower, consider strategies to improve it, such as paying down existing debt or disputing inaccuracies on your credit report. Remember, a higher credit score can assist you in qualifying for a more competitive loan rate.
- Understand Your Debt-to-Income Ratio: Lenders typically prefer a debt-to-income (DTI) ratio of 36% or lower, with housing costs under 28%. This ratio is crucial for determining your ability to manage monthly payments alongside your existing debts.
- Get Pre-Approved: Approach lenders to obtain a loan pre-approval. This process involves submitting your financial documents and allowing the lender to evaluate your creditworthiness. A pre-approval letter not only strengthens your position when making an offer on a home but also clarifies your budget constraints. With Properkey, you can benefit from expert guidance and full MLS exposure, ensuring you have the best options available.
- Shop Around for Lenders: Compare loan rates and terms from various lenders. Look for the best interest rates and fees to ensure you secure the most favorable terms for your loan. Loanvana simplifies this process by allowing you to apply once and compare hundreds of loan options side-by-side from multiple lenders, making it easier to find the right fit for your needs.
- Avoid New Credit Applications: During the loan application process, refrain from applying for new credit or making significant purchases. This can adversely affect your credit score and DTI ratio, potentially endangering your loan approval.
- Submit Your Application: Once you choose a lender, submit your loan application along with all necessary documentation. Be prepared to answer any additional questions the lender may have during this process.
- Await Underwriting: After submission, your application will undergo underwriting, where the lender verifies your information and assesses the risk of lending to you. You might find that this process takes anywhere from a few days to a few weeks.
- Close on Your Loan: If approved, you will receive a closing disclosure detailing your loan terms. Examine it thoroughly, then participate in the concluding meeting to sign the final documents and secure your loan.
Navigating the mortgage application process can feel overwhelming, especially in a competitive market. As of November 2025, the median home sale price in California was $725,000. Understanding how to get a 400k mortgage is critical for potential buyers. With Properkey's dedicated local agents, you have a single point of contact throughout your home buying journey, ensuring a smooth and efficient experience. With the right preparation, you can secure your dream home and thrive in California's competitive market.
Conclusion
Navigating the complexities of securing a $400K mortgage can feel overwhelming for many prospective homebuyers. Follow these steps to prepare for the financial commitment of homeownership and make informed decisions with confidence.
Key insights include:
- Determining the required income based on debt-to-income ratios
- Exploring various down payment options
- Accurately calculating monthly payments and total costs
Additionally, the mortgage application process becomes smoother with careful preparation of necessary documents and obtaining pre-approval, significantly enhancing your position in a competitive market.
This journey to obtaining a $400K mortgage is not just about meeting financial requirements; it’s about empowering you to take control of your homeownership dreams. With the right resources and a solid understanding of mortgage financing, you can confidently take the first steps toward homeownership and turn your dreams into reality.
Frequently Asked Questions
What is the Debt-to-Income Ratio (DTI) and why is it important for a mortgage?
The Debt-to-Income Ratio (DTI) is a measure that compares your total monthly debt obligations to your gross monthly income. Most lenders prefer a DTI ratio of 43% or lower, with many aiming for 36% to offer the best terms. This means your total monthly debts, including the mortgage, should not exceed 36% of your gross income.
How do I calculate the monthly mortgage cost for a $400K mortgage?
For a $400K mortgage at a 6.5% interest rate over 30 years, the principal and interest payment would be approximately $2,528. When adding property taxes and insurance, which can range from $500 to $800 each month, the total monthly payment could be around $3,200.
How can I determine the required income for a $400K mortgage?
To determine the required income for a $400K mortgage, divide your total housing costs by 0.36. For example, if your total monthly payment is $3,200, you would need a gross monthly income of about $8,889, which translates to an annual income of approximately $106,667.
What should I consider if I have other debts when applying for a mortgage?
If you have additional debts, such as car loans or student loans, you should factor these into your DTI calculation. Adjust your required income accordingly to ensure you stay within the 36% threshold for a favorable mortgage application.
Are there tools available to help calculate mortgage requirements?
Yes, you can use online calculators on financial websites to input your specific numbers for a tailored estimate of the income required for a $400K mortgage. Additionally, tools like Loanvana's financing tool allow you to apply once and compare multiple loan options side-by-side from various lenders.
List of Sources
- Determine Your Required Income for a $400K Mortgage
- Debt-to-Income Ratios | Fannie Mae (https://selling-guide.fanniemae.com/sel/b3-6-02/debt-income-ratios)
- What Income Do You Need To Afford A $400k House? (https://lower.com/mortgages/what-income-do-you-need-to-afford-a-400k-house)
- Debt-to-Income Ratio: What It Means for Your Mortgage in 2026 (https://amerisave.com/glossary/debttoincome-ratio-what-it-means-for-your-mortgage-in)
- What Is the Income Needed for a $400k House? (https://redfin.com/blog/income-needed-for-a-400k-mortgage)
- Here's how much you need to make to afford a $400,000 house today | Fortune (https://fortune.com/article/how-much-income-do-you-need-to-afford-400k-home)
- Explore Down Payment Options for a $400K Mortgage
- Down payments are at a record high: Here’s where buyers pay the most (https://krqe.com/news/national/down-payments-are-at-a-record-high-heres-where-buyers-pay-the-most)
- What's the Actual Down Payment on a House in 2026? (Data-Backed Reality Check) (https://amerisave.com/learn/what-s-the-actual-down-payment-on-a-house-data-backed-reality-check)
- Best Low Down Payment Loan Options in 2026 (https://lower.com/mortgages/best-low-down-payment-loan-options)
- FHA Down Payment Assistance Programs | 2026 Guide (https://neighborsbank.com/learn/fha-down-payment-assistance)
- How Much Is a Down Payment on a $400k House? (https://zillow.com/learn/how-much-down-payment-for-400k-house)
- Calculate Monthly Payments and Total Costs for a $400K Mortgage
- What is the monthly mortgage payment on a $400,000 house? (https://finance.yahoo.com/personal-finance/mortgages/article/mortgage-payment-on-400k-203127288.html)
- Mortgage Payment on a $400,000 House: Monthly Cost Breakdown (https://opendoor.com/articles/mortgage-payment-on-400k-house)
- How Much Is a Mortgage on a $400k House? (https://zillow.com/learn/how-much-is-a-mortgage-on-a-400k-house)
- How much does a $400,000 mortgage loan cost each month after the Fed's October rate cut? (https://cbsnews.com/news/how-much-does-a-400000-mortgage-loan-cost-monthly-after-the-feds-october-rate-cut)
- This would be your monthly mortgage payment for a $400,000 home (https://cbsnews.com/news/this-would-be-your-monthly-mortgage-payment-for-a-400000-home)
- Follow Steps to Apply for a $400K Mortgage
- The Definitive Guide on How to Qualify for a Mortgage in California for 2026 (https://accreditedschools.com/how-to-qualify-for-a-mortgage-in-california)
- Documents Needed For Mortgage Preapproval | Bankrate (https://bankrate.com/mortgages/documents-for-preapproval)
- A Complete Checklist of Documents Needed for a Mortgage (https://money.usnews.com/loans/mortgages/articles/a-complete-checklist-of-documents-needed-for-a-mortgage)
- California First-Time Homebuyer Guide 2026 | New American Funding (https://newamericanfunding.com/learning-center/guides/california-first-time-homebuyer-guide)
- How to Get Approved for a Mortgage in CA - Potempa Team at CrossCountry Mortgage (https://potempateam.com/how-to-get-approved-for-a-mortgage-in-ca)