What's the Average Closing Cost on a House Compared to Other Expenses?
Introduction
Navigating the financial landscape of home buying can be daunting, especially when it comes to the hidden costs that can catch buyers off guard. Understanding these costs is crucial for any buyer looking to maintain control over their budget.
Closing costs, often overlooked, can significantly impact a buyer's finances. These expenses range from loan origination fees to title insurance and can vary widely based on location and property value. Many buyers underestimate the financial burden of closing costs, leading to unexpected challenges. This lack of awareness can result in budget overruns and stress during the home buying process.
This article delves into the average closing costs associated with purchasing a home, offering insights and strategies to manage these financial obligations effectively. Understanding these costs is not just beneficial; it’s essential for a smooth and successful home buying experience.
Define Closing Costs: Understanding the Basics
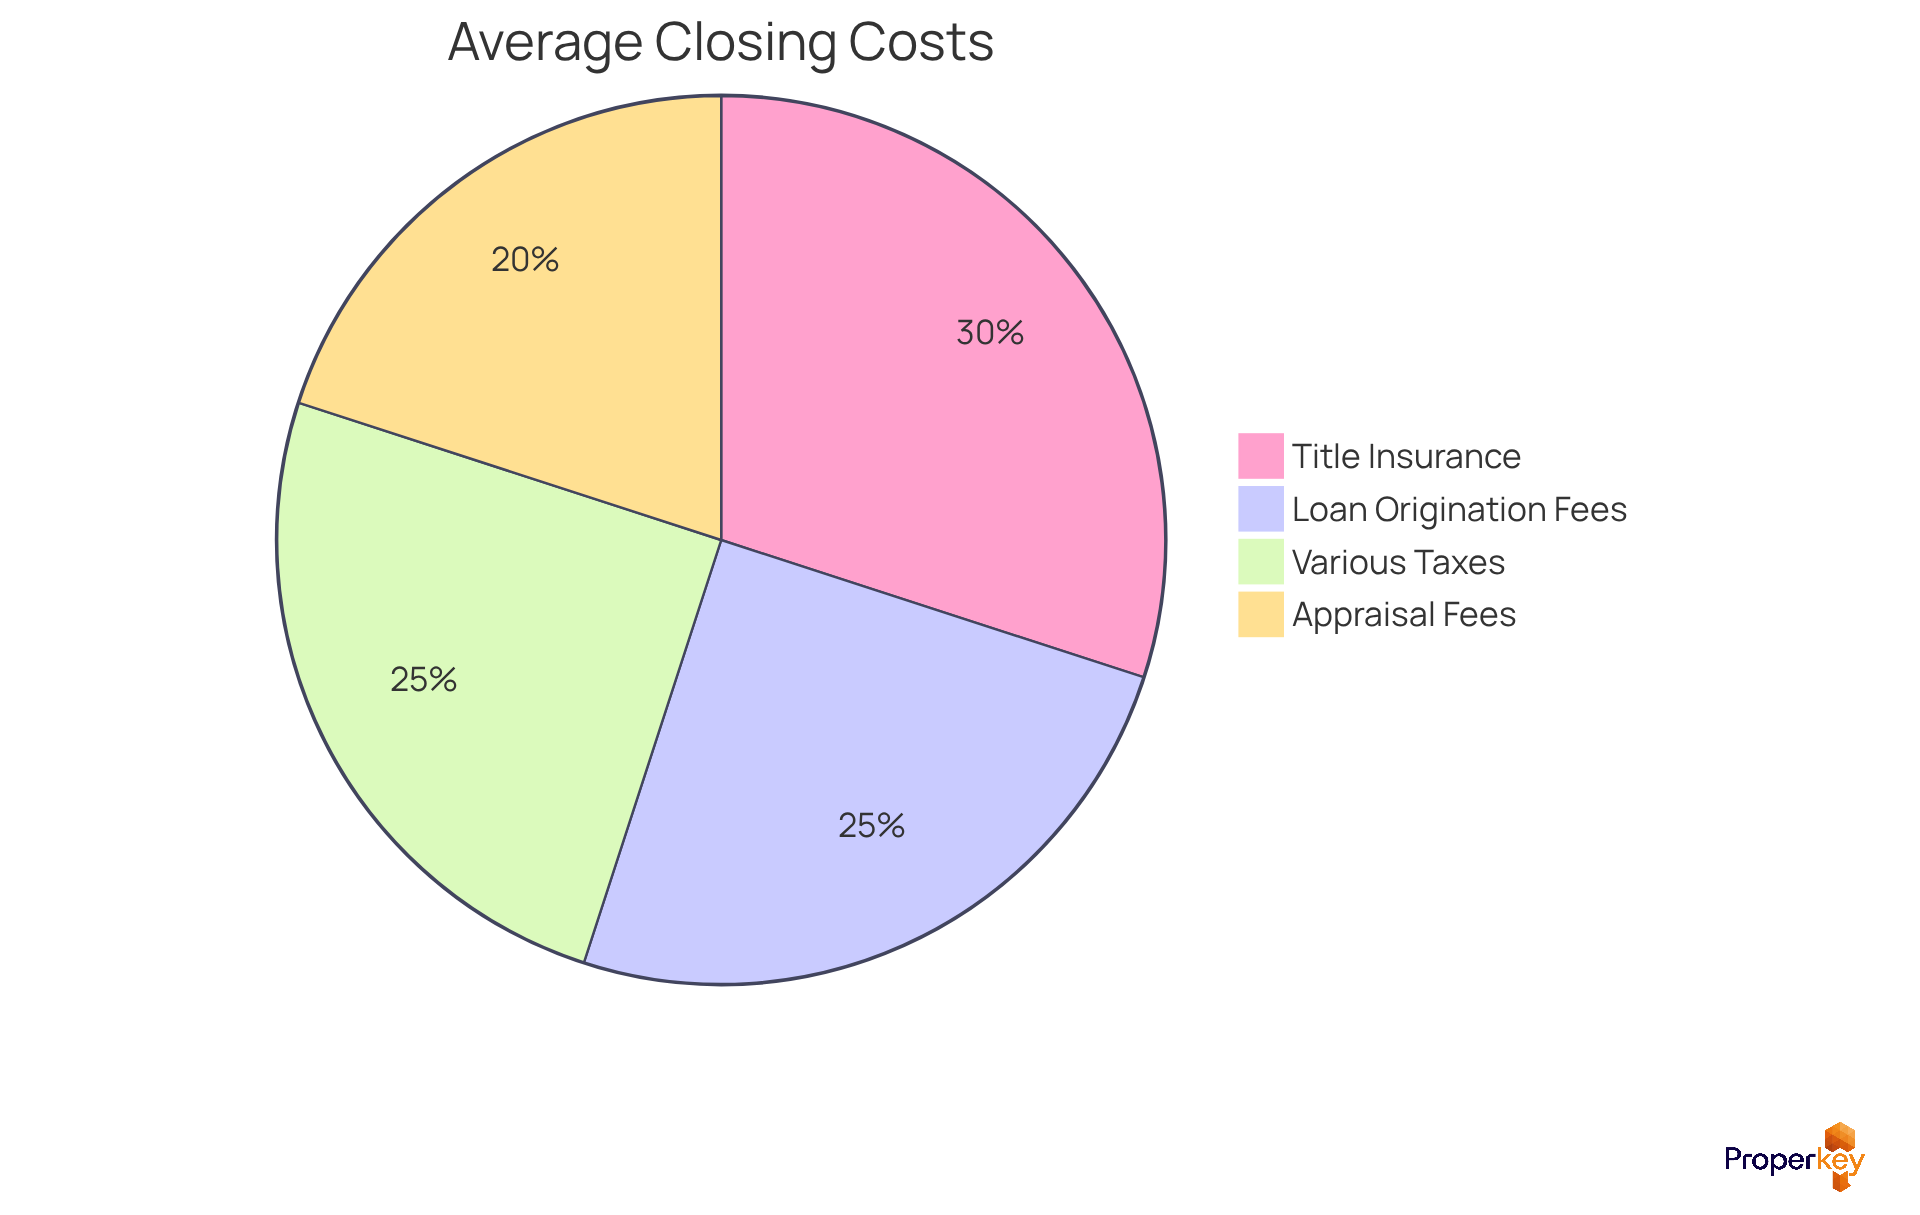
For home sellers, understanding what's the average closing cost on a house is crucial, as these fees can significantly impact their financial planning. When discussing closing charges, many people wonder what's the average closing cost on a house, as these include the various fees and expenses incurred by buyers and sellers during the completion of a real estate transaction. In California, Idaho, and Nevada, what's the average closing cost on a house usually falls between 2% to 5% of the home's purchase price. This variation reflects local market conditions and regulations. For instance, California's typical final expenses hover around $5,500, influenced by elevated property values but a comparatively low transfer tax rate. In contrast, Nevada purchasers can expect final expenses to vary from 2% to 3% of the purchase price, which translates to approximately $10,000 to $15,000 on a $500,000 residence.
Typical elements of final expenses consist of:
- Loan origination fees
- Title insurance
- Appraisal fees
- Various taxes
It’s vital for both buyers and sellers to understand what's the average closing cost on a house, as this expense signifies a substantial financial responsibility that needs to be prepared for beforehand. Navigating the maze of closing charges can feel daunting, especially when unexpected fees arise. Failing to prepare for these expenses can lead to significant financial strain during the transaction.
With Vana's escrow services, you’ll benefit from a transparent fee structure and a 4-Step Protection system. This makes navigating these expenses much easier. The system includes:
- Document verification
- Funds protection
- Title clearance
- Closing & settlement
By partnering with Vana, you can ensure that you’re not just aware of these costs, but also equipped to handle them with confidence.
Break Down Closing Costs: Key Components Explained
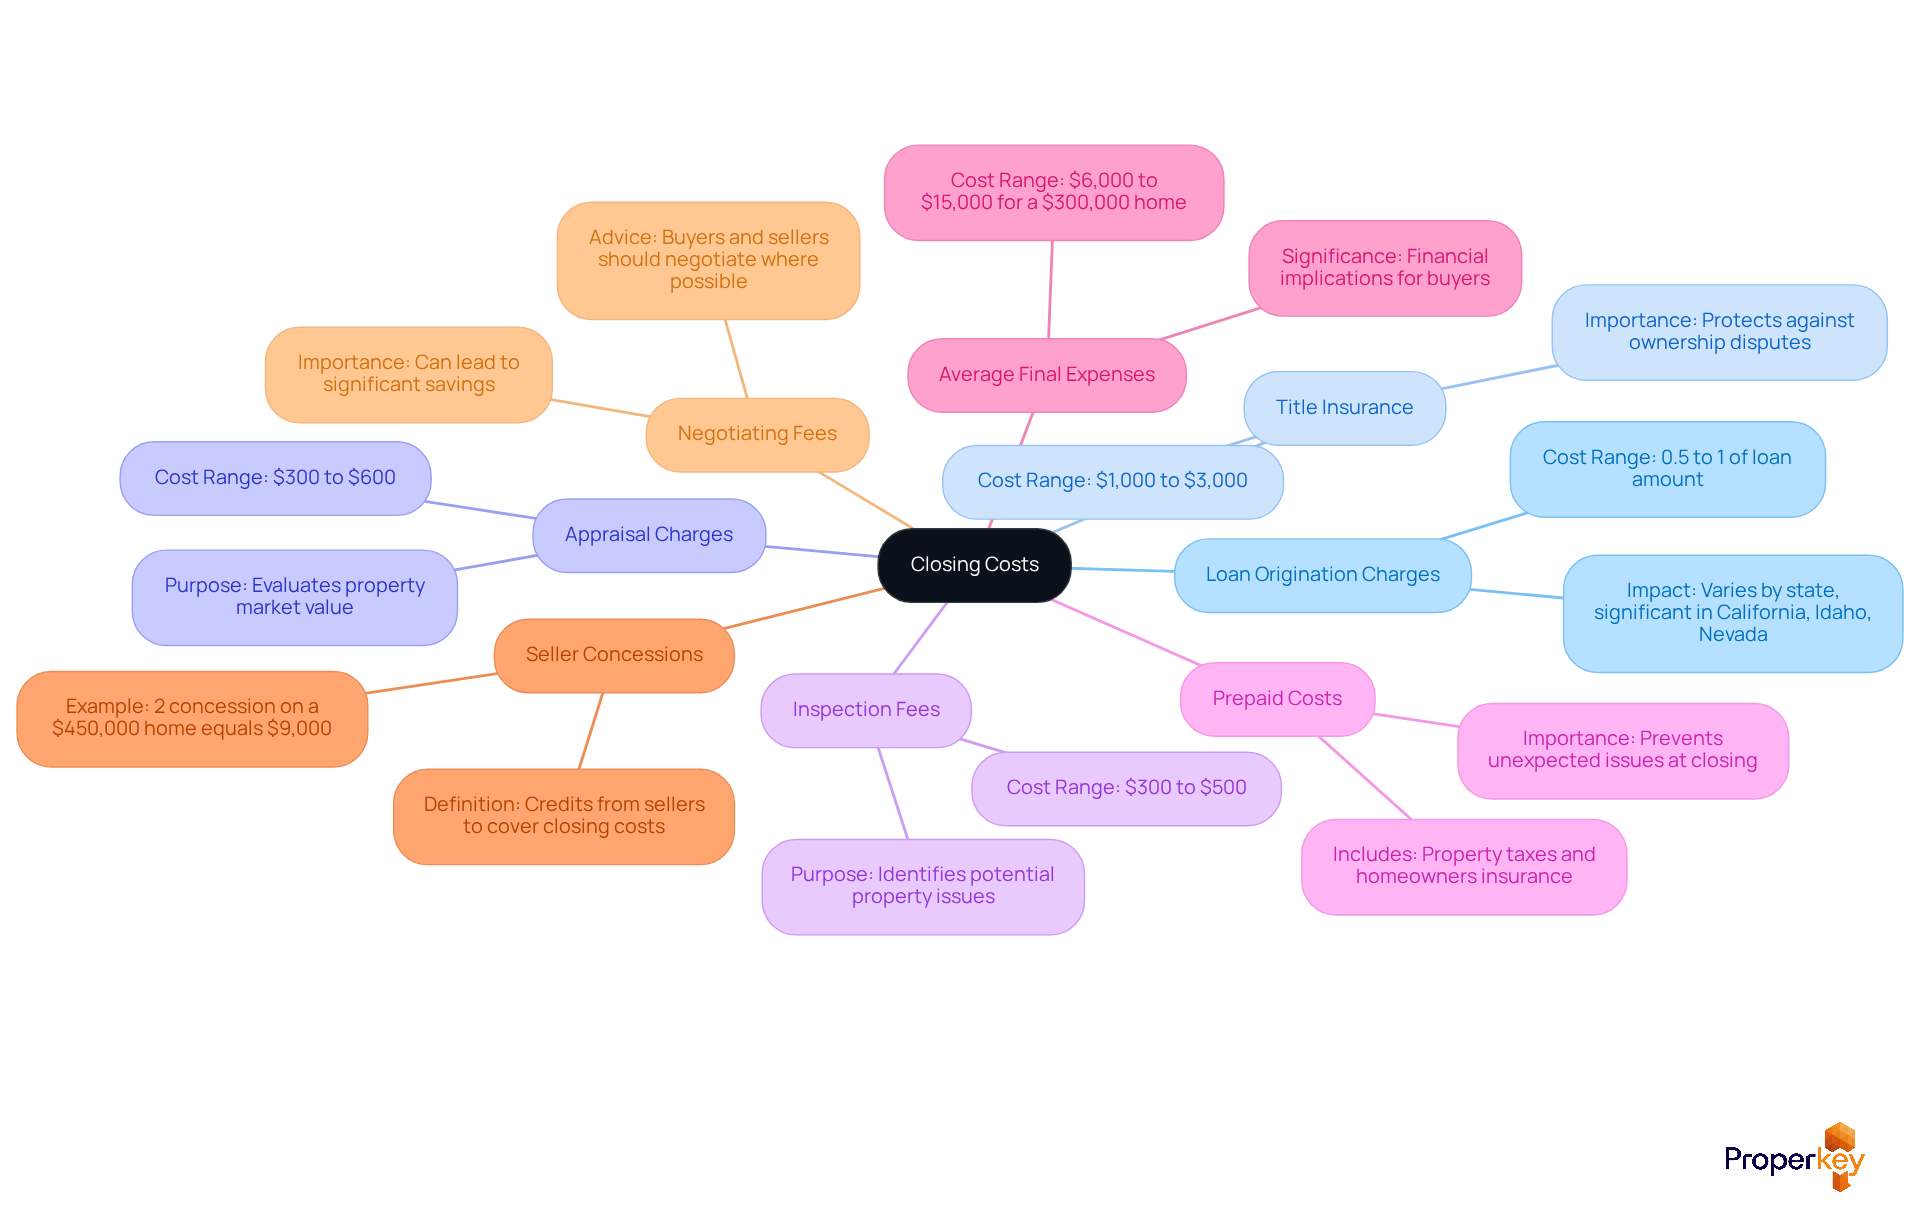
Navigating the maze of closing costs, such as what's the average closing cost on a house, can feel overwhelming for both buyers and sellers, but understanding these essential components is crucial for a successful transaction. Closing costs encompass several key elements that you should be aware of, including:
- Loan Origination Charges: These costs, imposed by lenders for handling the loan application, usually vary from 0.5% to 1% of the loan amount. In California, Idaho, and Nevada, these fees can significantly affect the total expense of acquiring a mortgage.
- Title Insurance: This insurance protects against potential disputes over property ownership and usually costs between $1,000 and $3,000, depending on the property's value. Given the competitive nature of the real estate market in these states, securing title insurance is a prudent step for buyers.
- Appraisal Charges: Necessary to evaluate the property's market value, appraisal charges typically vary from $300 to $600. This expense is crucial for lenders to ensure the property is worth the loan amount.
- Inspection Fees: Covering the expense of home inspections, these fees can range from $300 to $500. Inspections are vital for identifying any potential issues with the property before finalizing the purchase.
- Prepaid Costs: These encompass advance payments for property taxes and homeowners insurance, which are frequently necessary at the finalization of the transaction. Purchasers should plan for these expenses to prevent unexpected issues on settlement day. Imagine facing unexpected costs on the day you thought everything was settled.
- Average Final Expenses: For a $300,000 residence, final expenses can vary from $6,000 to $15,000, emphasizing the financial consequences of these charges. Understanding what's the average closing cost on a house can make the difference between a smooth transaction and financial strain.
- Seller Concessions: Buyers may negotiate seller concessions, where sellers provide credits to help cover closing costs, making the transaction more affordable.
- Negotiating Fees: It’s important for purchasers and sellers to negotiate fees where possible, as this can lead to significant savings.
When you understand these elements, you can anticipate your financial responsibilities and negotiate effectively, paving the way for a smoother transaction. Furthermore, using Vana's escrow services can simplify the finalization process, offering clarity in fee structures and ensuring that all documents and funds are organized effectively. By grasping these costs and leveraging Vana's escrow services, you can turn potential pitfalls into a streamlined, successful sale.
Compare Closing Costs with Other Home Buying Expenses
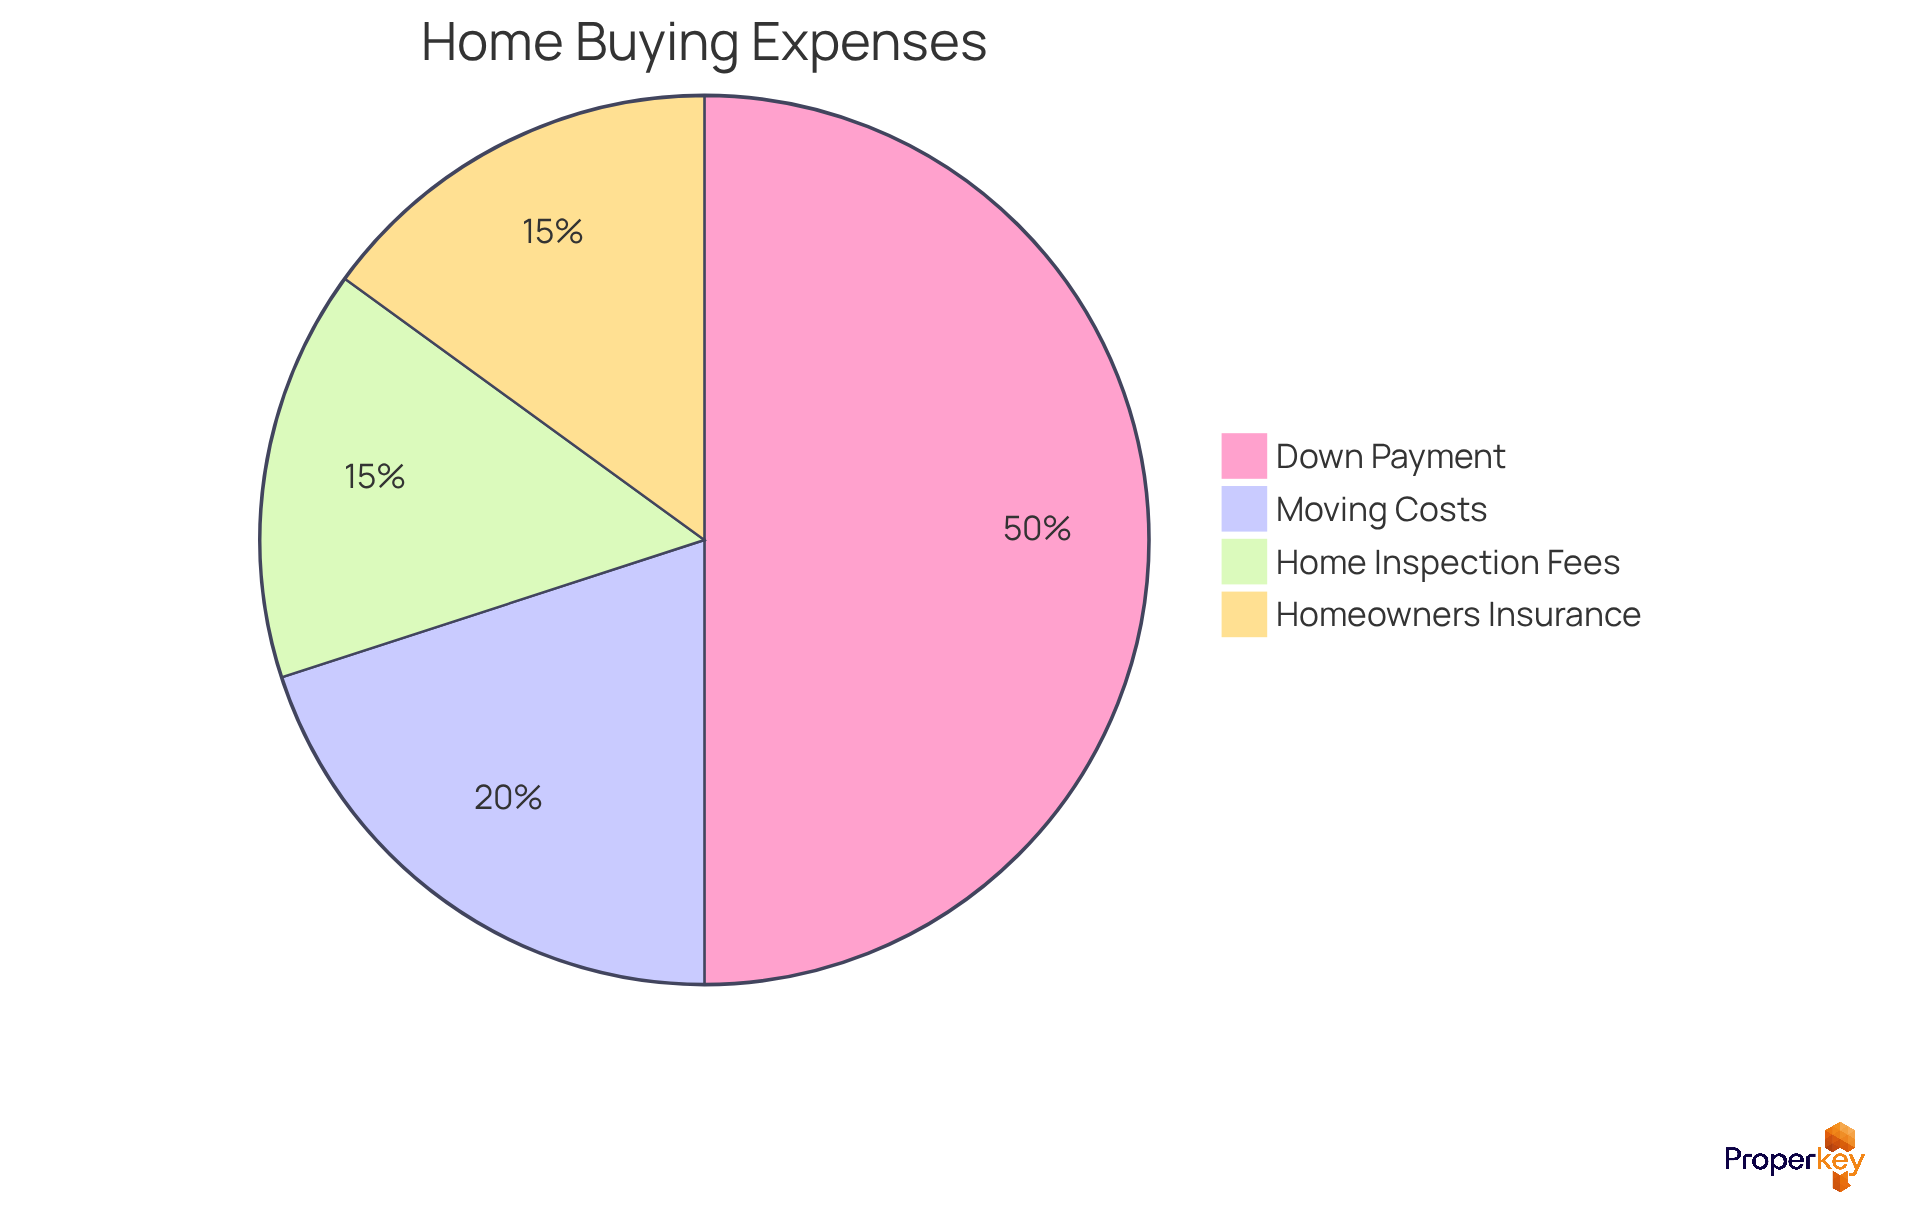
When purchasing a home, it's essential to recognize that costs extend far beyond just closing fees.
- Down Payment: This usually varies from 3% to 20% of the home's purchase price, often representing the largest initial expense. For instance, on a $400,000 home, a 20% down payment would amount to $80,000. In California, the average down payment is approximately 19%, translating to around $78,831 based on recent data. In Idaho and Nevada, down payments can vary, but they generally follow similar trends, with first-time buyers often putting down around 9%.
- Moving Costs: These can vary widely based on distance and volume but generally range from $1,000 to $5,000. In competitive markets, like California, relocation expenses can increase, particularly if professional movers are employed.
- Home Inspection Fees: These fees usually increase the total amount by another $300 to $500, depending on the property's size and condition. In California, thorough inspections are vital, especially given the state's unique housing stock and risks like earthquakes.
- Homeowners Insurance: Frequently mandated by lenders, this can range from $800 to $1,500 each year. In regions susceptible to natural disasters, like California, insurance expenses may be on the higher end of this range. Vana provides customizable home insurance plans with immediate quotes, assisting purchasers in managing these essential expenses efficiently.
Navigating these expenses can be overwhelming for many buyers, especially first-timers. By grasping these expenses, buyers can make informed decisions that lead to successful homeownership.
Manage and Reduce Closing Costs: Practical Strategies
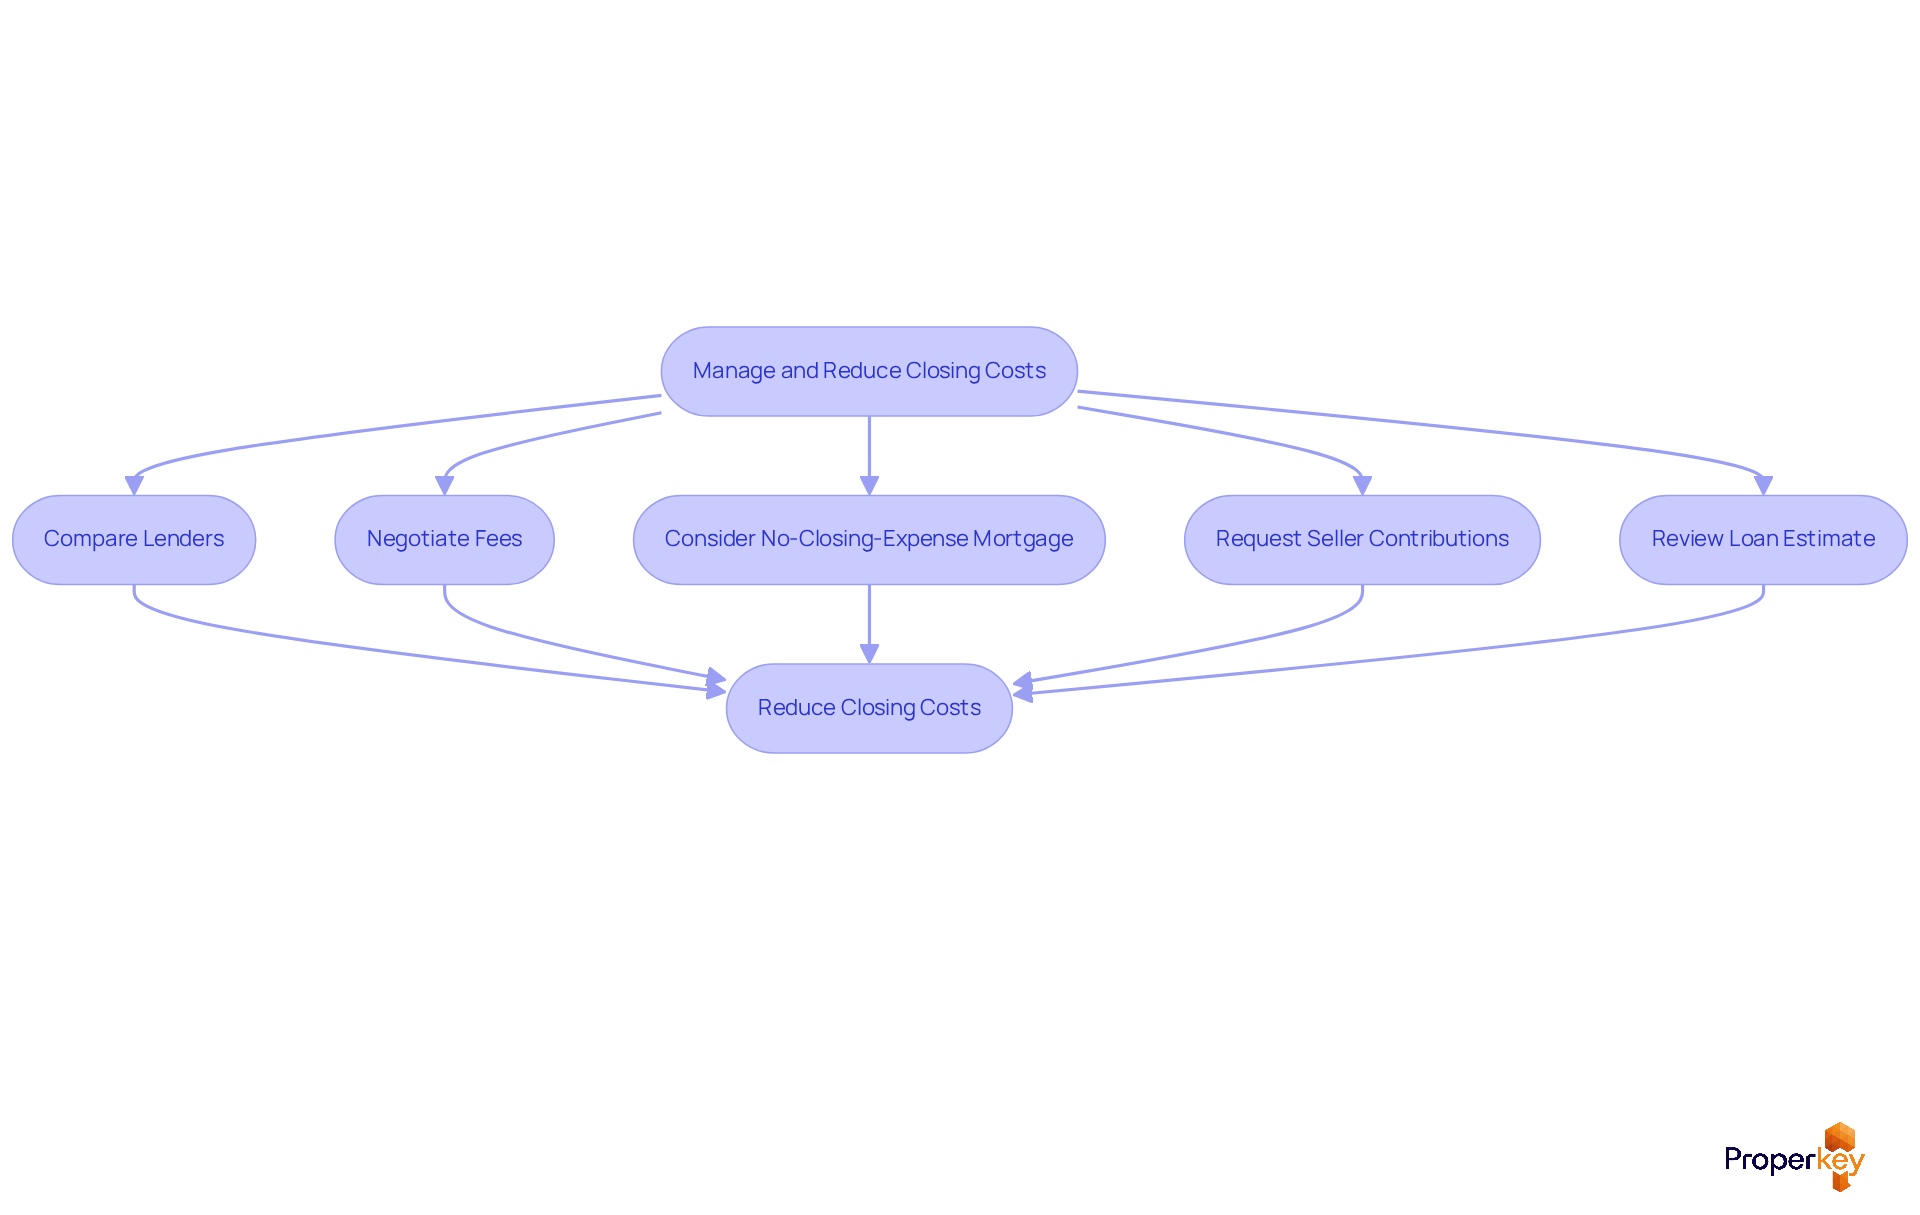
For home buyers, understanding what's the average closing cost on a house is crucial, as high closing costs can be a significant burden, often leading to unexpected financial strain. Let’s explore some effective strategies to manage and reduce your closing costs:
- Compare Lenders: Different lenders offer varying rates and charges. By comparing multiple lenders, you can identify the most favorable terms and potentially save thousands.
- Negotiate Fees: Many closing costs are negotiable. Don’t hesitate to ask your lender or service providers for discounts or to eliminate certain charges. This can include origination and underwriting fees, which can vary significantly between lenders.
- Consider a No-Closing-Expense Mortgage: Some lenders provide options that incorporate expenses into the loan amount. This can be beneficial if you are low on funds at settlement, enabling you to cover these expenses over the duration of the loan.
- Request Contributions from the Seller: In a purchaser's market, sellers might be open to covering a part of the final expenses as a component of the negotiation process. For instance, requesting a seller concession of 3% on a $600,000 home could significantly reduce your cash-to-close.
- Review the Loan Estimate: This document details all anticipated expenses related to your mortgage. Scrutinizing it can help identify areas where you can save, such as comparing origination charges and services you can shop for.
By taking these steps, you not only save money but also pave the way for a smoother home buying experience, especially when considering what's the average closing cost on a house.
Conclusion
Many buyers and sellers feel overwhelmed by the hidden costs associated with closing a deal. Understanding these costs is crucial for effective financial planning. By grasping the various components that contribute to closing costs, individuals can better prepare for the financial responsibilities that come with purchasing a home. When you know what to expect, you can budget better and tackle the complexities of real estate with confidence.
This article delves into the key elements of closing costs, including:
- Loan origination fees
- Title insurance
- Appraisal charges
- Inspection fees
- Among others
Recognizing these costs in relation to other home buying expenses, such as down payments and moving costs, is essential. By comparing these expenses, buyers can gain a clearer picture of their overall financial commitment and make informed decisions that lead to successful homeownership.
By taking charge of your closing costs, you can save money and make your transaction smoother. Here’s how: consider these strategies:
- Compare lenders
- Negotiate fees
- Seek seller concessions
Each can help lighten your financial load. Embracing these insights not only enhances the home buying experience but also underscores the importance of thorough preparation in achieving financial success in real estate.
Frequently Asked Questions
What are closing costs in real estate transactions?
Closing costs are the various fees and expenses incurred by buyers and sellers during the completion of a real estate transaction.
What is the average closing cost on a house?
The average closing cost on a house typically falls between 2% to 5% of the home's purchase price, depending on local market conditions and regulations.
How do closing costs vary by state?
In California, typical closing costs hover around $5,500 due to elevated property values and a low transfer tax rate. In Nevada, closing costs usually range from 2% to 3% of the purchase price, translating to approximately $10,000 to $15,000 on a $500,000 residence.
What are some typical elements included in closing costs?
Typical elements of closing costs include loan origination fees, title insurance, appraisal fees, and various taxes.
Why is it important for buyers and sellers to understand closing costs?
Understanding closing costs is vital as they represent a substantial financial responsibility that needs to be prepared for beforehand, helping to avoid significant financial strain during the transaction.
How can Vana's escrow services assist with closing costs?
Vana's escrow services offer a transparent fee structure and a 4-Step Protection system, which includes document verification, funds protection, title clearance, and closing & settlement, making it easier to navigate closing expenses.
List of Sources
- Define Closing Costs: Understanding the Basics
- The complete cost of buying and selling a home in 2026: Fees most people don't expect (https://fresnobee.com/news/business/article315234670.html)
- Closing Costs by State 2026: Seller & Buyer Fees, All 50 (https://usesumline.com/guides/closing-costs-by-state-guide)
- Closing Costs by State 2026 — All 50 States Compared | RealEstateCalcPro (https://realestatecalcpro.com/closing-costs-by-state)
- US Closing Costs Guide 2026 — What to Expect and How to Reduce Them (https://propertycalchub.com/us/closing-costs)
- Closing Costs in Nevada: 2026 Buyer & Seller Guide (https://nevadarealestategroup.com/blog/closing-costs-in-nevada)
- Break Down Closing Costs: Key Components Explained
- Why closing costs fell in 28 states, rose in 23 (https://nationalmortgagenews.com/news/why-closing-costs-fell-in-28-states-rose-in-23)
- Closing costs: What they are and how much you’ll pay (https://rocketmortgage.com/learn/closing-costs)
- Average Closing Costs [current_year] | List of Closing Costs (https://themortgagereports.com/35800/guide-to-mortgage-closing-costs-what-average-mortgage-costs-are-and-how-to-keep-yours-low)
- How Much Are Closing Costs? Average Costs and Fees in 2026 (https://lendingtree.com/home/mortgage/understanding-mortgage-closing-costs)
- Closing Costs in Nevada: 2026 Buyer & Seller Guide (https://nevadarealestategroup.com/blog/closing-costs-in-nevada)
- Compare Closing Costs with Other Home Buying Expenses
- The complete cost of buying and selling a home in 2026: Fees most people don't expect (https://sacbee.com/news/business/article315234670.html)
- What's The Average Down Payment On A House? | Bankrate (https://bankrate.com/mortgages/average-down-payment)
- What's the Actual Down Payment on a House in 2026? (Data-Backed Reality Check) (https://amerisave.com/learn/what-s-the-actual-down-payment-on-a-house-data-backed-reality-check)
- What Is the Average Down Payment on a House? (https://sofi.com/learn/content/average-down-payment-on-a-house)
- Manage and Reduce Closing Costs: Practical Strategies
- Closing Costs Explained 2026: Every Fee Line by Line (https://mortgage-info.com/blog/closing-costs-explained-line-by-line-2026-buyer-guide)
- Negotiate Closing Costs - Free Estimator (2026) | Daily Calcs (https://dailycalcs.com/blog/finance/closing-cost-negotiation-guide)
- 6 Ways to Reduce Closing Costs in California (2026) (https://betteroffers.com/blog/reduce-closing-costs-california)
- Can You Negotiate Closing Costs When Buying a Home? (https://redfin.com/blog/can-you-negotiate-closing-costs)
- Reduce Mortgage Closing Costs 2026: Save $3K-$8K (https://mortgage-info.com/blog/how-to-reduce-mortgage-closing-costs-2026-save-5k)



