What Is a Buydown Mortgage? Key Insights for California Homebuyers
Introduction
As California homebuyers face the dual challenges of rising interest rates and soaring property prices, many find themselves at a crossroads in their financing journey. A buydown mortgage emerges as a strategic solution, offering the potential to significantly lower monthly payments and enhance affordability during the crucial early years of homeownership.
Yet, understanding the mechanics of a buydown mortgage is essential. How does it truly work, and what are the long-term implications for both buyers and sellers in a competitive market? Grasping these nuances could be the key to unlocking a more affordable path to homeownership.
Define Buydown Mortgage: Understanding the Concept
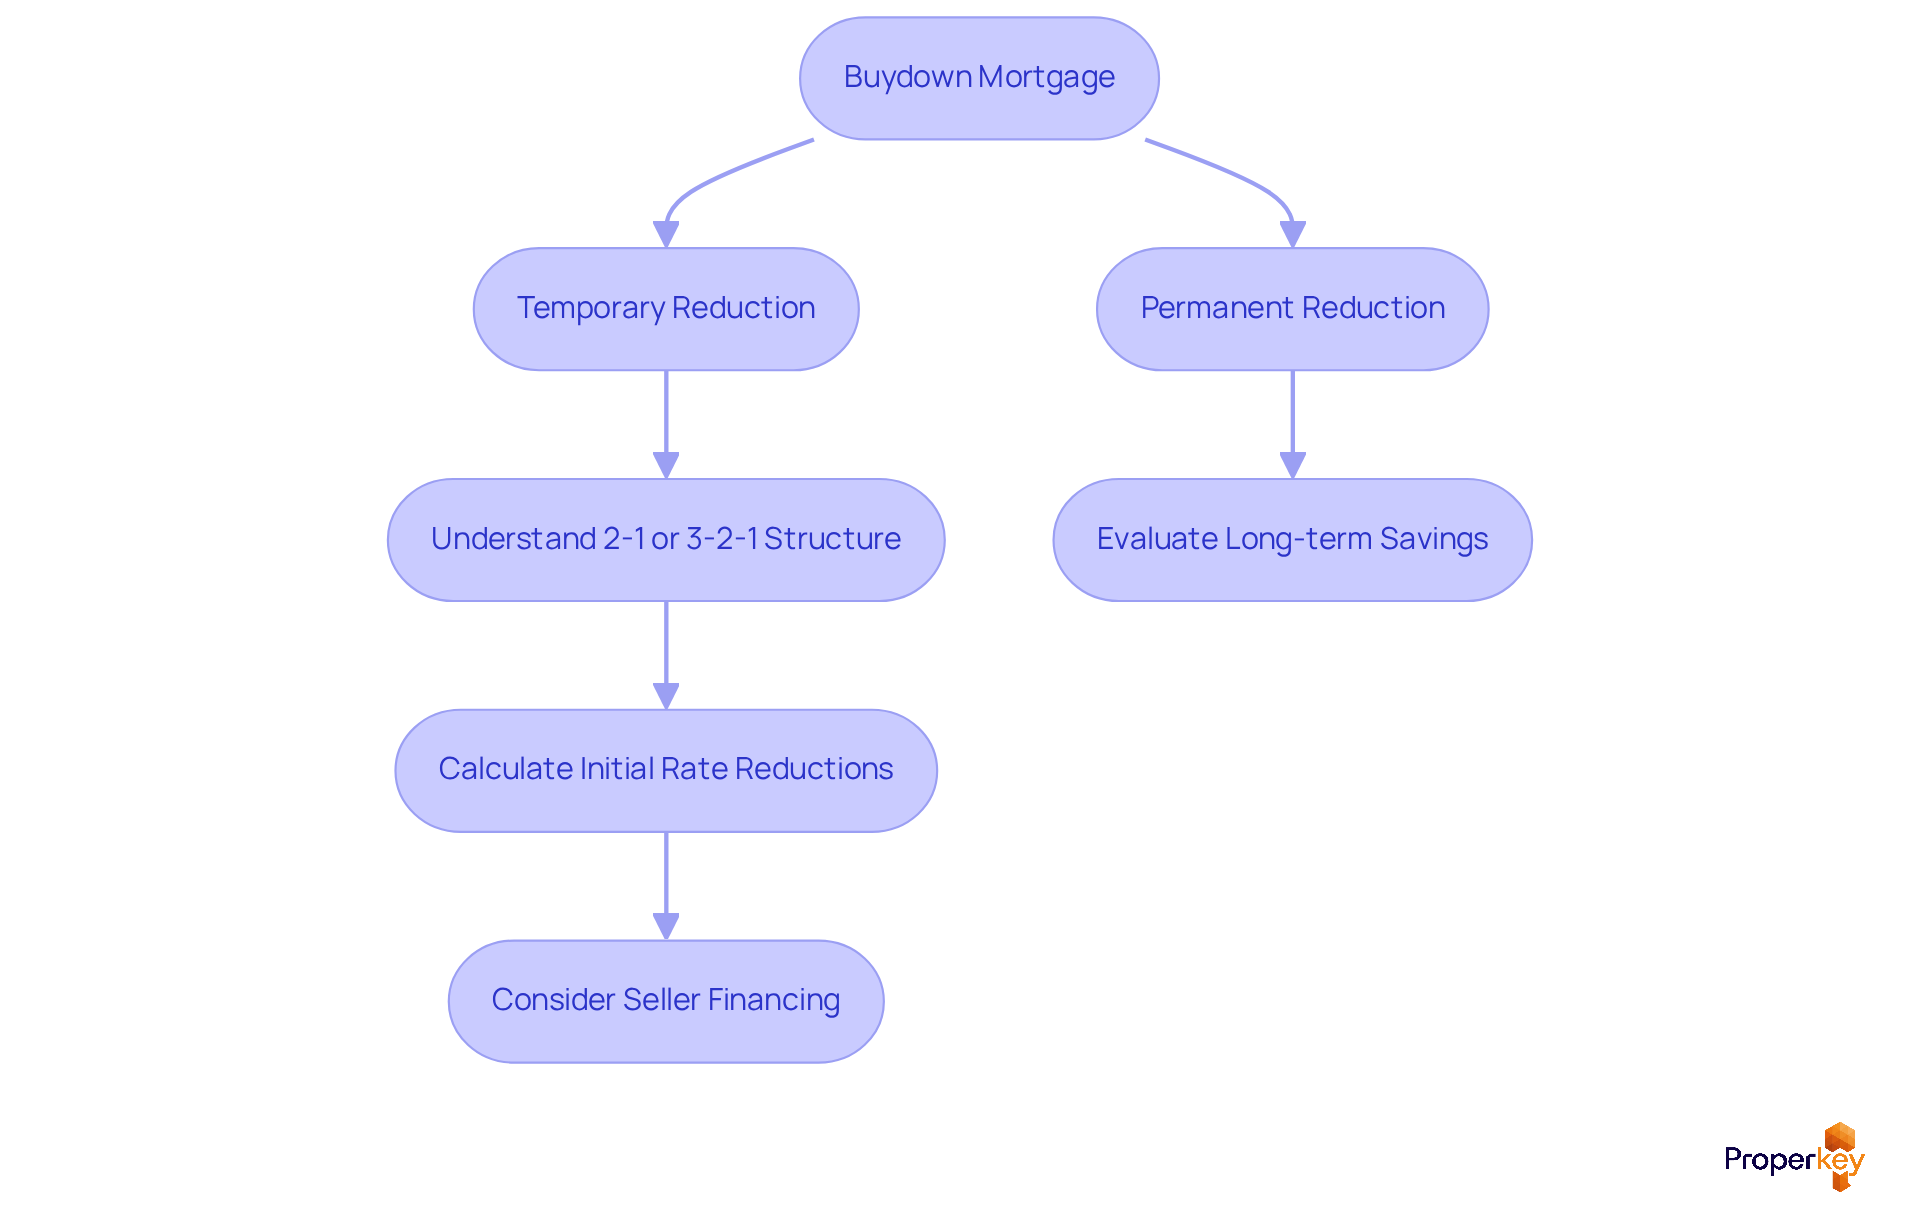
Navigating the complexities of home financing can be daunting, especially when faced with high interest rates and upfront costs. A discount loan is a financing approach that allows borrowers to reduce their loan interest by paying an upfront fee at closing, often referred to as 'points.' This arrangement significantly reduces monthly mortgage payments for a set period. To understand what a buydown mortgage is, it's important to know that there are two main types: temporary and permanent.
In a temporary reduction, the interest rate is lowered for the initial years of the loan, usually arranged as a 2-1 or 3-2-1 structure, where the rate diminishes by a fixed percentage each year before returning to the full rate. For example, a 2-1 rate reduction provides a 2% decrease in the first year and a 1% decrease in the second year. Sellers and builders frequently finance these temporary buydowns as incentives to draw in purchasers, making them a strategic tool in competitive markets. On the other hand, a lasting reduction decreases the interest amount for the entire term of the mortgage, offering long-term savings.
Homebuyers in California find this strategy especially beneficial, as it can ease the financial burden during the early years of homeownership, making it easier to manage costs associated with moving and settling into a new home. Furthermore, prospective purchasers should compute the break-even point to assess if a buydown is financially advantageous, particularly noting that approximately 58.7% of home purchasers with acquisition loans paid discount points during a recent phase of heightened interest levels.
Loanvana steps in with a powerful financing tool that allows buyers to easily compare hundreds of loan options side-by-side from various lenders, ensuring they discover the best deals available. To understand what a buydown mortgage is, it's important to note that temporary buydowns generally reduce loan costs for a specified number of years, typically between one and three, offering significant financial relief. Understanding the benefits of discount loans could be the key to unlocking a more manageable path to homeownership.
Contextualize Buydown Mortgages: Importance in Real Estate Financing
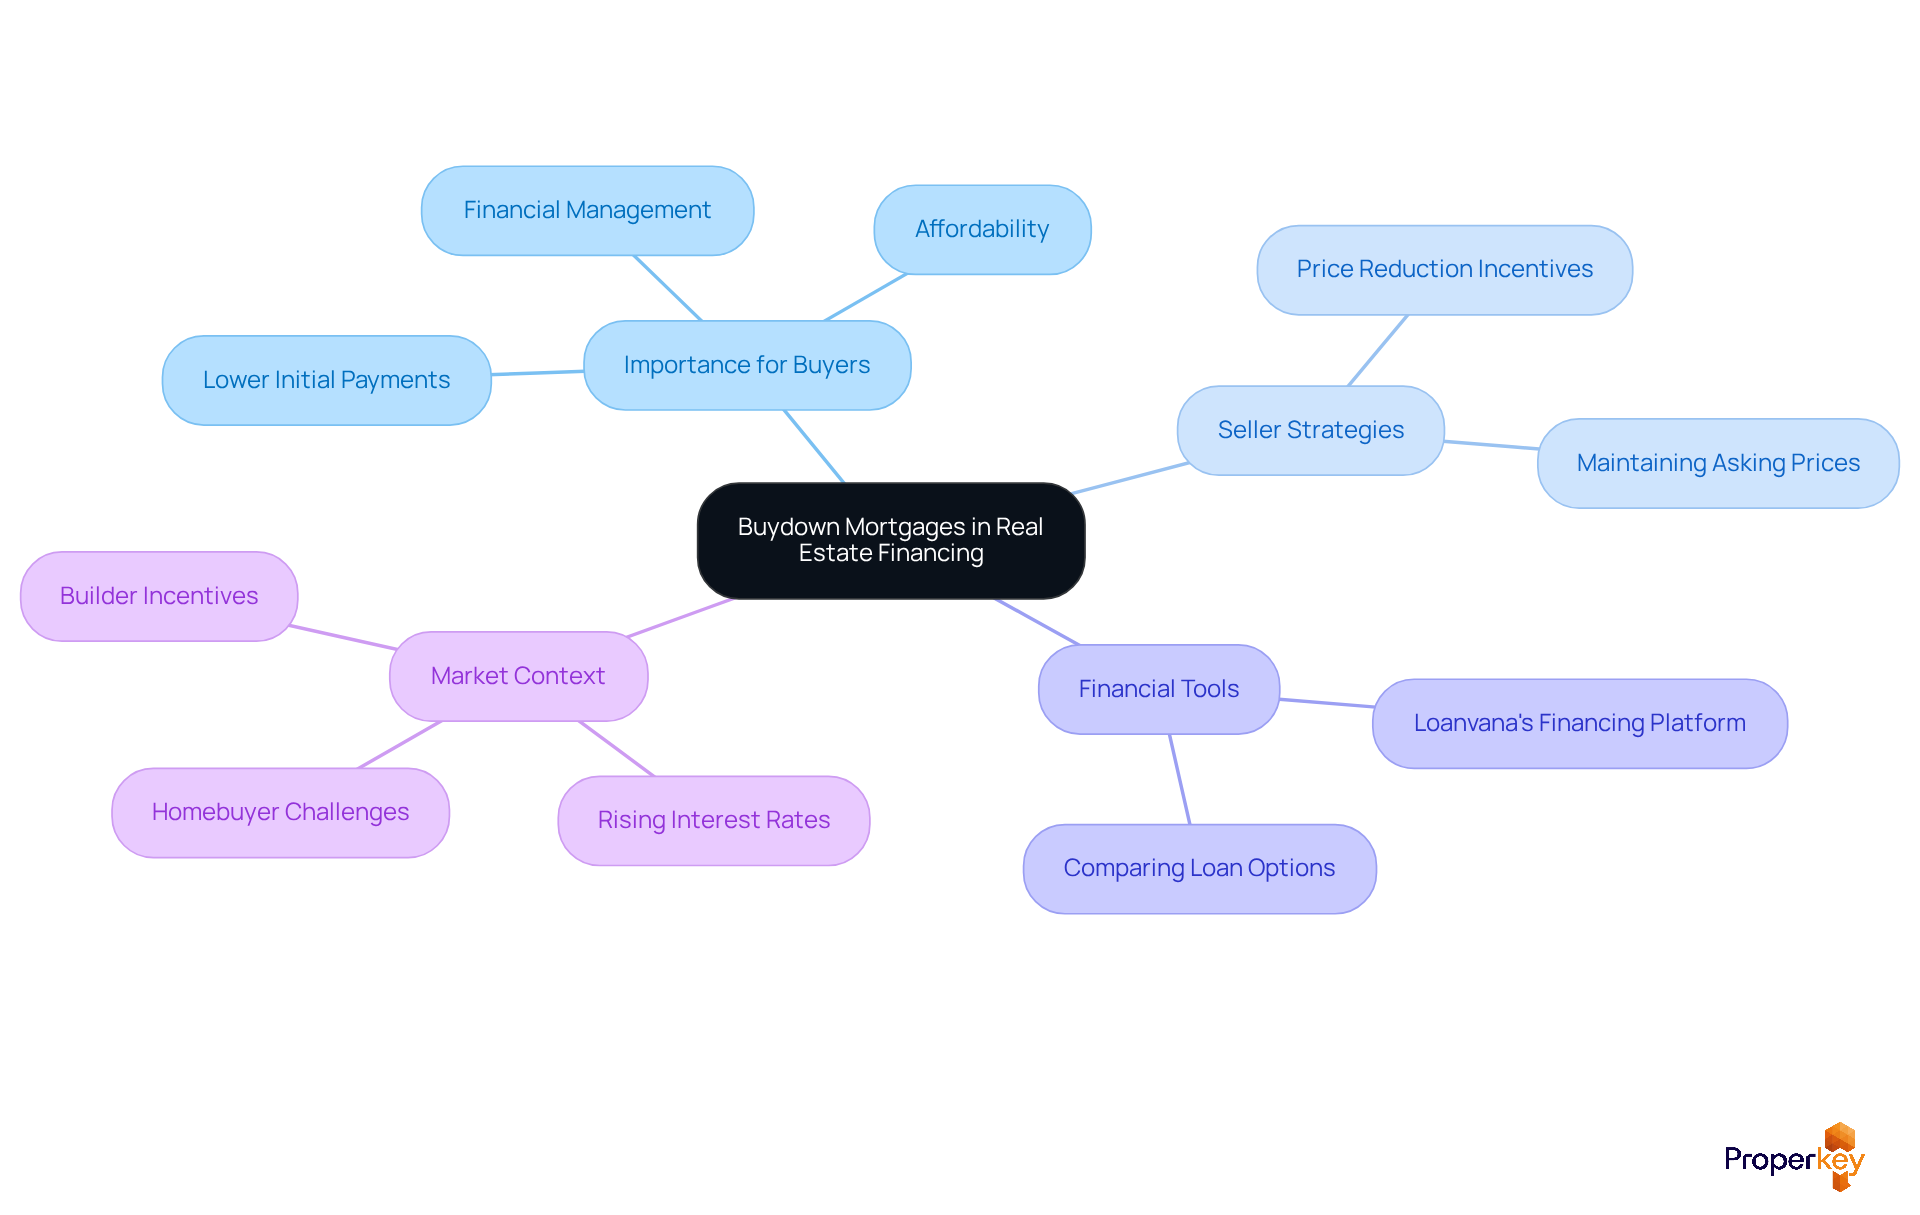
As interest rates climb, homebuyers in California are feeling the pinch, making financing options like buydown loans more critical than ever. Buydown loans allow buyers to lower their initial loan payments. This boosts affordability and makes owning a home more attainable. For instance, a 2-1 reduction can save buyers $367 monthly in the first year and $189 in the second year, greatly easing their financial burden during the crucial early years of their loan. Many buyers are struggling to afford homes due to rising interest rates and high property prices. Reduced-rate mortgages help them manage their finances better.
Sellers are also increasingly using price reduction incentives to attract buyers. This strategy allows them to maintain their asking prices while making their properties more appealing. However, sellers face limits on how much they can reduce prices. This can impact the financial dynamics of the sale. As the California real estate landscape continues to evolve, understanding what is buydown mortgage and its benefits is essential for both buyers and sellers. Without this knowledge, buyers risk missing out on affordable homeownership opportunities. Additionally, what is buydown mortgage typically available for the purchase of 1-2 unit homes that the individual plans to occupy, making this financing option particularly relevant for many in the housing market.
To better support homebuyers, tools such as Loanvana's financing platform enable buyers to apply once and compare hundreds of loan options side-by-side from various lenders. This simplifies the financing process and ensures they discover the best offers available. Navigating these options could be the key to unlocking your dream home in a challenging market.
Trace the Origin of Buydown Mortgages: Historical Development
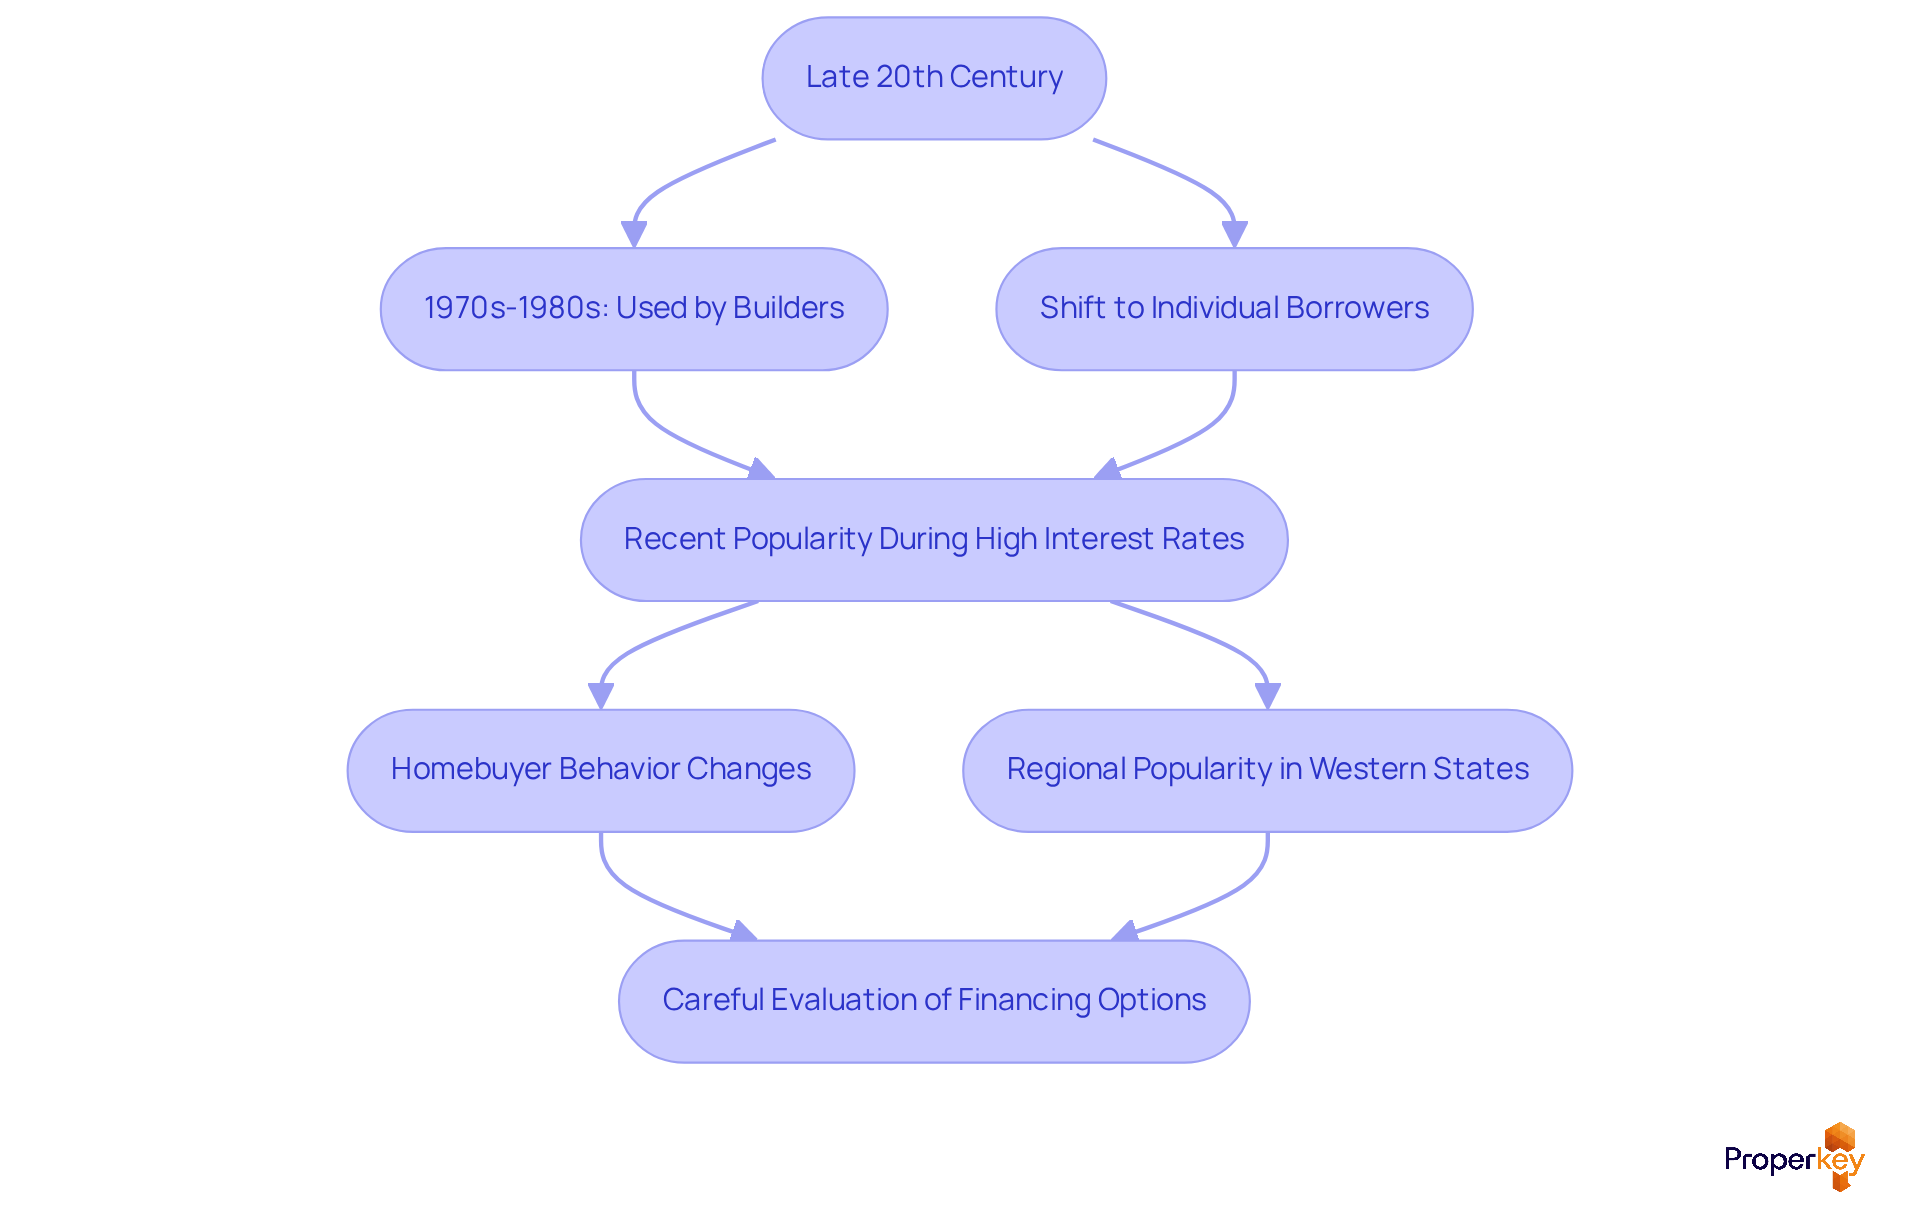
In a fluctuating interest rate environment, home sellers face unique challenges that demand innovative financing solutions. The idea of reduced-rate loans emerged in the late 20th century, primarily as a response to interest rate fluctuations and the need for more flexible financing options. Initially gaining traction in the 1970s and 1980s, these loans were mainly used by builders and developers to attract homebuyers. Over time, rate-reduction loans became a viable option for individual borrowers, helping them secure better loan terms.
Recently, especially during periods of high interest rates, many are asking what is buydown mortgage as these loans have gained popularity in various real estate transactions. This trend reflects a shift in homebuyer behavior, where individuals are willing to invest in upfront costs to achieve lower monthly payments, thereby enhancing their purchasing power in competitive markets.
Interestingly, we've noticed that temporary buydowns are particularly popular in western states like Idaho and Arizona, indicating regional dynamics that influence their appeal. While temporary buydowns can provide immediate financial relief, they often come with higher overall costs over the life of the loan. Homeowners with these options typically received interest rates that were, on average, 15 basis points higher. This underscores the need for careful evaluation, especially regarding break-even durations, which can be under two years for a 30-year loan with a one-point buy-down.
Ultimately, a careful analysis of your financing options can mean the difference between a successful sale and a costly mistake.
Explore Key Characteristics: Mechanics of Buydown Mortgages
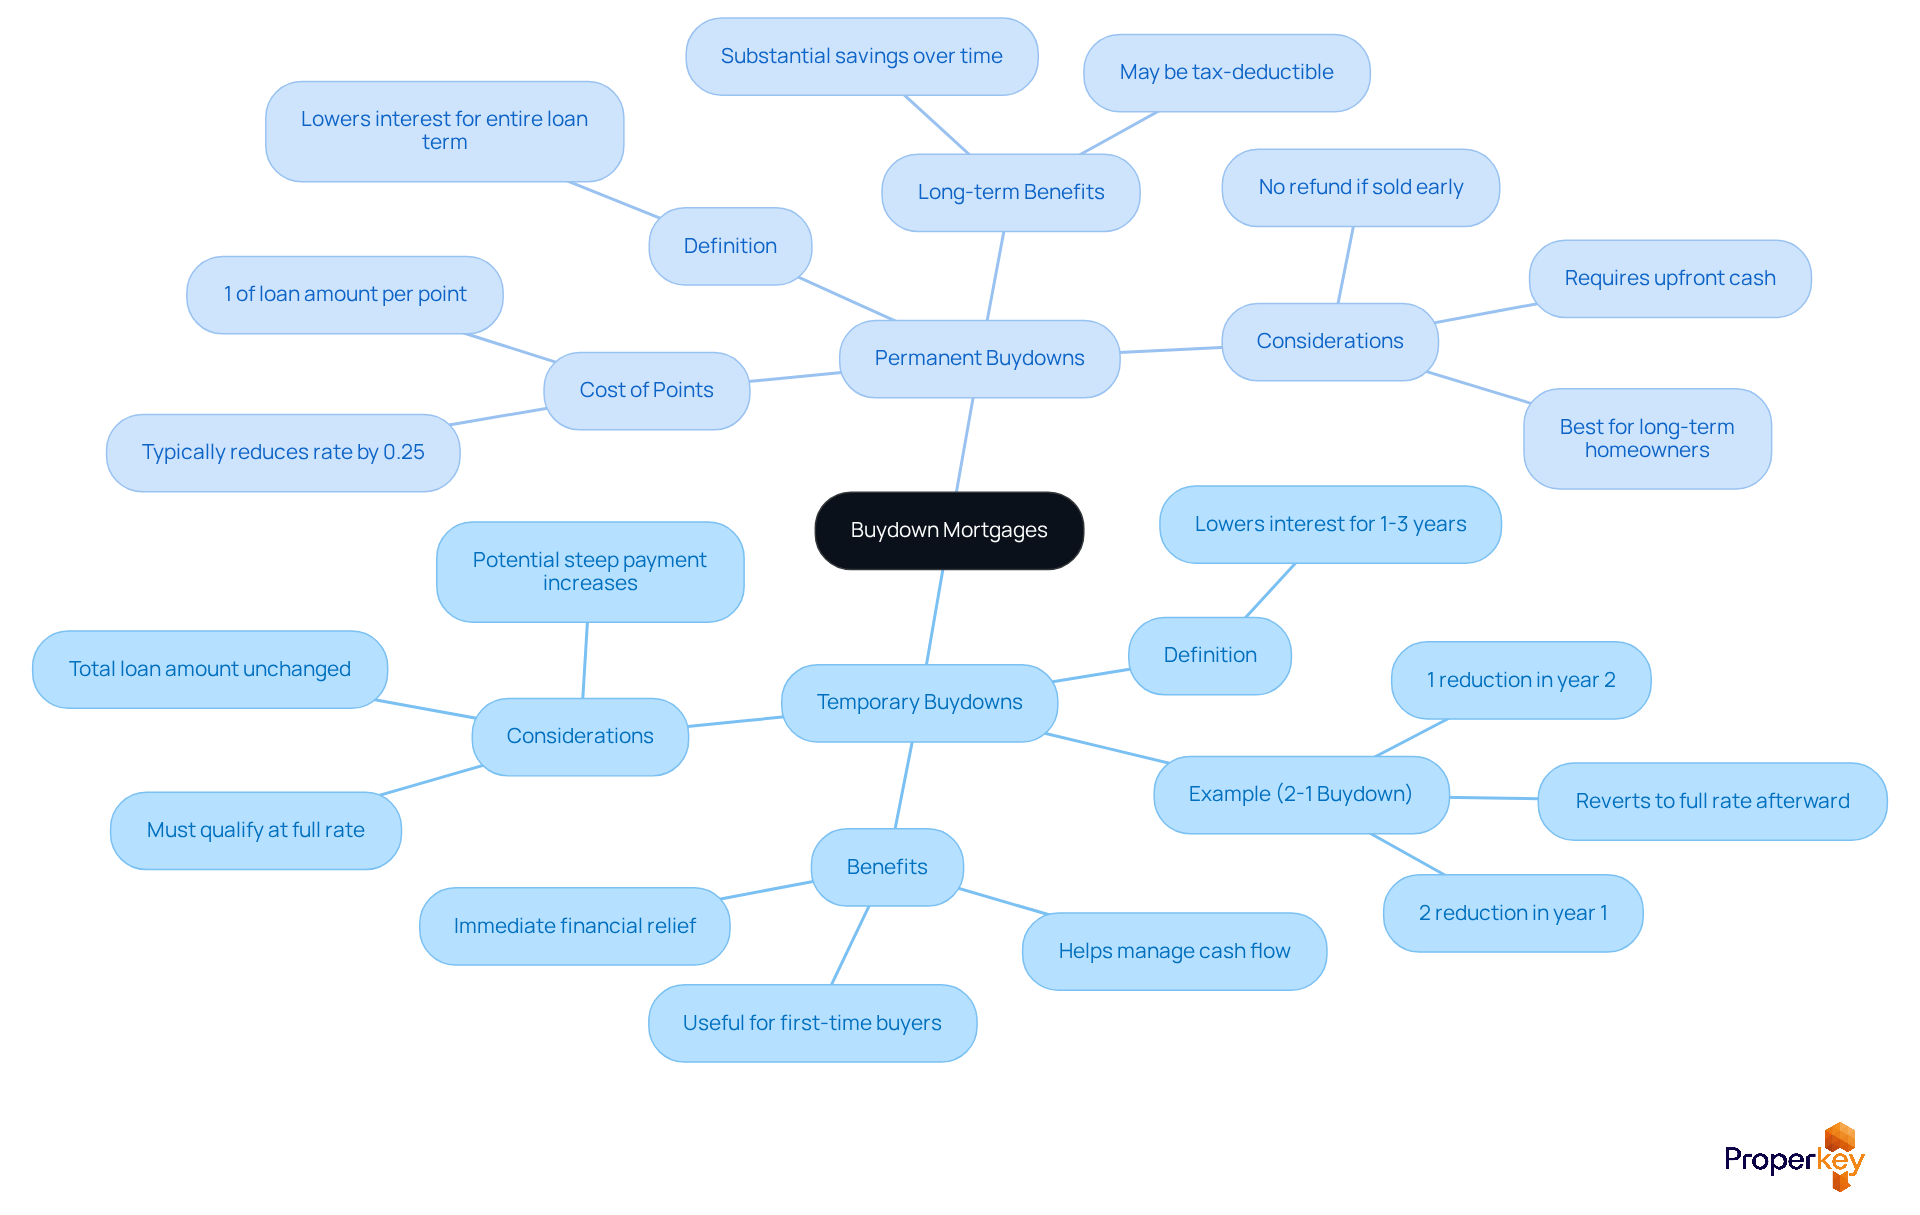
Navigating the complexities of what is buydown mortgage can be daunting for home sellers and buyers alike. To understand what is buydown mortgage, it's important to know that they can be structured in various ways, primarily categorized into temporary and permanent buydowns. A temporary reduction in interest lowers the cost for the first one to three years, enabling borrowers to enjoy decreased monthly payments during this initial period. For example, a 2-1 buydown lowers the interest percentage by 2% in the first year and 1% in the second year, returning to the initial figure afterward. Understand that while temporary buydowns provide initial relief, they do not change the total amount paid over the life of the loan; they simply bridge payment gaps without delivering long-term savings. This option is especially beneficial for first-time homebuyers or those anticipating income growth, offering immediate financial relief. Furthermore, lenders necessitate that borrowers qualify at the complete interest level, not the temporarily lowered amount, which is crucial for understanding your future financial obligations.
In contrast, a permanent reduction involves paying upfront points to decrease the interest for the entire loan term. Each discount point typically costs 1% of the loan amount and can reduce the rate by approximately 0.25%. This option is often more beneficial for borrowers planning to stay in their homes long-term, as it can lead to substantial savings over the life of the loan. For instance, a lasting reduction can save homeowners tens of thousands of dollars in interest over 30 years, making homeownership more affordable.
Understanding what is buydown mortgage and the implications of both types is crucial for making informed financial decisions. Purchasers should consult with financing experts to assess which option aligns best with their financial situation and long-term housing plans. Furthermore, sellers may offer to pay for buydowns as part of the deal, providing immediate relief from monthly payments without lowering the home's price. Ultimately, the right buydown strategy can be a game-changer in your home-selling journey, influencing both immediate cash flow and long-term financial health.
Highlight Benefits: Advantages of Buydown Mortgages
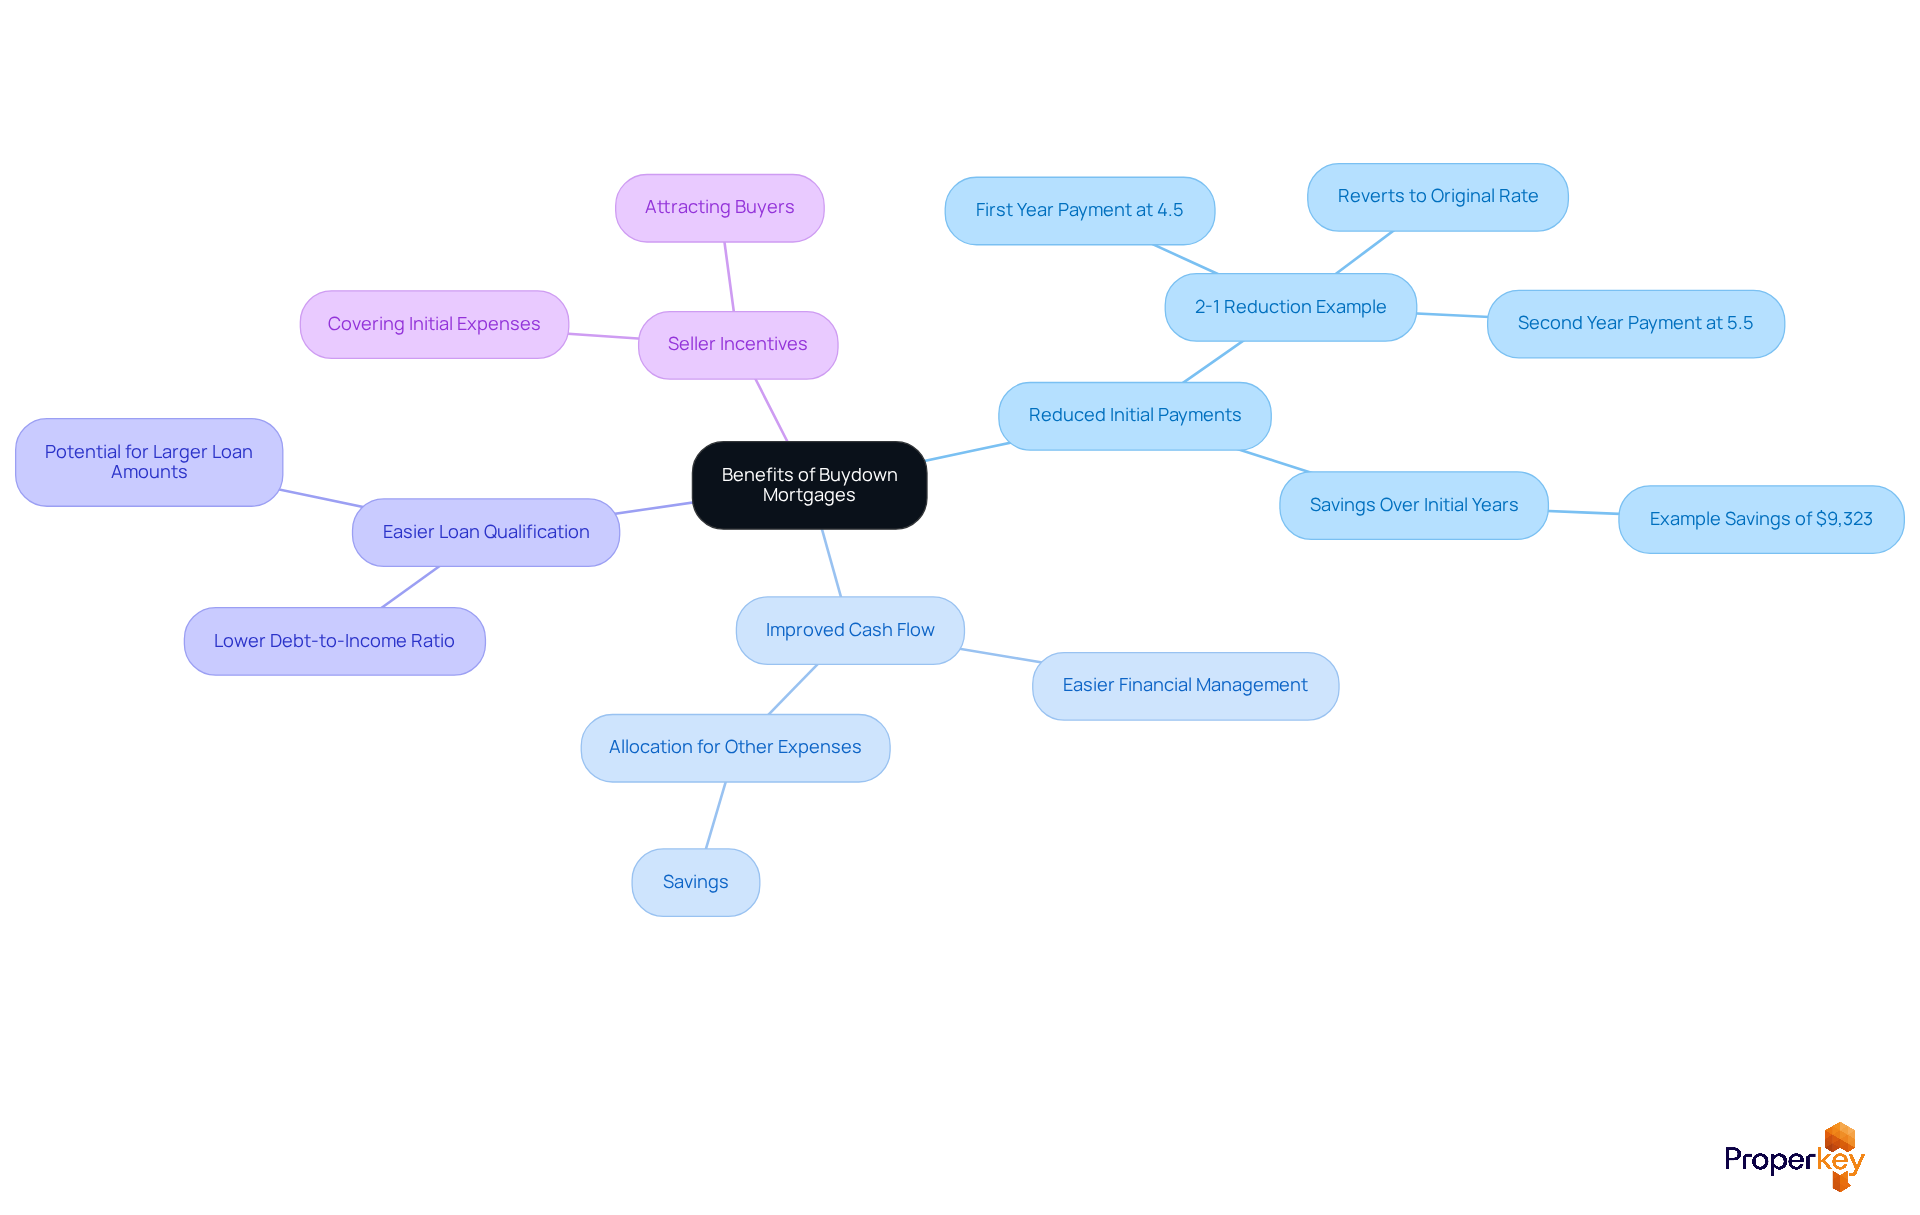
In a high-interest climate, California homebuyers face significant challenges that can hinder their ability to purchase a home. Buydown loans provide several important benefits, especially in today's financial landscape. One of the primary advantages is the reduction of initial monthly payments, significantly enhancing affordability. Reducing the interest rate in the early years allows buyers to allocate their finances to other important expenses, like home improvements or savings, rather than being burdened by hefty loan payments.
Plus, these mortgages can really help with cash flow, making it simpler for buyers to keep their finances in check. For instance, a 2-1 reduction permits a lowered interest rate of 4.5% in the first year and 5.5% in the second year, before returning to the original rate. This gradual increase in payments assists buyers in adapting to homeownership expenses without feeling overwhelmed.
Moreover, reduced-rate mortgages can facilitate easier qualification for loans. The lower initial payments may align better with an individual's budget, potentially allowing them to qualify for larger loan amounts. This is particularly beneficial in a competitive market where securing financing can be challenging.
Sellers can also utilize incentive programs to draw in buyers, creating a mutually advantageous situation. For instance, in a buyer's market, sellers may propose to cover the initial expenses of a price reduction, enhancing the attractiveness of their properties and accelerating the sales process.
Case studies illustrate these benefits effectively. In one case, a seller proposed a 2-1 reduction on a $400,000 loan at a 7% interest rate, leading to a savings of over $9,323 in interest for the buyer during the initial two years. Such strategies not only enhance the attractiveness of a property but also help sellers close deals more quickly.
In summary, what is buydown mortgage serves as a valuable tool for navigating California's home financing landscape. They provide initial payment relief and improved affordability, which is essential for first-time buyers and seasoned investors to understand what is buydown mortgage. Additionally, utilizing Loanvana's financing tool allows buyers to apply once and compare hundreds of loan options side-by-side from multiple lenders, further simplifying the financing process.
Conclusion
Navigating California's real estate market can feel overwhelming, especially with rising interest rates. Understanding the intricacies of a buydown mortgage is essential for homebuyers looking to make informed decisions. This financing option allows borrowers to lower their interest rates through upfront payments, resulting in reduced monthly payments. This is particularly beneficial during the initial years of homeownership. By leveraging either temporary or permanent buydown structures, buyers can enhance their affordability and manage their financial commitments more effectively.
Throughout this article, we've explored key insights into the mechanics and benefits of buydown mortgages. Temporary buydowns offer immediate relief by decreasing payments for the first few years, while permanent buydowns provide long-term savings. The historical context highlights how these loans have evolved to meet the needs of buyers in fluctuating interest rate environments. Additionally, the strategic use of buydown mortgages by sellers as an incentive showcases their role in facilitating smoother transactions in a competitive market.
By leveraging buydown mortgages, buyers can unlock pathways to homeownership that may have seemed out of reach. As interest rates rise, understanding and utilizing these financing options can empower buyers to make informed decisions, ensuring they do not miss out on affordable pathways to homeownership. Engaging with tools like Loanvana can further streamline the process, allowing buyers to compare various loan options and secure the best possible terms.
Frequently Asked Questions
What is a buydown mortgage?
A buydown mortgage is a financing approach that allows borrowers to reduce their loan interest by paying an upfront fee at closing, known as 'points,' which significantly lowers monthly mortgage payments for a set period.
What are the two main types of buydown mortgages?
The two main types of buydown mortgages are temporary and permanent. Temporary buydowns lower the interest rate for the initial years of the loan, while permanent buydowns reduce the interest amount for the entire term of the mortgage.
How does a temporary buydown work?
A temporary buydown typically follows a 2-1 or 3-2-1 structure, where the interest rate is reduced by a fixed percentage each year for a specified number of years before returning to the full rate. For example, a 2-1 buydown provides a 2% decrease in the first year and a 1% decrease in the second year.
Why are buydown mortgages beneficial for homebuyers in California?
Buydown mortgages are particularly beneficial for homebuyers in California as they help ease the financial burden during the early years of homeownership, making it easier to manage costs associated with moving and settling into a new home.
How can buyers assess if a buydown mortgage is financially advantageous?
Prospective buyers should compute the break-even point to determine if a buydown is financially beneficial, especially considering that a significant percentage of home purchasers with acquisition loans have paid discount points during periods of high interest rates.
What financial relief can a 2-1 buydown provide?
A 2-1 buydown can save buyers approximately $367 monthly in the first year and $189 in the second year, greatly easing their financial burden during the crucial early years of their loan.
How are sellers using buydown mortgages as a strategy?
Sellers are increasingly using buydown mortgages as price reduction incentives to attract buyers while maintaining their asking prices, making their properties more appealing in a competitive market.
What types of homes are typically eligible for buydown mortgages?
Buydown mortgages are generally available for the purchase of 1-2 unit homes that the individual plans to occupy, making this financing option relevant for many homebuyers in the housing market.
How can Loanvana assist buyers in the financing process?
Loanvana provides a financing platform that allows buyers to apply once and compare hundreds of loan options side-by-side from various lenders, simplifying the financing process and helping them find the best offers available.
List of Sources
- Define Buydown Mortgage: Understanding the Concept
- Mortgage buydown: What it is and how it works (https://empower.com/the-currency/life/mortgage-buydown-what-it-and-how-it-works)
- Mortgage Buydown: What It Means for Home Buyers in 2026 (https://amerisave.com/glossary/mortgage-buydown-what-it-means-for-home-buyers-in)
- Buy down interest rate: How mortgage buydowns work and cost (https://rocketmortgage.com/learn/buydown-mortgage)
- Mortgage Buydown: How It Works, Types, and Costs (https://freedommortgage.com/learn/homebuying/mortgage-buydowns)
- Mortgage Rate Buydown Definition (https://dictionary.nolo.com/mortgage-rate-buydown-term.html)
- Contextualize Buydown Mortgages: Importance in Real Estate Financing
- How to qualify for a rate buydown as a first-time homebuyer (https://guildmortgage.com/blog/how-to-qualify-for-a-rate-buydown-as-a-first-time-homebuyer)
- Buydowns Vs Price Cuts: We Have A Winner (https://nationalmortgageprofessional.com/news/buydowns-vs-price-cuts-we-have-winner)
- How Mortgage Rate Buydowns Save Money | New American Funding (https://newamericanfunding.com/learning-center/homebuyers/the-rise-of-mortgage-rate-buydowns-how-they-can-save-buyers-thousands)
- How an Interest Rate Buydown Can Make Your Mortgage More Affordable | Homeownership Hub (https://fairway.com/articles/2-1-buydown-make-homeownership-more-affordable?nmls=1658823)
- Helping New Buyers on the Path to Homeownership (https://ncsl.org/resources/details/helping-new-buyers-on-the-path-to-homeownership)
- Trace the Origin of Buydown Mortgages: Historical Development
- Temporary Mortgage Rate Buydown Activity Spiked in Late 2022, Now Becoming Less Common (https://freddiemac.com/research/insight/20230731-temporary-mortgage-rate-buydown-activity-spiked-in)
- Evaluating the Mortgage Rate Buy-Down Decision (https://financialplanningassociation.org/article/journal/NOV15-evaluating-mortgage-rate-buy-down-decision)
- Mortgage Buydowns: The Latest Insights & Trends - Virginia REALTORS® (https://virginiarealtors.org/2023/11/06/mortgage-buydowns-insights-trends)
- Explore Key Characteristics: Mechanics of Buydown Mortgages
- How Temporary Rate Buydowns Work: 1-0, 2-1, and 3-2-1 Explained | Movement Mortgage | Movement Mortgage Blog (https://movement.com/blog/2026/06/temporary-rate-buydowns-explained)
- Interest Rate Buydowns: Permanent vs. Temporary Buydowns (https://apmortgage.com/blog/interest-rate-hacks-to-reduce-your-monthly-payments)
- Mortgage Buydown: What It Means for Home Buyers in 2026 (https://amerisave.com/glossary/mortgage-buydown-what-it-means-for-home-buyers-in)
- Temporary Buydown Mortgages Explained (https://nfmlending.com/temporary-buydown-mortgages-explained)
- Secondary Strategies: Buydowns vs. Float Downs (https://nationalmortgageprofessional.com/news/secondary-strategies-buydowns-vs-float-downs)
- Highlight Benefits: Advantages of Buydown Mortgages
- How Mortgage Rate Buydowns Save Money | New American Funding (https://newamericanfunding.com/learning-center/homebuyers/the-rise-of-mortgage-rate-buydowns-how-they-can-save-buyers-thousands)
- What Is a Mortgage Buydown? | Amplify Credit Union (https://goamplify.com/mortgage/buydowns/what-is-a-buydown)
- 2-1 Buydown Loans and How They Can Help Homebuyers | Keller Home Loans (https://kwlends.com/what-is-a-2-1-buydown-loan-and-how-does-it-help-homebuyers)
- Unlocking Financial Benefits of a Rate Buydown | Elliott Homes | Elliott Homes (https://elliotthomes.com/blog/unlocking-the-financial-benefits-of-a-rate-buydown)
- Understanding Temporary Buydowns: How They Work and Their Benefits for Homebuyers (https://northpointe.com/learn/homes-real-estate/understanding-temporary-buydowns-how-they-work-and-their-benefits-for-homebuyers)

