Can You Get a Mortgage with No Credit History? Here's How!

Introduction
Many aspiring homeowners find themselves at a standstill, unsure of how to proceed without a credit history. Let’s explore the mortgage solutions available for those without traditional credit, highlighting the potential pathways to securing a loan. Understanding these strategies could be the key to unlocking your path to homeownership.
Understand Mortgage Basics Without Credit History
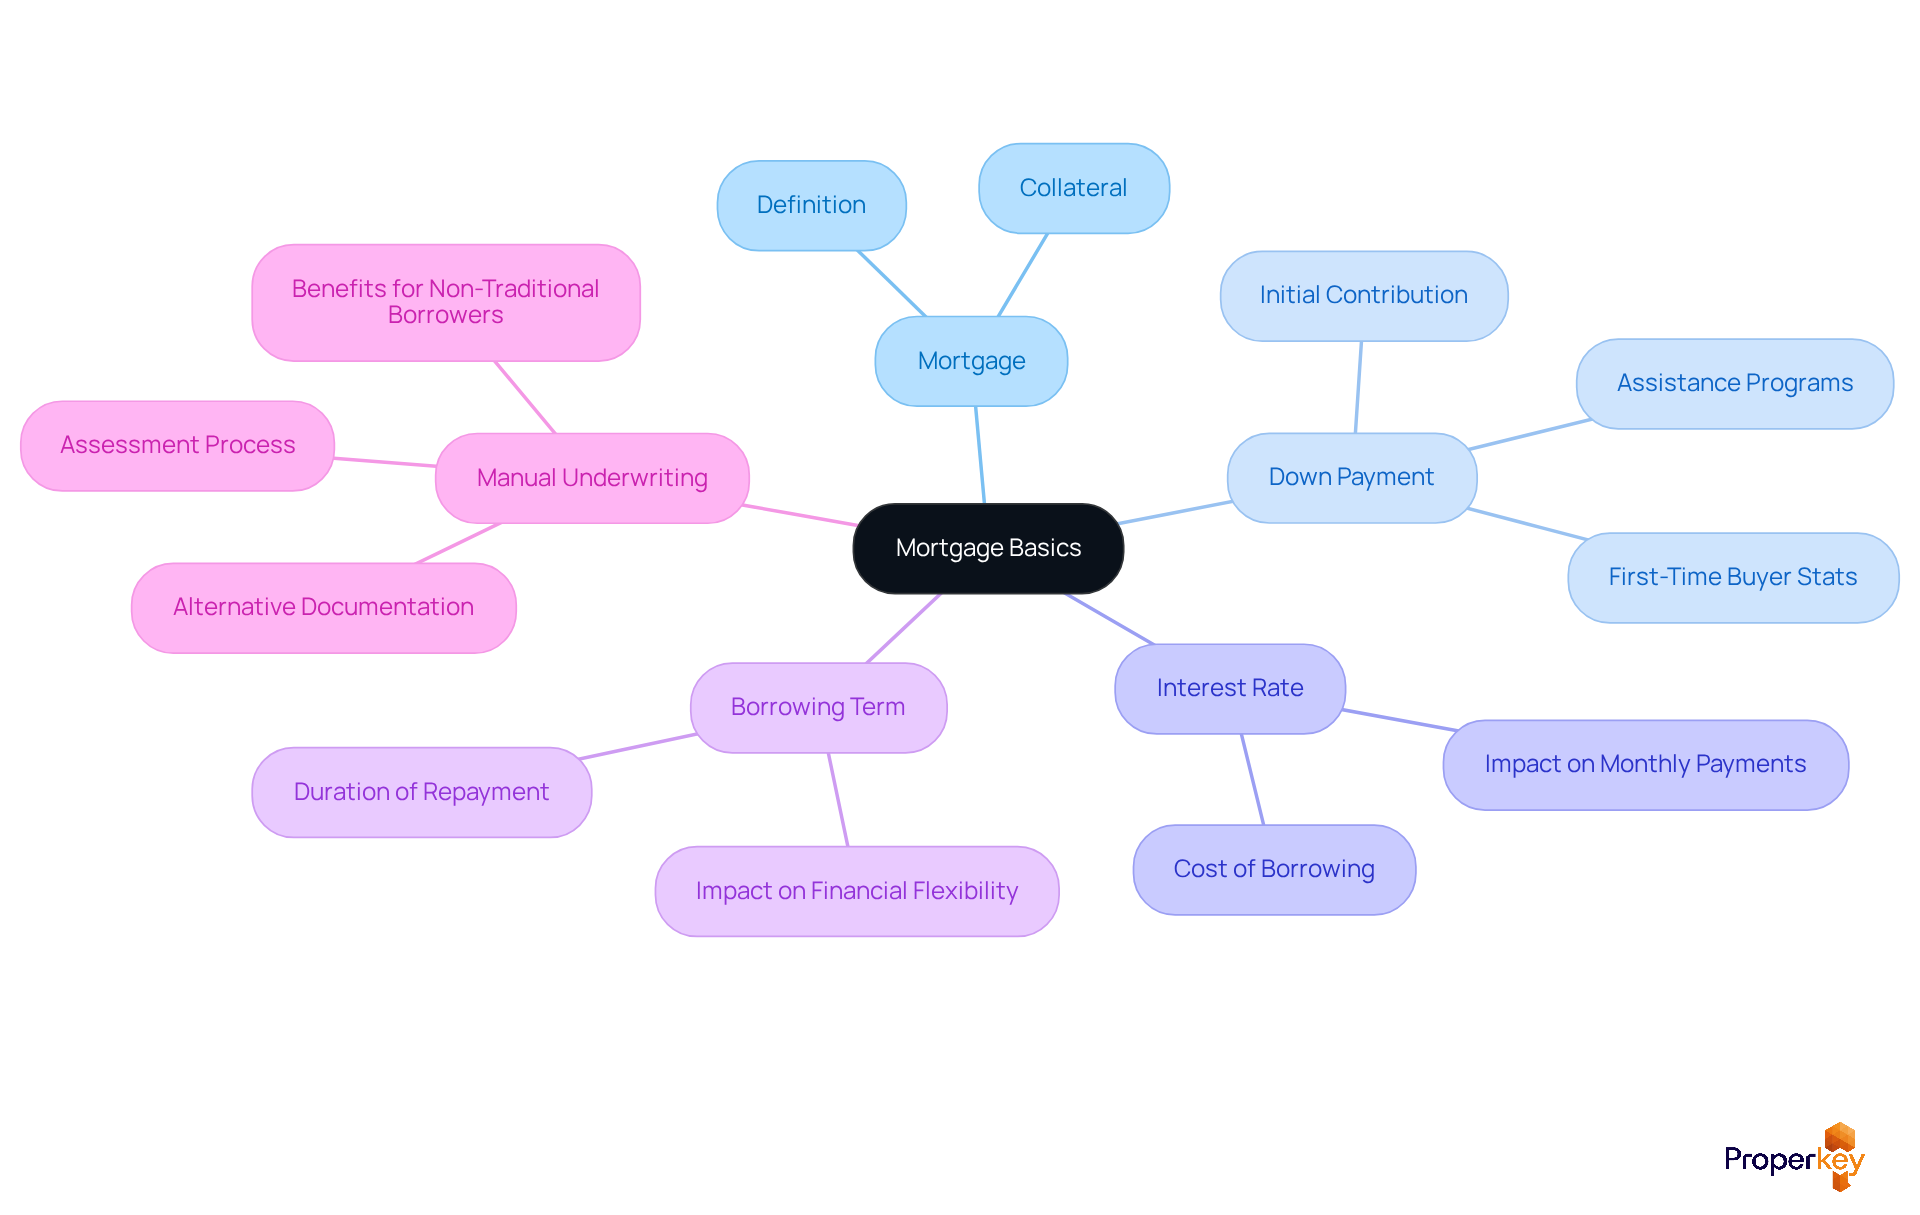
Navigating the mortgage landscape can be daunting, particularly when you wonder, can you get a mortgage with no credit history?. To make this journey smoother, it's essential to grasp some basic concepts:
- Mortgage: A loan specifically for purchasing real estate, where the property serves as collateral. In 2026, the average initial contribution for homes in California is approximately 19%, with first-time purchasers usually providing a deposit of 10%, the highest since 1989.
- Down Payment: The initial amount paid upfront when buying a home, typically expressed as a percentage of the purchase price. Many first-time buyers find the down payment to be a daunting hurdle, but down payment assistance programs are available to help alleviate this burden.
- Interest Rate: The cost of borrowing funds, usually expressed as a percentage of the borrowed amount. It's essential to grasp how interest rates influence your monthly payments, as this knowledge is key to effective budgeting.
- Borrowing Term: The duration over which the amount must be repaid, commonly 15 or 30 years. Choosing the right loan term can significantly impact your financial flexibility and total interest paid over time.
- Manual Underwriting: A procedure in which lenders assess a borrower's financial condition without relying solely on scoring systems, often considering alternative documentation like rental records and utility payments. This is especially advantageous for individuals lacking a conventional financial background.
By understanding these terms, you'll feel more confident exploring the mortgage options available to you, even if you don't have a traditional financial background. Financial advisors emphasize that lacking a credit score does not inherently indicate poor financial history or an inability to repay a mortgage, leading many to wonder, can you get a mortgage with no credit history?. With the right knowledge, you can unlock opportunities that others might overlook.
Explore Mortgage Options for No Credit History
Navigating the mortgage landscape can feel daunting, particularly when considering if you can get a mortgage with no credit history, but there are viable options available to help you achieve homeownership. Consider the following mortgage options:
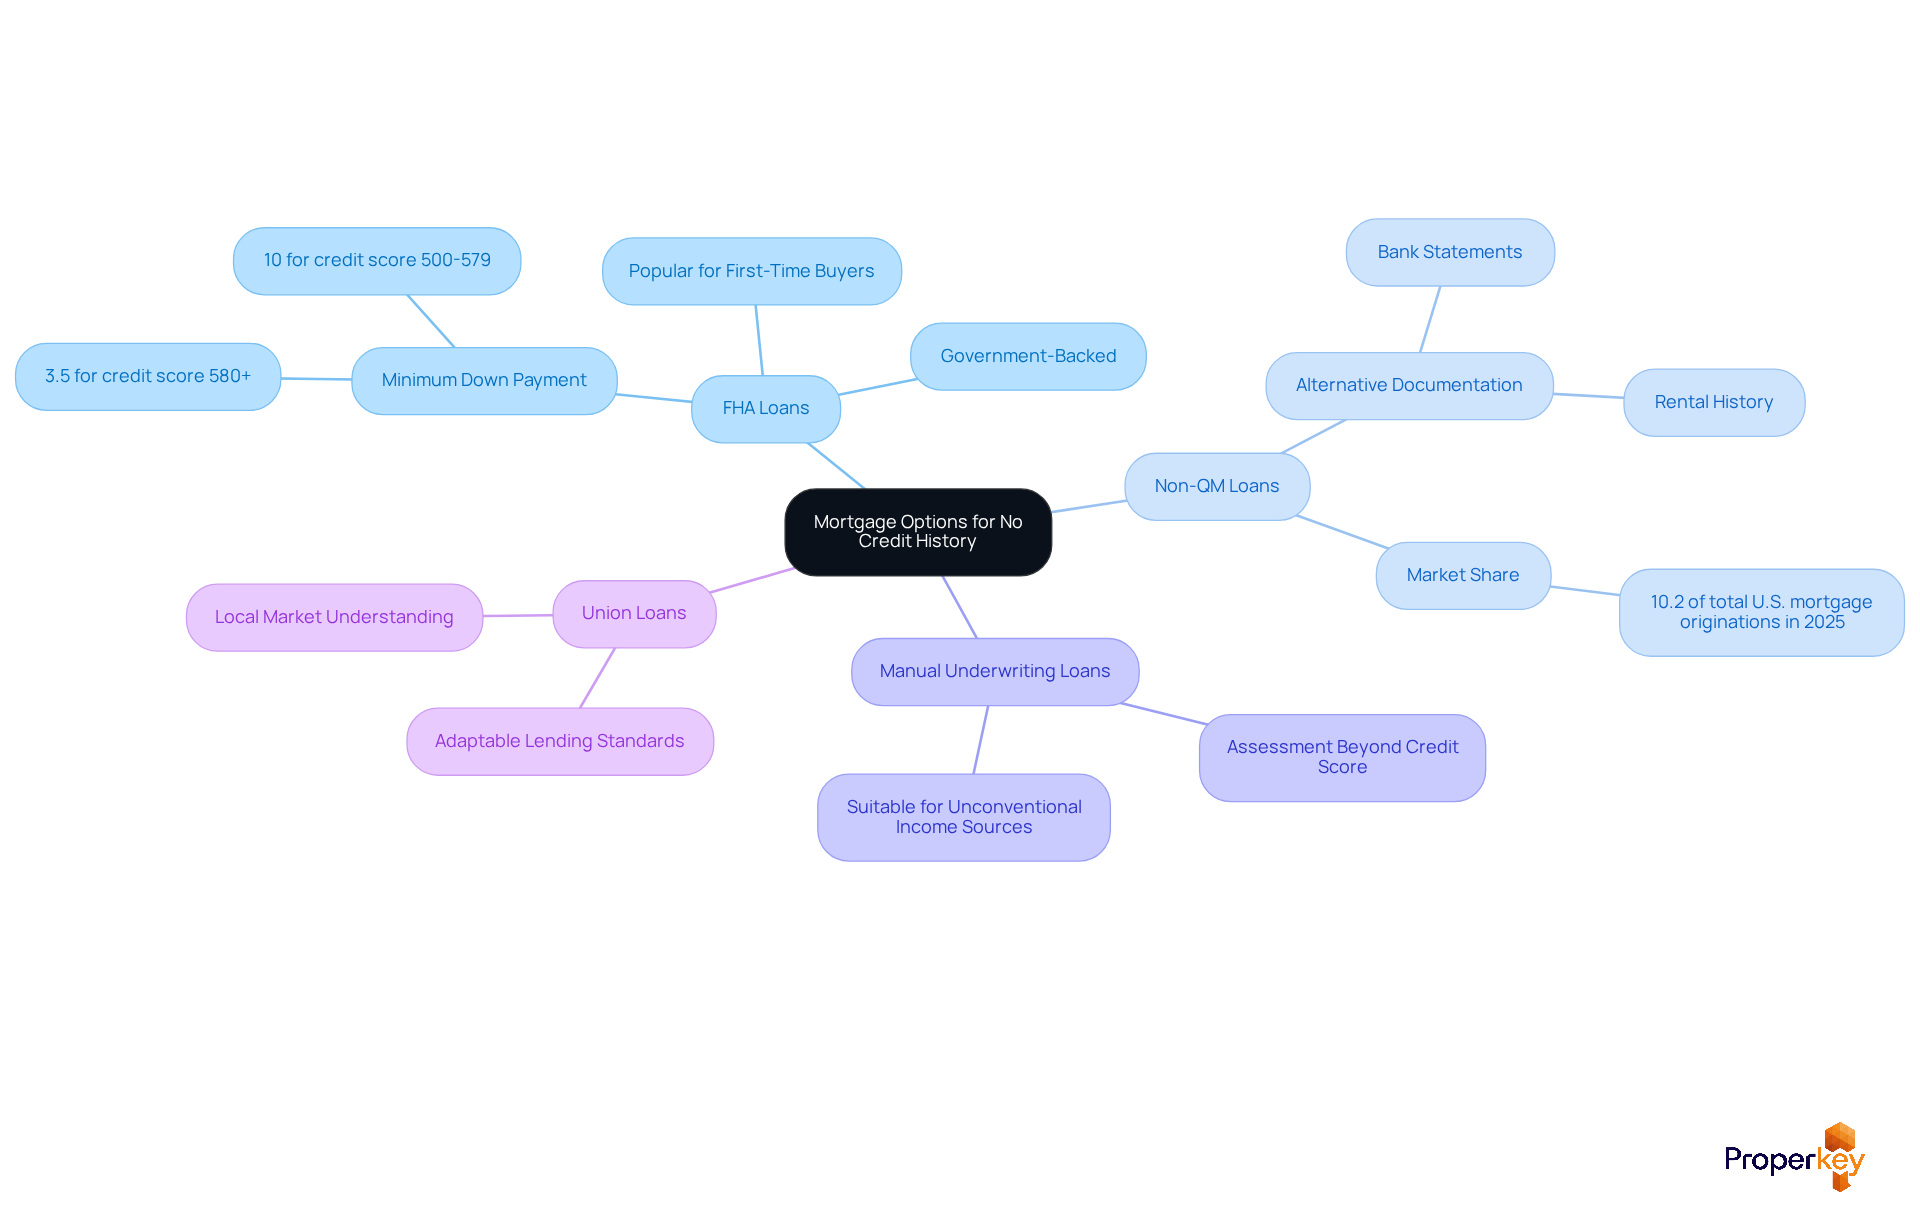
- FHA Loans: These government-backed loans are designed for borrowers with limited credit histories, allowing for a minimum down payment of just 3.5% for those with a credit score of 580 or higher. If your score falls between 500 and 579, a 10% down payment is required. FHA financing options provide a more accessible pathway to homeownership, making them a popular choice for first-time buyers in California. For detailed information, access FHA guidelines and borrowing limits through the HUD resources, which offer comprehensive support for navigating the mortgage process.
- Non-QM Loans: Non-Qualified Mortgages are tailored for borrowers who do not meet traditional lending criteria. These financial products often consider alternative documentation, such as bank statements or rental history, leading to the question of can you get a mortgage with no credit history, making them a feasible choice for individuals without a standard borrowing history. In 2025, Non-QM financing represented around 10.2% of total U.S. mortgage originations, indicating their increasing acceptance in the market.
- Manual Underwriting Loans: Some lenders provide loans that go through manual underwriting, allowing them to assess your financial situation based on factors beyond scoring. This method can be especially advantageous for individuals with unconventional income sources or those who have built a dependable payment record through rent.
- Union Loans: Local unions may offer more adaptable lending standards and tailored service, which can be beneficial for managing the mortgage process. They often have a better understanding of the local market conditions in California and Idaho, making them a valuable resource for first-time homebuyers.
By exploring these tailored mortgage solutions, you can take significant steps toward securing your dream home, even in a competitive market. Additionally, accessing resources from Fannie Mae, VA, FHA, HUD, and Freddie Mac can provide further guidance on conforming loan limits and financing options.
Strengthen Your Mortgage Application Without Credit
Navigating the mortgage application process can be daunting, particularly when considering if you can get a mortgage with no credit history. To enhance your mortgage application despite this challenge, consider the following strategies:
- Provide Alternative Documentation: Gather documents that demonstrate your financial reliability, such as bank statements, proof of income, and payment histories for rent or utilities. Lenders frequently accept alternative credit information, which can encompass regular rent contributions and utility bills, to evaluate your financial responsibility. According to Fannie Mae's Selling Guide, lenders need to see at least three types of bills paid consistently over 12-24 months.
- Increase Your Initial Contribution: A larger initial contribution can significantly reduce the lender's risk and enhance your chances of approval. In California, for example, striving for at least a 20% deposit can be advantageous, particularly considering the median home sales price of $792,800 as of December 2025. Properkey provides different loan programs that allow for reduced initial costs, including choices for borrowers with scores as low as 500, which can assist you in obtaining financing even with a limited financial history.
- Get a Co-Signer: If you have a family member or friend with good credit, consider asking them to co-sign your mortgage application. This can strengthen your application, as statistics show that having a co-signer can improve approval rates significantly, particularly in California where many lenders are more receptive to applications with additional support. As noted by financial expert Brian Walsh, "Down payment assistance programs and gifts from family members can help with affordability."
- Show Stable Employment: Lenders are more likely to favor applicants who show stable employment. Provide documentation of your employment background and income to demonstrate your financial stability. A consistent employment record can enhance your application, as lenders look for patterns of reliability in your financial behavior. Additionally, Properkey's specialized programs, such as those for seniors or renovation loans, can provide tailored solutions that fit your unique situation.
By implementing these strategies, you can significantly improve your chances of securing a mortgage, which raises the question: can you get a mortgage with no credit history even in challenging circumstances?
Leverage Local Lenders and Understand Underwriting
Navigating the mortgage landscape can be daunting, especially for those without a financial background. However, interacting with nearby lenders can significantly enhance your chances of securing a mortgage. Here are some key advantages:
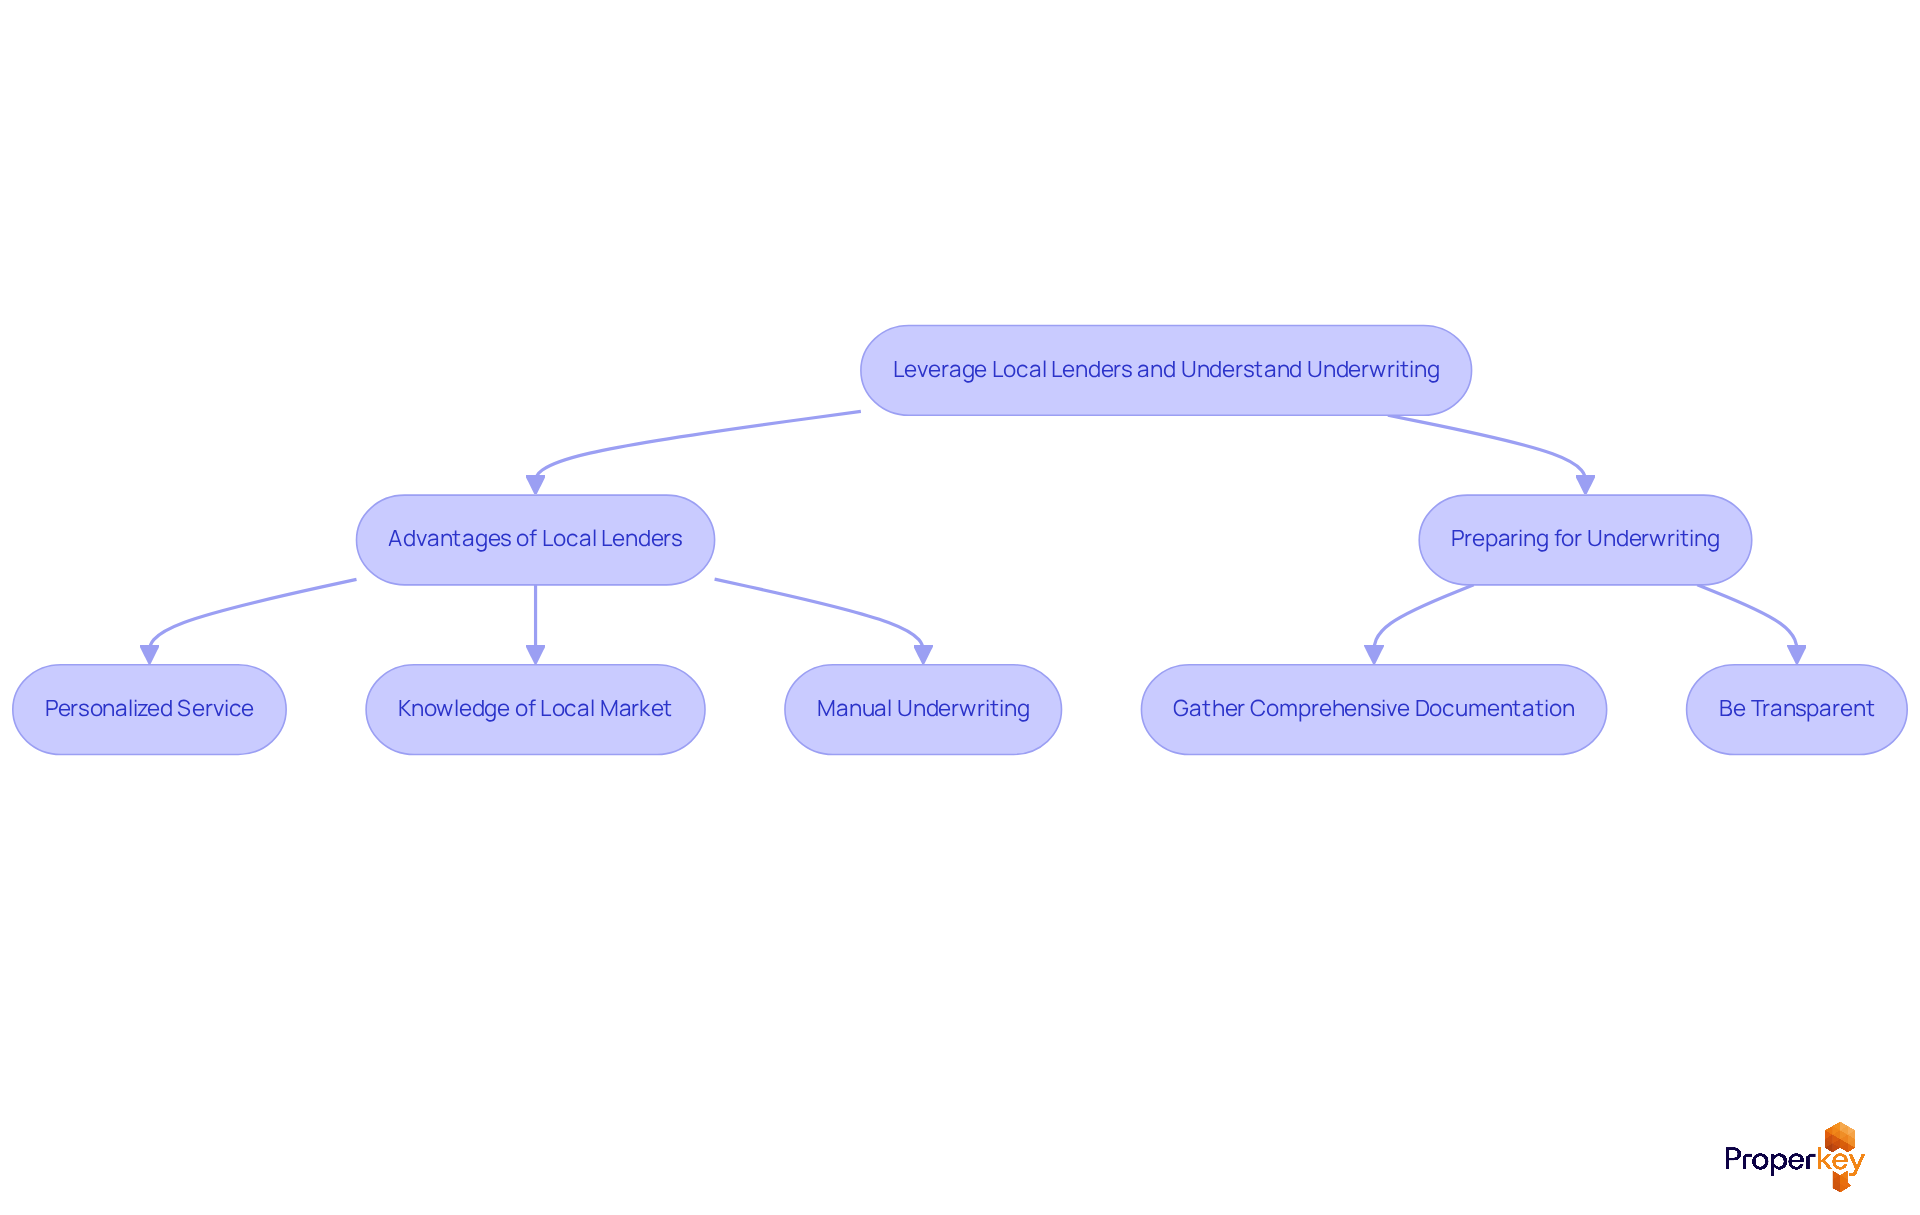
- Personalized Service: Local lenders are known for their commitment to personalized service. They often take the time to understand your unique financial situation and may be more flexible in crafting a mortgage solution that fits your needs.
- Knowledge of Local Market: With a deep understanding of the California real estate market, local lenders can provide insights that larger, national lenders might overlook. This local expertise can be invaluable in navigating property values and zoning laws.
- Manual Underwriting: Numerous local lenders are knowledgeable about manual underwriting procedures, which can be especially advantageous for borrowers wondering, can you get a mortgage with no credit history. This approach allows lenders to consider alternative forms of creditworthiness, such as consistent payment histories on rent or utilities.
Here’s how to prepare for the underwriting process:
- Gather Comprehensive Documentation: Be prepared to present detailed financial documentation, including income verification, bank statements, and any alternative references that demonstrate your financial reliability.
- Be Transparent: Open communication with your lender about your financial situation is crucial. Transparency fosters trust and can lead to a smoother underwriting process.
By leveraging the strengths of local lenders and understanding the nuances of the underwriting process, you can improve your chances of securing a mortgage tailored to your circumstances. Embrace the opportunity to work with local lenders and watch your mortgage options expand.
Build Your Credit for Future Mortgage Opportunities
Many home sellers struggle with establishing a solid credit history, leading to the concern of can you get a mortgage with no credit history. To build your credit for future mortgage options, consider the following steps:
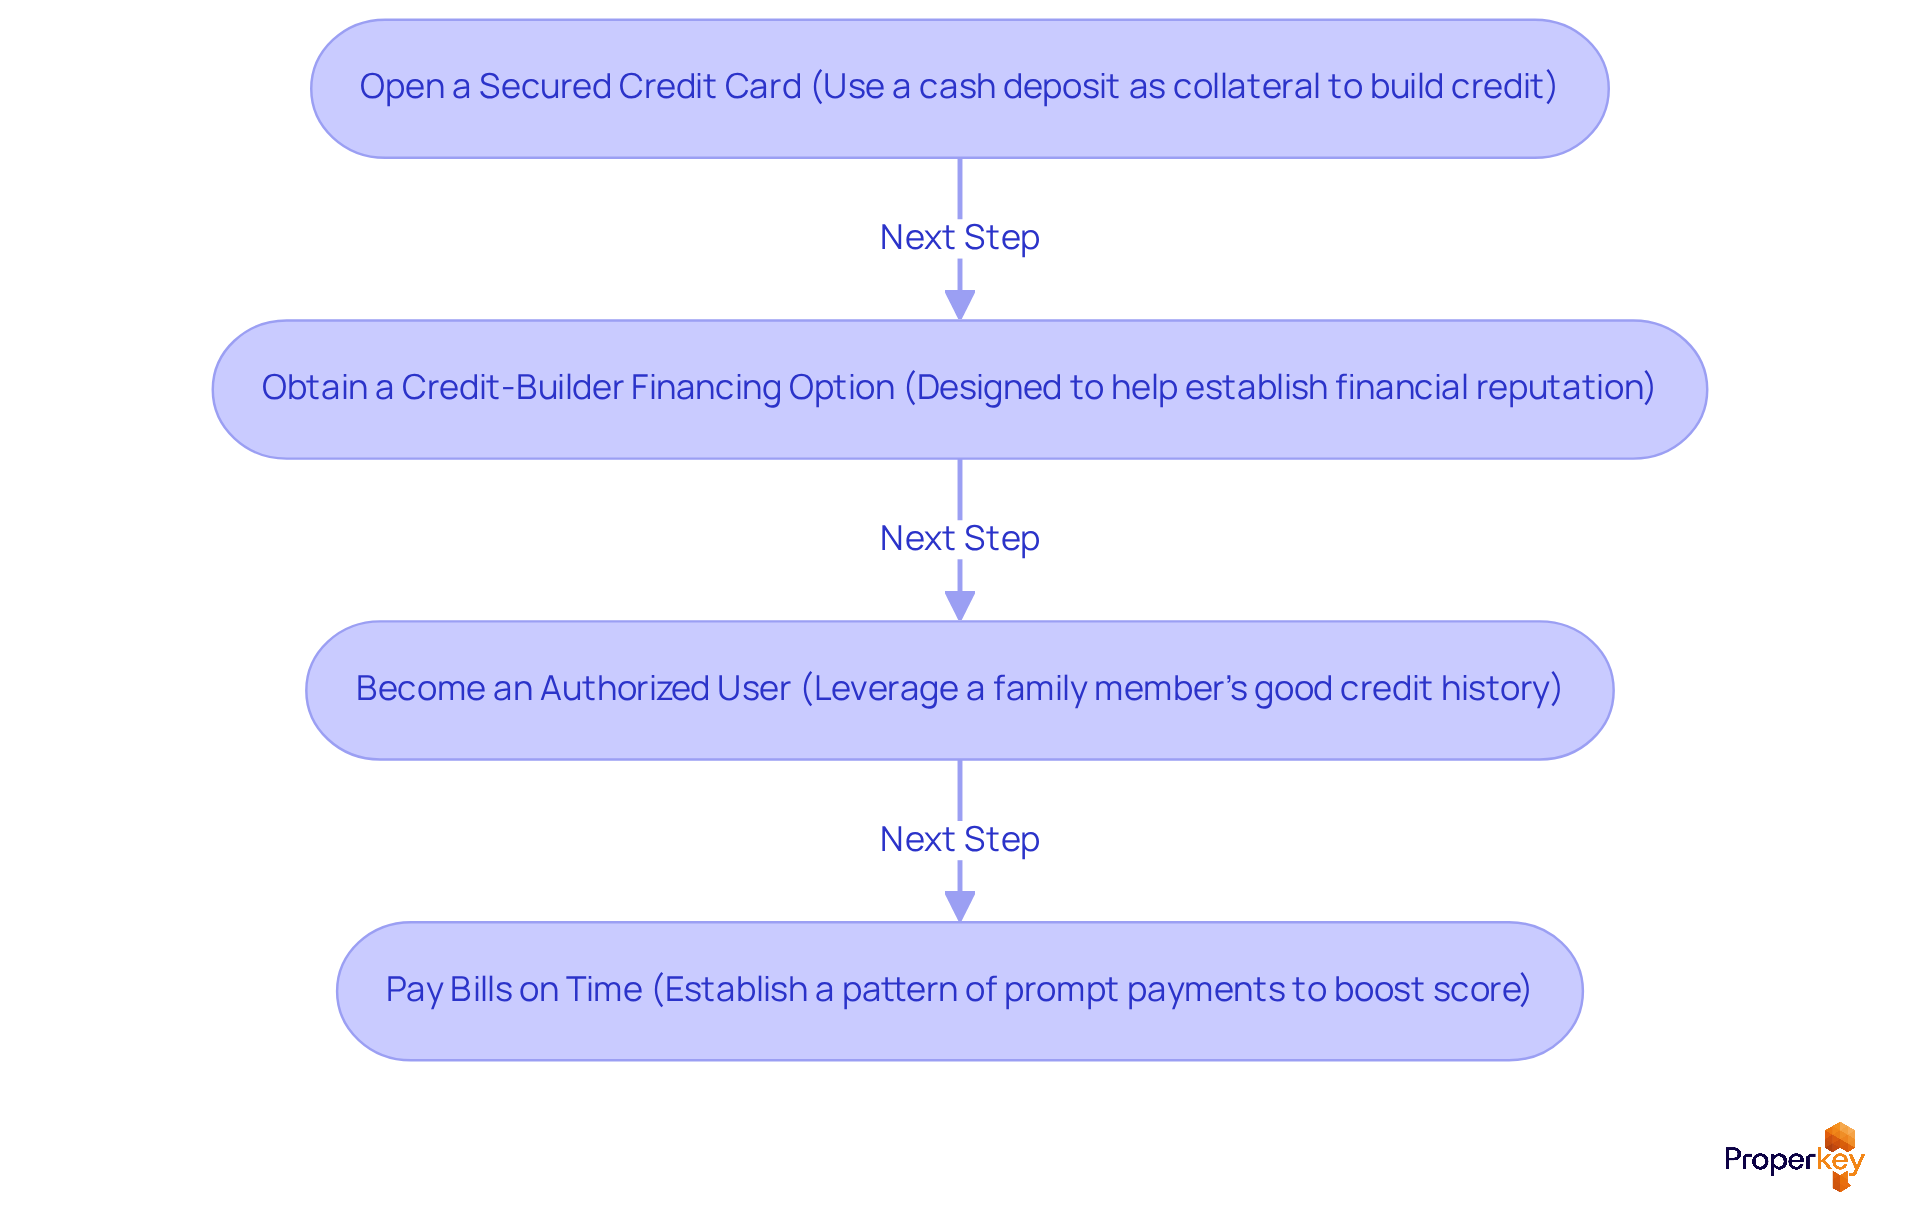
- Open a Secured Credit Card: A secured credit card needs a cash deposit as collateral. This makes it easier to get one. For instance, in Idaho, individuals have effectively utilized secured cards to create a favorable financial record by making minor purchases and settling the balance completely each month. This responsible usage can lead to enhanced scores over time. According to financial specialists, 'Using a secured charge card responsibly can assist you in establishing a solid financial record and reduce your expenses for borrowing funds in the future.'
- Obtain a Credit-Builder Financing Option: These financial products are specifically designed to assist individuals in establishing their financial reputation. In California, borrowers who consistently meet their obligations can significantly boost their financial profiles, as the contributions are reported to financial agencies, leading to a more robust financial history. In 2026, it was reported that individuals using builder loans experienced an average rise of 30 points in their scores within six months of regular payments.
- Become an Authorized User: Ask a family member or friend with a strong financial history if you can be added as an authorized user on their card. This strategy enables you to benefit from their favorable financial background without incurring debt, which can be especially advantageous for first-time purchasers in Nevada.
- Pay Bills on Time: Make it a habit to pay all your bills-utilities, rent, and more-on time. Creating a pattern of prompt payments can beneficially influence your score, as payment records make up approximately 35% of your FICO score. This habit is crucial for anyone asking, 'can you get a mortgage with no credit history?' while looking to secure favorable mortgage terms in the future.
By following these steps, you not only enhance your creditworthiness but also position yourself for better mortgage options down the line.
Conclusion
Many aspiring homeowners face a daunting challenge: securing a mortgage without a credit history. However, it’s entirely possible to achieve your dream of homeownership by understanding the various mortgage options available. Exploring options like FHA loans and Non-QM loans can empower you to take significant steps toward homeownership, especially when you know how to navigate the process effectively.
Key strategies for enhancing your mortgage application without a credit history include:
- Providing alternative documentation
- Increasing your initial contribution
- Showcasing stable employment history
These approaches can significantly improve your chances of approval, even in a competitive market. Additionally, building credit through secured credit cards and timely bill payments can pave the way for better mortgage opportunities in the future.
With the right strategies and support, you can transform your dream of homeownership into reality, regardless of your credit history. Embrace the possibilities and take proactive steps toward achieving financial stability and homeownership, as the right knowledge and resources can make all the difference.
Frequently Asked Questions
What is a mortgage?
A mortgage is a loan specifically for purchasing real estate, where the property serves as collateral.
What is a down payment?
A down payment is the initial amount paid upfront when buying a home, typically expressed as a percentage of the purchase price. Many first-time buyers find this to be a significant hurdle, but down payment assistance programs are available.
How do interest rates affect mortgages?
Interest rates represent the cost of borrowing funds, usually expressed as a percentage of the borrowed amount. Understanding how interest rates influence monthly payments is crucial for effective budgeting.
What is the typical borrowing term for a mortgage?
The typical borrowing term for a mortgage is commonly 15 or 30 years. The choice of loan term can significantly impact financial flexibility and the total interest paid over time.
What is manual underwriting?
Manual underwriting is a process where lenders assess a borrower's financial condition without relying solely on scoring systems, often considering alternative documentation like rental records and utility payments. This is beneficial for individuals without a conventional financial background.
Can you get a mortgage with no credit history?
Yes, it is possible to get a mortgage with no credit history. Understanding mortgage options available for individuals without a traditional financial background can help in achieving homeownership.
What are FHA loans?
FHA loans are government-backed loans designed for borrowers with limited credit histories, allowing for a minimum down payment of just 3.5% for those with a credit score of 580 or higher. If the score is between 500 and 579, a 10% down payment is required.
What are Non-QM loans?
Non-QM (Non-Qualified Mortgages) are tailored for borrowers who do not meet traditional lending criteria. They often consider alternative documentation, such as bank statements or rental history, making them a feasible choice for individuals without a standard borrowing history.
What are manual underwriting loans?
Manual underwriting loans are provided by some lenders who assess financial situations based on factors beyond scoring, which can be advantageous for individuals with unconventional income sources or a reliable payment record through rent.
What are union loans?
Union loans are offered by local unions and may have more adaptable lending standards and tailored service, which can be beneficial for managing the mortgage process, especially for first-time homebuyers.
List of Sources
- Understand Mortgage Basics Without Credit History
- How to Get a Mortgage with No Credit Score (https://waterstonemortgage.com/blog/mortgage-basics/2020/03/mortgage-no-credit-score)
- Let these key stats guide your homebuying journey in 2026 (https://rate.com/mortgage/resource/amazing-homeownership-stats)
- Buying a Home Without a Credit Score? New Rules Make It Possible (https://luminate.bank/buying-home-without-credit-score)
- The average down payment on a house in 2026 (https://finance.yahoo.com/personal-finance/mortgages/article/average-down-payment-on-a-house-182153085.html)
- Mortgages are now available for borrowers without credit scores (https://housingwire.com/articles/49615-mortgages-are-now-available-for-borrowers-without-credit-scores)
- Explore Mortgage Options for No Credit History
- Mortgages are now available for borrowers without credit scores (https://housingwire.com/articles/49615-mortgages-are-now-available-for-borrowers-without-credit-scores)
- Can You Get a Mortgage With No Credit History? (https://redfin.com/blog/mortgage-with-no-credit-history)
- California Non-QM Mortgage Market | Size, Lenders & Borrower Demand (https://polygonresearch.com/non-qm-market/california)
- FHA Loan Article Library (https://fha.com/fha_article?id=506)
- Non-QM Town Hall Highlights 2026 Growth Opportunities As Originators Shift Strategy (https://nationalmortgageprofessional.com/news/non-qm-town-hall-highlights-2026-growth-opportunities-originators-shift-strategy)
- Strengthen Your Mortgage Application Without Credit
- The average down payment on a house in 2026 (https://finance.yahoo.com/personal-finance/mortgages/article/average-down-payment-on-a-house-182153085.html)
- 7 Proven Ways to Buy a House with No Credit in 2026 (https://amerisave.com/learn/7-proven-ways-to-buy-a-house-with-no-credit)
- Can You Get a Mortgage With No Credit History? (https://redfin.com/blog/mortgage-with-no-credit-history)
- What Is the Average Down Payment on a House? (https://sofi.com/learn/content/average-down-payment-on-a-house)
- Buying a Home Without a Credit Score? New Rules Make It Possible (https://luminate.bank/buying-home-without-credit-score)
- Leverage Local Lenders and Understand Underwriting
- Local Mortgage Lenders vs. National: Why the Local Lender Wins | Liberty Bank (https://libertybank.com/local-mortgage-lenders-vs-national-why-the-local-lender-wins)
- The benefits of working with a local lender for your home mortgage (https://minnwestbank.com/insights/the-benefits-of-working-with-a-local-lender-for-your-home-mortgage)
- 5 reasons to work with a local lender | Mortgage Equity Partners (https://mortgageequitypartners.com/5-reasons-to-work-with-a-local-lender)
- 5 Benefits of Using a Local Home Mortgage Lender - Piscataqua Savings Bank (https://piscataqua.com/local-mortgage-lender-benefits)
- Home Loans & The Benefits of Working with a Local Lender - Rollstone Bank (https://rollstonebank.com/home-loans-the-benefits-of-working-with-a-local-lender)
- Build Your Credit for Future Mortgage Opportunities
- How to Build Credit: 7 Key Steps (https://pnc.com/insights/personal-finance/borrow/7-steps-to-building-strong-credit.html)
- How to Build Credit - Establish Credit - Wells Fargo (https://wellsfargo.com/financial-education/credit-management/build-credit)
- How to Build Your Credit Successfully - Intuit Blog (https://intuit.com/blog/innovative-thinking/financial-tips/build-credit)
- How to establish credit (https://cnbc.com/select/how-to-build-credit-with-no-credit-history)
- What are some ways to start or rebuild a good credit history? | Consumer Financial Protection Bureau (https://consumerfinance.gov/ask-cfpb/what-are-some-ways-to-start-or-rebuild-a-good-credit-history-en-2155)



