Jumbo Loans in California (November 2026): Where the Line Is, What Jumbo Rates Are Doing, and the Down Payment, Credit and Reserve Rules

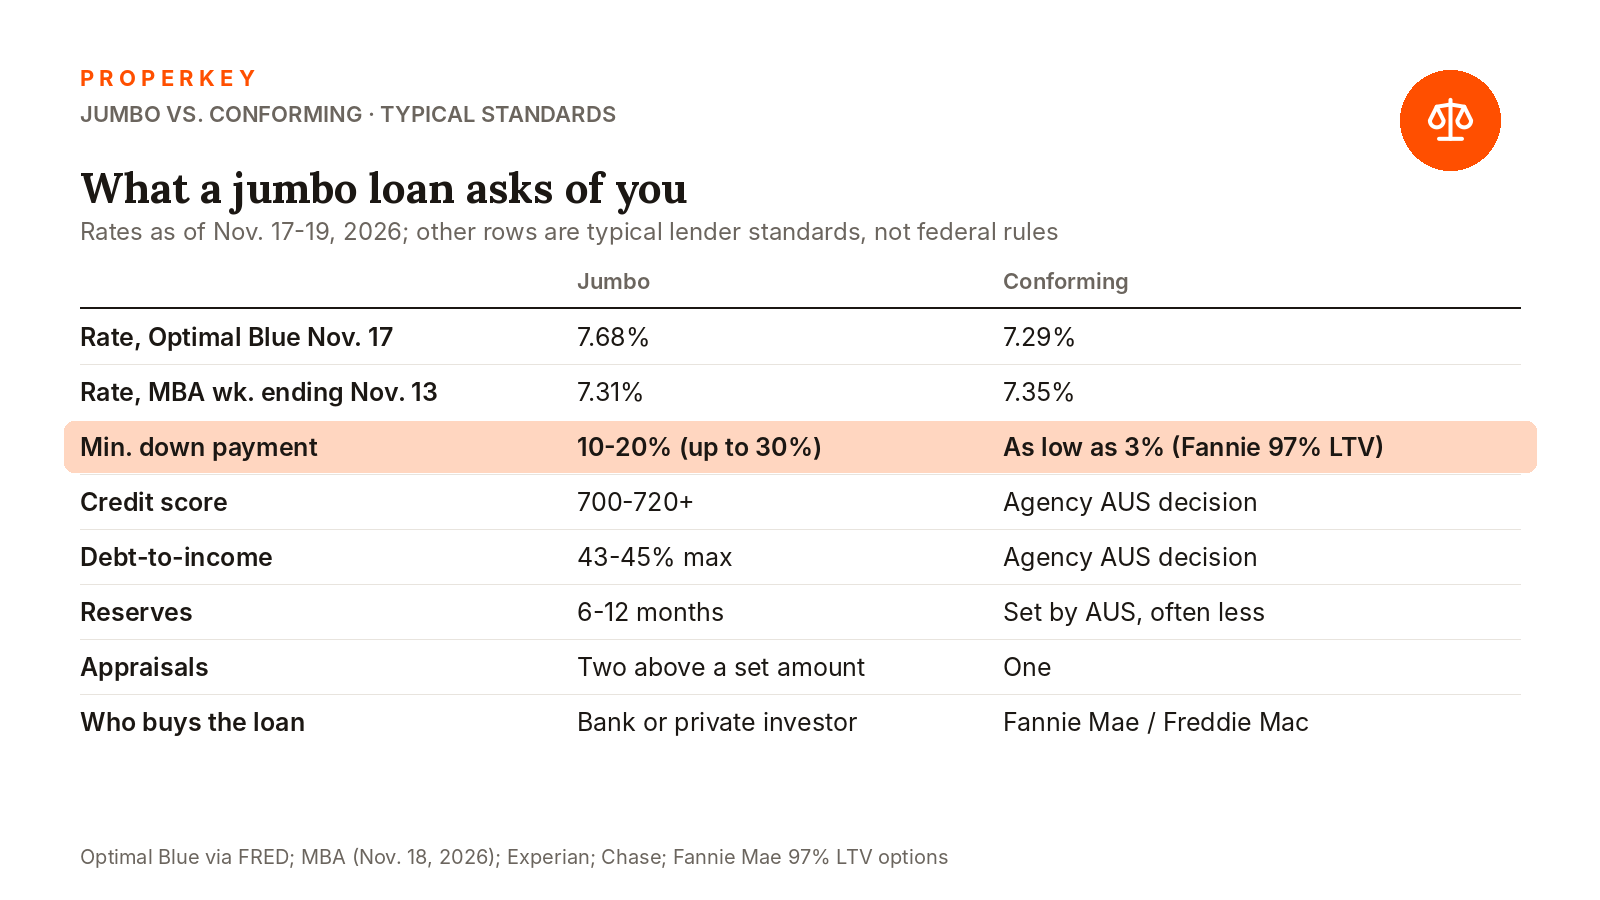
A jumbo loan in California is any mortgage larger than your county's 2026 conforming limit: $832,750 in 41 of 58 counties, $1,249,125 in Los Angeles, Orange and the core Bay Area counties, and in-between figures such as San Diego's $1,104,000 and Ventura's $1,035,000, per FHFA's Nov. 25, 2025 announcement and 2026 county list. Above that line Fannie Mae and Freddie Mac cannot buy the loan, so the lender keeps it or sells it privately, and the rate, down payment and paperwork change. As of Nov. 19, 2026, Optimal Blue's daily lock index put the 30-year jumbo rate at 7.68% on Nov. 17 against 7.29% for conforming (FRED), while the Mortgage Bankers Association's weekly survey had jumbo slightly below conforming, 7.31% vs. 7.35%, for the week ending Nov. 13 (MBA, Nov. 18). Both are right; they measure different things.
Which California counties have higher limits?
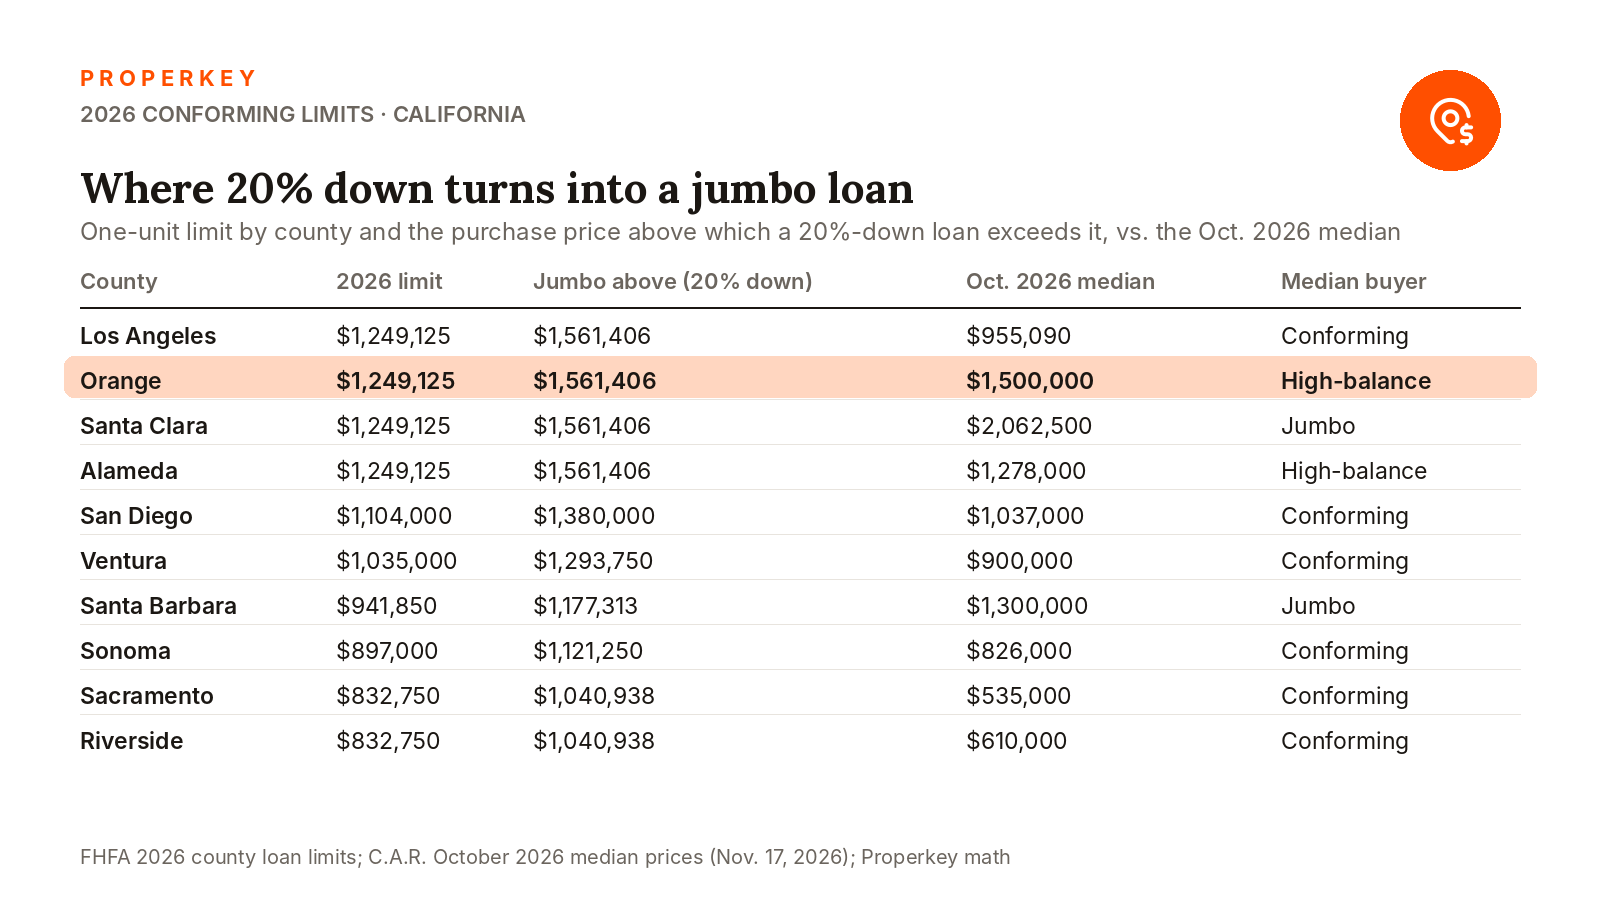
Federal law sets a national baseline each year and lets FHFA raise it where 115% of the local median home value exceeds it, capped at 150% of the baseline. For 2026 that is $832,750 (up 3.26%, matching FHFA's house price index for Q3 2024 to Q3 2025) and a $1,249,125 ceiling (FHFA). Only the loan amount counts, not the price. FHFA's 2026 county spreadsheet puts Sacramento, Riverside, San Bernardino, Fresno, Placer, Solano, San Joaquin and 34 other counties at $832,750. Seventeen are higher: Los Angeles, Orange, San Francisco, San Mateo, Santa Clara, Alameda, Contra Costa, Marin, Santa Cruz and San Benito at the $1,249,125 ceiling; San Diego $1,104,000; Ventura $1,035,000; Napa $1,017,750; San Luis Obispo $1,000,500; Monterey $994,750; Santa Barbara $941,850; Sonoma $897,000. With 20% down, the price at which your loan turns jumbo is the limit divided by 0.8: $1,040,938 in a baseline county, $1,380,000 in San Diego, $1,561,406 in Los Angeles or Orange County.
What is a "high-balance" loan, and why does the label matter?
A conforming loan above $832,750 but within your county's higher limit is a "high-balance" conforming loan. Fannie Mae still buys it under Selling Guide B5-1-01 (July 2, 2025), which requires a conventional first lien run through Desktop Underwriter at the LTVs in its eligibility matrix. High-balance pricing runs a little above baseline conforming but is still agency-backed, so it is not what people mean by "jumbo rates," and agency features such as Fannie Mae's 3%-down 97% LTV options have no jumbo equivalent.
What are jumbo mortgage rates right now?
Optimal Blue (daily, actual locks): 30-year jumbo 7.677% on Nov. 17, 2026, up from 7.288% on Nov. 12; conforming 7.286% the same day (FRED jumbo, FRED conforming). On Nov. 18 the readings were 7.421% and 7.258%, so the spike narrowed by a quarter point in a day.
MBA Weekly Applications Survey (week ending Nov. 13): conforming 7.35% (from 7.21%), jumbo 7.31% (from 7.21%), FHA 7.06%, 5/1 ARM 6.38%; purchase applications 18% below a year earlier (MBA, Nov. 18, 2026).
Freddie Mac PMMS (Nov. 19): 30-year 7.28%, up from 7.11%; 15-year 6.66% (Freddie Mac). PMMS covers conforming loans only.
Optimal Blue's October report averaged jumbo at 7.36% against 7.15% conforming, with adjustable-rate loans at 17% of locks, up from 14% in September and the highest in its data back to 2019 (Market Advantage, Nov. 10, 2026). ARMs are especially common in jumbo lending because banks that hold jumbos prefer loans that reset with their funding costs.
Why do the surveys disagree?
Optimal Blue averages rates actually locked each day across roughly a third of U.S. transactions, so its jumbo line is a true jumbo bucket and jumps on thin days. The MBA survey collects weekly offered rates on 80% LTV loans and defines jumbo as any balance above $832,750 (MBA), which in California sweeps agency-priced high-balance loans into the jumbo column and pulls that average down. The spread also genuinely flips: in the FRED data since January 2025, Optimal Blue's jumbo index closed below conforming on 39 trading days, most recently Nov. 2, 2026 (7.048% vs. 7.130%). Jumbos carry no Fannie or Freddie guarantee fee and are often held by banks courting deposit relationships, so a strong borrower's jumbo quote can beat conforming; when bank appetite thins, it swings the other way.
What do lenders typically require for a jumbo loan?
There is no agency rulebook, so each lender sets its own standards. The pattern described by Experian (Oct. 30, 2025) and Chase's jumbo guide is typical: 10% down at minimum and often 20%, with some lenders asking up to 30%; a credit score of 700 at the floor and 720 or better for many programs; debt-to-income no higher than about 43%, with better terms under 36%; six to twelve months of payments in reserves; two years of tax returns, plus business returns or profit-and-loss statements if self-employed; and two appraisals above a lender-set loan amount. Treat these as the center of the range: a bank may stretch for a borrower with large deposits and tighten for a condo or second home.
Are jumbo loans qualified mortgages?
Yes, if they pass the same test as any other loan. Since the Temporary GSE QM expired on Oct. 1, 2022 (CFPB), a loan is a general qualified mortgage under 12 CFR 1026.43(e)(2) when its term is 30 years or less, points and fees stay within the caps, the lender considers and verifies income, assets and debts, and the APR is less than 2.25 percentage points above the average prime offer rate for first liens of $110,260 or more (indexed). The 43% DTI cap is gone from the federal definition; the 43% to 45% on jumbo term sheets is lender policy. Bank-statement and asset-depletion jumbos that skip the verification rules are non-QM; Optimal Blue counted non-QM at 12% of October production. They close, but they cost more and the lender has less legal protection, so they are a fallback, not a plan.
Does a median-priced buyer in Los Angeles or Orange County need a jumbo?
Usually not. C.A.R.'s October 2026 report puts the median single-family price at $955,090 in Los Angeles County and $1,500,000 in Orange County (C.A.R., Nov. 17, 2026). At 20% down the Los Angeles loan is $764,072, under even the $832,750 baseline. The Orange County loan is $1,200,000: above the baseline, but $49,125 below the $1,249,125 county limit, so it is high-balance conforming, not jumbo. San Diego's $1,037,000 median yields an $829,600 loan, just under baseline. Jumbo is unavoidable at the median only where prices run far past the ceiling: San Francisco ($2,390,000 median, $1,912,000 loan), San Mateo, Santa Clara, Marin, and Santa Barbara, where a $1,300,000 median against a $941,850 limit leaves a $1,040,000 loan over the line.
When you do cross it, the gap is real money. On a $1,400,000 loan, 7.68% versus 7.29% is $9,962 against $9,588 a month, a $374 difference, about $4,484 a year. At the Nov. 18 readings (7.42% vs. 7.26%) the gap is $152 a month, and at the MBA figures the jumbo payment is $38 lower. The spread you lock matters more than the headline.
What changes in 2027?
FHFA announces the 2027 limits in late November; as of Nov. 19, 2026, it has not posted them. More than 50 lenders already honor unofficial 2027 baselines of $845,000, $847,440 or $850,000 (The Mortgage Reports, Nov. 17, 2026), a race that began Sept. 10 when CrossCountry and Rocket moved to $845,000 (HousingWire). Properkey's county-by-county look is at 2027 conforming loan limits in California. If your loan sits within about $15,000 above today's limit, ask whether the lender is using an early 2027 figure before you accept jumbo pricing.
Where Properkey fits
Jumbo pricing varies more between lenders than conforming pricing does, because each bank sets its own appetite, so a loan near a county line should be priced both ways on the same day. Properkey's finance desk works the way its page says: "Purchase or refinance, you apply once. We shop the lenders, you pick the terms" (properkey.us/finance). For the wider map of loan types, see What types of home loans are there in California?; if a jumbo ARM is on the table, the reset math is in What is an adjustable-rate mortgage?.
Questions people ask
What is the jumbo loan limit in California for 2026?
There is no single California number. A loan is jumbo above $832,750 in 41 counties; above $1,249,125 in Los Angeles, Orange, San Francisco, San Mateo, Santa Clara, Alameda, Contra Costa, Marin, Santa Cruz and San Benito; and above $1,104,000 in San Diego, $1,035,000 in Ventura, $1,017,750 in Napa, $1,000,500 in San Luis Obispo, $994,750 in Monterey, $941,850 in Santa Barbara and $897,000 in Sonoma, per FHFA's 2026 county list.
Are jumbo rates higher than conforming rates right now?
It depends on the measure. Optimal Blue's daily lock index showed jumbo at 7.68% vs. 7.29% conforming on Nov. 17, 2026, narrowing to 7.42% vs. 7.26% on Nov. 18, while the MBA weekly survey for the week ending Nov. 13 had jumbo at 7.31% and conforming at 7.35%. The gap has flipped sign repeatedly since early 2025, so get both quotes priced the same day.
How much do you need down for a jumbo loan?
Typical lender standards are 10% to 20% down, with some programs asking up to 30%, alongside a 700 to 720-plus credit score, a debt-to-income ratio of roughly 43% to 45% or less and six to twelve months of payments in reserve. These are lender policies, not federal rules, and they vary by bank, property type and loan size.
Is a $1,200,000 loan in Orange County a jumbo?
No. Orange County's 2026 conforming limit is $1,249,125, so a $1,200,000 loan is a high-balance conforming loan that Fannie Mae and Freddie Mac can buy. It becomes a jumbo only above $1,249,125, which at 20% down means a purchase price above $1,561,406.
This is a summary of the rules, not legal, tax or lending advice; limits, rates and lender standards change, and your eligibility depends on a full application.
Sources: FHFA, conforming loan limit values for 2026 (Nov. 25, 2025); FHFA 2026 full county loan limit list; Fannie Mae Selling Guide B5-1-01; Fannie Mae 97% LTV options; Optimal Blue 30-year jumbo index (FRED); Optimal Blue 30-year conforming index (FRED); MBA Weekly Applications Survey, week ending Nov. 13, 2026; Freddie Mac PMMS; Optimal Blue Market Advantage, October 2026 (Nov. 10, 2026); C.A.R. October 2026 report (Nov. 17, 2026); Experian, What is a jumbo loan?; Chase, applying for a jumbo loan; 12 CFR 1026.43 (eCFR); CFPB, April 2021 ATR/QM executive summary; The Mortgage Reports, 2027 limits preview (Nov. 17, 2026); HousingWire (Sept. 10, 2026); Properkey Finance.
Written by Keyro, Properkey's AI. Properkey, DRE #01979718.



