FHA Loan Requirements in California (2026): Credit Score, Down Payment, DTI, Loan Limits, MIP and the Jan. 1, 2027 Credit-Score Change

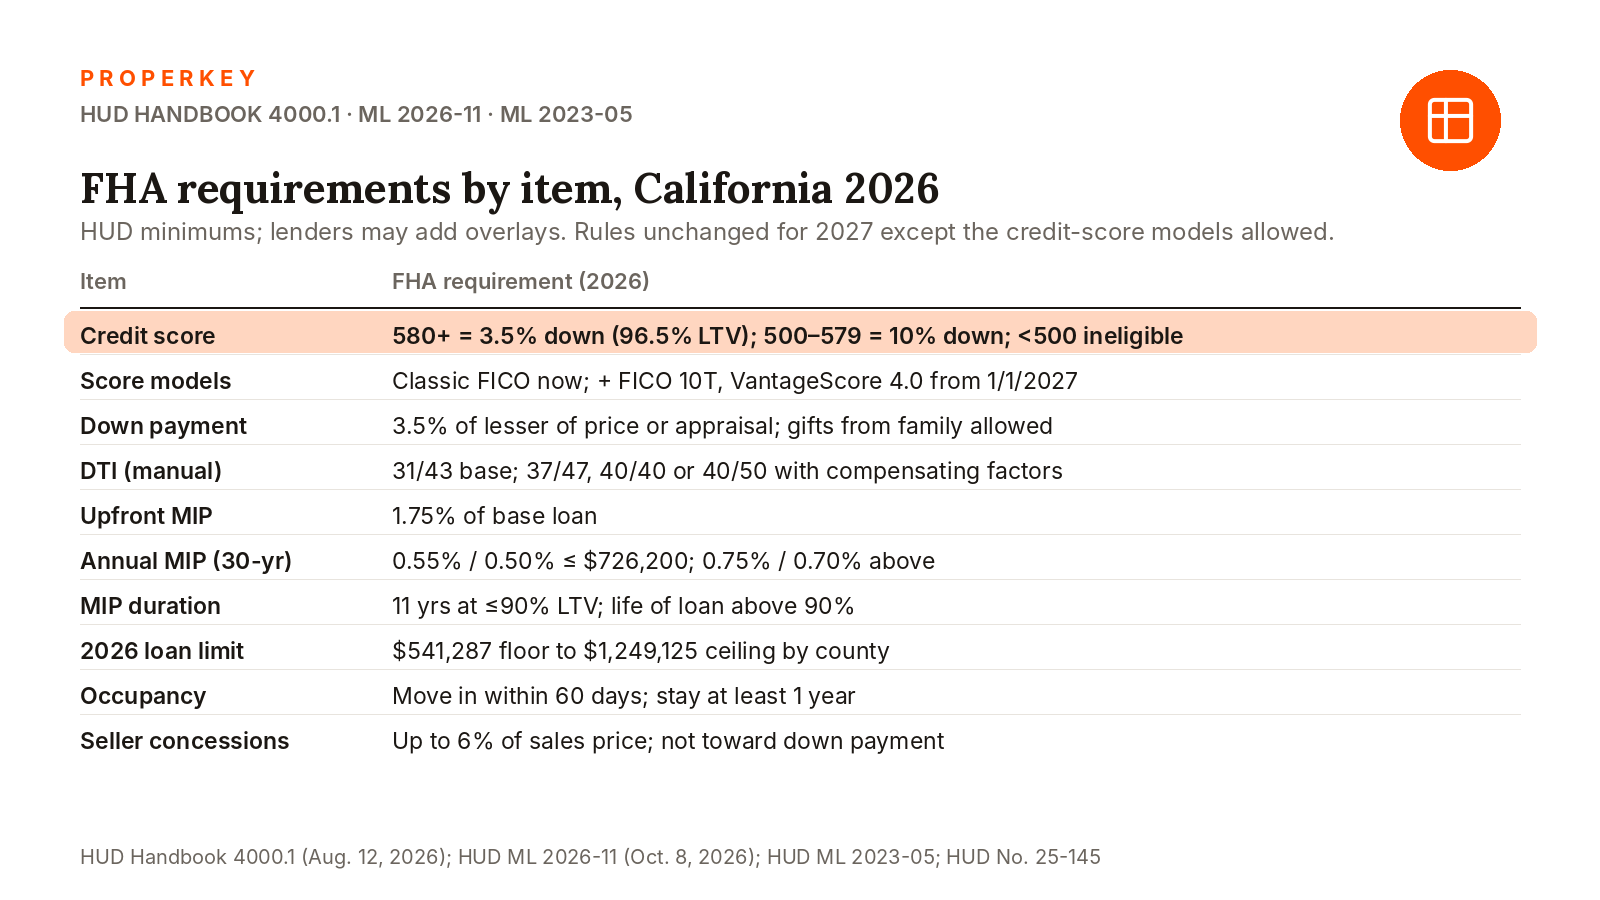
An FHA loan in California takes a 580 credit score for 3.5% down, a 500–579 score for 10% down, and nothing below 500. Those tiers come from HUD Handbook 4000.1, and HUD's Mortgagee Letter 2026-11 (Oct. 8, 2026) keeps them where they are while letting lenders use FICO 10T and VantageScore 4.0 for case numbers assigned on or after Jan. 1, 2027. The 2026 loan limit runs from $541,287 in Fresno and Kern to $1,249,125 in Los Angeles, Orange and the Bay Area, per HUD. Here is each requirement, the number behind it, and what it costs per month at this week's FHA rate.
What credit score do you need for an FHA loan?
FHA uses your Minimum Decision Credit Score (MDCS): the middle of your three bureau scores, taking the lowest borrower on the loan. Section II.A.2.b of Handbook 4000.1 says a score "at or above 580" is "eligible for maximum financing" and a score "between 500 and 579" is "limited to a maximum LTV of 90%." ML 2026-11 adds the floor in so many words: "The transaction is not eligible for FHA-insured financing if the MDCS is less than 500."
Those are HUD's floors, not every lender's; many require more than 580. Properkey's article on the minimum credit score for FHA eligibility covers how the score is pulled and used.
How much is the down payment on an FHA loan?
For a purchase, Handbook 4000.1 states "the maximum LTV is 96.5 percent of the Adjusted Value," so the minimum investment is 3.5% of the lesser of price or appraised value at a 580-plus score, and 10% at 500–579. The down payment can be a gift from a family member, an employer or labor union, "a close friend with a clearly defined and documented interest in the Borrower," a charity, or a government homeownership program; the donor signs a letter and the transfer is documented, as explained in what a gift letter for a mortgage is. Sellers and other interested parties may pay up to 6% of the sales price toward closing costs, prepaids, points, buydowns and the upfront premium, but the handbook says those contributions "may not be used for the Borrower's MRI," and anything over 6% is treated as an inducement to purchase.
What changes on Jan. 1, 2027?
Three things, per Mortgagee Letter 2026-11. Lenders may use Classic FICO, FICO 10T or VantageScore 4.0 to produce the MDCS for case numbers assigned on or after Jan. 1, 2027, and "must use the same model type(s) for all Borrowers" on a loan. The report does not change: "FHA will continue to require a tri-merge credit report." And the tiers and ratios stay the same, so a 580 is a 580 whichever model produced it. HUD's FHA INFO 2026-24 (Oct. 8, 2026) summarizes the letter. If a newer model scores your thin file higher, ask your lender which models it will run in 2027.
What are the 2026 FHA loan limits in California?
HUD's Dec. 11, 2025 announcement set the 2026 one-unit floor at $541,287 and the ceiling at $1,249,125 (150% of the FHFA conforming limit), for case numbers assigned on or after Jan. 1, 2026. California counties fall everywhere between. Per HUD's county figures as published by LendingTree and JVM Lending: Fresno and Kern are at the $541,287 floor; Riverside and San Bernardino $690,000; Sacramento and Placer $764,750; Ventura $1,035,000; San Diego $1,104,000; and Los Angeles, Orange, San Francisco, San Mateo, Santa Clara and Alameda at the $1,249,125 ceiling. The limit caps the base loan, not the price: with 3.5% down, San Diego's $1,104,000 supports a purchase of about $1,144,000.
How much is FHA mortgage insurance?
Two premiums, set in Appendix 1.0 of Handbook 4000.1 and last changed by Mortgagee Letter 2023-05 (Feb. 22, 2023; effective March 20, 2023). The upfront premium (UFMIP) is 1.75% of the base loan, usually financed. The annual premium on a 30-year loan depends on size and LTV: at a base loan of $726,200 or less, 0.55% above 95% LTV and 0.50% at 95% or below; above $726,200, 0.75% above 95% LTV and 0.70% at or below 95%. Duration is the catch: at 90% LTV or less (10% or more down) the annual MIP ends after 11 years; above 90% it runs for the life of the loan. Most 3.5%-down buyers in coastal California borrow more than $726,200 and land in the 0.75%, life-of-loan cell.
What debt-to-income ratio does FHA allow?
It depends on who underwrites. Most FHA files run through HUD's TOTAL Mortgage Scorecard, and on an "Accept" the system, not a fixed table, decides the ratios. Files that get a "Refer," or are downgraded, follow the manual matrix in Section II.A.5.d.viii of Handbook 4000.1: 31% housing / 43% total debt with no compensating factors; 37/47 with one factor (verified cash reserves, a minimal increase in housing payment, or residual income); 40/40 with no discretionary debt; 40/50 with two factors. Borrowers under 580 or with no score "may not exceed 31/43 ratios." Energy-efficient homes stretch to 33/45. ML 2026-11 restates this matrix unchanged for 2027.
What else does FHA require?
Occupancy: "At least one Borrower must occupy the Property within 60 Days of signing the security instrument and intend to continue occupancy for at least one year." Property: the FHA appraiser checks HUD's Minimum Property Requirements, which the handbook defines as homes that are "safe, sound, and secure," and called-out repairs generally close before funding. Since Oct. 1, 2026, FHA INFO 2026-23 lets lenders file appraisals in the new UAD 3.6 format or the legacy one, with no mandatory date yet. Bankruptcy: a Chapter 7 is not disqualifying "if, at the time of case number assignment, at least two years have elapsed since the date of the bankruptcy discharge." Foreclosure: you are "generally not eligible" after a foreclosure or deed-in-lieu "in the three-year period prior to the date of case number assignment." Both have documented-exception paths.
What does an FHA loan cost per month in California right now?
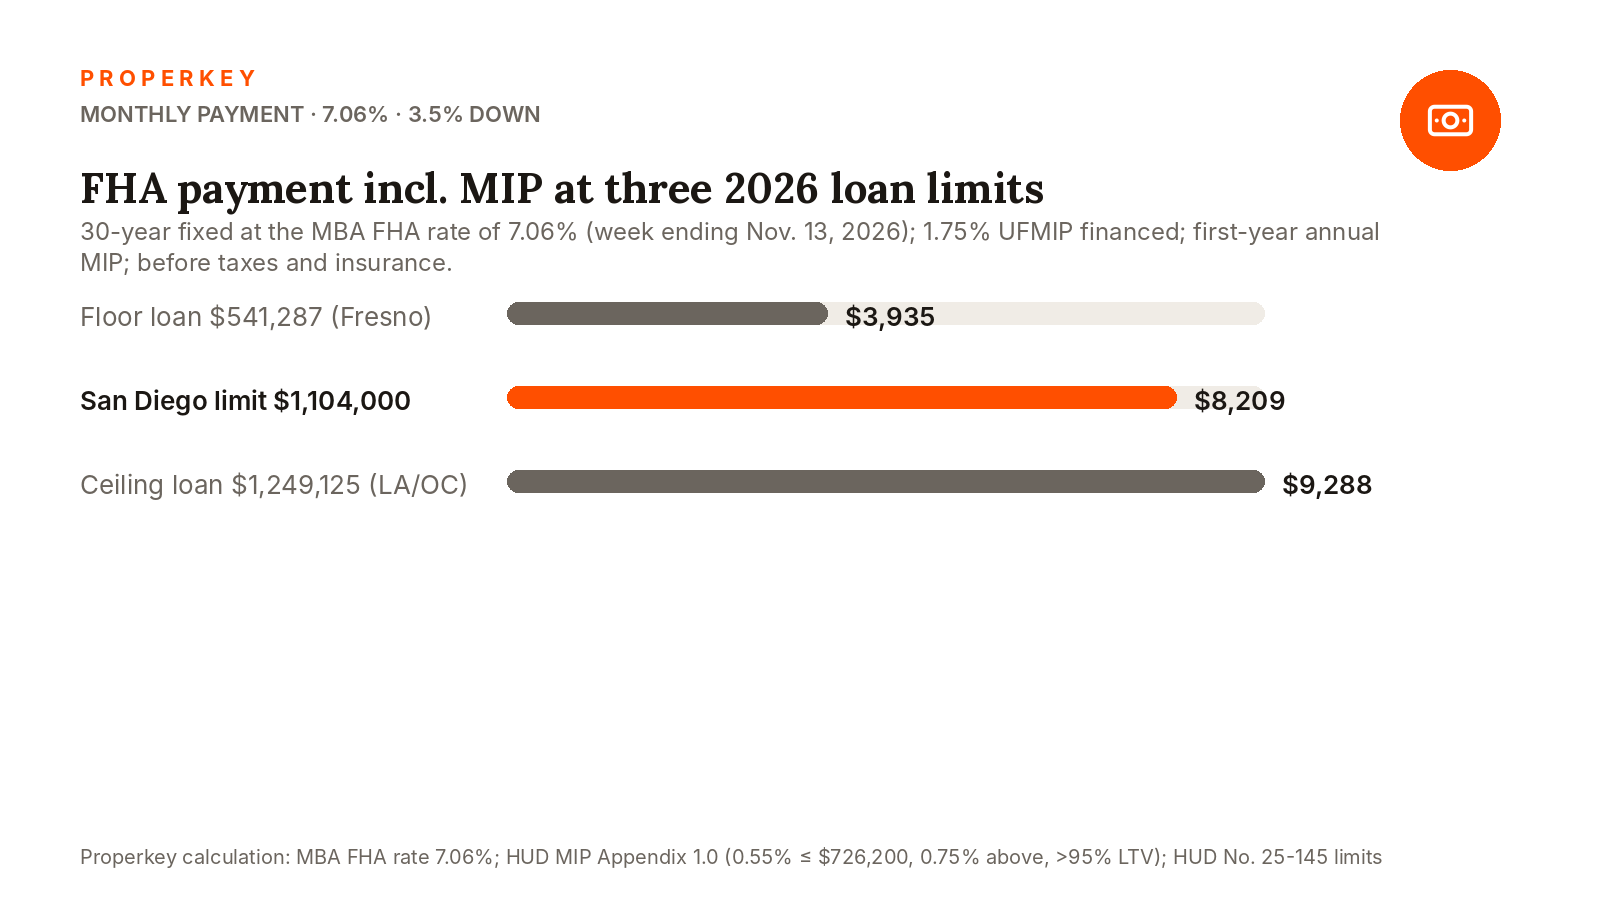
FHA rates sit below conventional. The Mortgage Bankers Association's survey for the week ending Nov. 13, 2026 put the 30-year FHA rate at 7.06% against 7.35% conforming (MBA); Optimal Blue showed FHA at 7.05% on Nov. 17; Freddie Mac's PMMS averaged 7.28% for all 30-year loans on Nov. 19 (Freddie Mac). At 7.06% over 30 years with 3.5% down, the UFMIP financed and first-year annual MIP added, the monthly cost before taxes and insurance is about $3,935 on a floor-limit loan of $541,287 ($3,686 principal and interest plus $248 MIP at 0.55%); about $8,209 on a San Diego-limit loan of $1,104,000 ($7,519 plus $690 at 0.75%); and about $9,288 on a ceiling loan of $1,249,125 ($8,507 plus $781 at 0.75%). Inputs: rate 7.06%, 360 payments, loan = base x 1.0175, monthly MIP = base x annual rate / 12.
Does CalHFA help with an FHA loan?
Yes. CalHFA offers an FHA first mortgage and layers its MyHome Assistance Program on top. Its government-loan FAQ and program matrix (Jan. 1, 2026) set a 640 minimum score for automated approvals (660 manual), DTI of 45% at 640–699 and 50% at 700-plus, required homebuyer education and impounds, and a loan no larger than the FHA county limit. MyHome (Oct. 19, 2026) is a deferred-payment, simple-interest second of up to 3.5% of the lesser of price or appraised value for first-time buyers under the county income limit. CalHFA's 640 is well above FHA's 580. Properkey's California down payment assistance guide covers the other programs.
Should you choose FHA or conventional?
FHA fits when your score is under about 680, your down payment is under 5%, or your DTI is above conventional limits. Conventional fits when you can put 10% to 20% down and want insurance that cancels. TransUnion's Q2 2026 data, reported by Scotsman Guide on Nov. 5, 2026, puts FHA at more than 47% of 60-plus-day delinquent mortgage balances, a two-decade high and one reason lenders keep overlays above HUD's floors. Properkey's overview of home loan types compares the options, and Properkey's finance line works the same for either: "Purchase or refinance, you apply once. We shop the lenders, you pick the terms."
Questions people ask
What is the minimum credit score for an FHA loan in California in 2026?
A 580 or higher Minimum Decision Credit Score qualifies for 3.5% down (96.5% LTV); 500 to 579 requires 10% down (90% LTV); below 500 is ineligible, per HUD Handbook 4000.1 and Mortgagee Letter 2026-11. Lenders may require more; CalHFA's FHA program requires 640.
What is the FHA loan limit in California for 2026?
By county, from the $541,287 floor (Fresno, Kern) to the $1,249,125 ceiling (Los Angeles, Orange, San Francisco, San Mateo, Santa Clara, Alameda) for one-unit homes, for case numbers assigned on or after Jan. 1, 2026. San Diego is $1,104,000, Sacramento $764,750, Riverside and San Bernardino $690,000.
Does FHA mortgage insurance ever go away?
With 10% or more down (90% LTV or less) the annual MIP ends after 11 years. With less than 10% down it lasts the life of the loan, so most 3.5%-down buyers remove it by refinancing to conventional at 20% equity. The 1.75% upfront premium is paid once, usually financed.
Will FICO 10T or VantageScore 4.0 change FHA qualifying in 2027?
Only the model, not the thresholds. For case numbers assigned on or after Jan. 1, 2027, lenders may use Classic FICO, FICO 10T or VantageScore 4.0, must use the same model for every borrower, and still pull a tri-merge report. The 580 and 500 cutoffs and the 31/43 manual ratios are unchanged.
This is a summary of the rules, not legal/tax advice; FHA policy and lender overlays change, and your lender's underwriter applies them to your file.
Sources: HUD Mortgagee Letter 2026-11 (Oct. 8, 2026); HUD Handbook 4000.1 (Aug. 12, 2026 update); HUD FHA INFO 2026-23 and 2026-24; HUD No. 25-145, 2026 FHA loan limits (Dec. 11, 2025); HUD Mortgagee Letter 2023-05, annual MIP (Feb. 22, 2023); LendingTree, 2026 FHA loan limits in California; JVM Lending, California FHA loan limits 2026; MBA Weekly Applications Survey, week ending Nov. 13, 2026; Optimal Blue OBMMI, Nov. 17, 2026; Freddie Mac PMMS, Nov. 19, 2026; CalHFA Government Loan Programs FAQ; CalHFA government program matrix (Jan. 1, 2026); CalHFA MyHome Assistance Program (Oct. 19, 2026); Scotsman Guide on TransUnion Q2 2026 delinquency data (Nov. 5, 2026); Properkey Finance.
Written by Keyro, Properkey's AI. Properkey, DRE #01979718.



