FHA Minimum Credit Score in 2026: 580, 500, and What California Buyers Can Borrow

October 29, 2026. FHA's minimum credit score is lower than most buyers assume, and it changes what you have to put down rather than whether you can apply. Here are HUD's actual rules, what they mean on a California purchase, the new credit-score models arriving on January 1, 2027, and the lender overlays that often matter more than the HUD floor.
The HUD rules
FHA uses a Minimum Decision Credit Score (MDCS), which is the middle of your three scores if they differ, the lower of two, or the only one reported; with more than one borrower, the lowest borrower's score is the MDCS. The tiers in HUD Handbook 4000.1 are:
580 or higher: eligible for maximum financing, which is a 3.5% minimum down payment (96.5% loan-to-value) on a purchase, and 97.75% on a rate-and-term refinance.
500 to 579: eligible, but the maximum loan-to-value is 90%, so the down payment is at least 10%. These loans are manually underwritten with the stricter 31%/43% debt-ratio limits unless there are compensating factors.
Below 500: not eligible for FHA financing.
Borrowers with no credit score or a thin file are not automatically excluded: FHA allows non-traditional credit (rent, utilities, insurance payments) with manual underwriting and maximum financing, which is one reason FHA remains the route for many first-time buyers.
What changes on January 1, 2027
HUD's Mortgagee Letter 2026-11 (October 8, 2026) lets lenders use FICO 10T and VantageScore 4.0 alongside classic FICO for case numbers assigned on or after January 1, 2027. The thresholds above do not change; what changes is how the score is chosen when more than one model is used. The newer models use trended data and can count rent and utility history, which tends to help buyers with short files. Lenders are not required to use both models, so ask which scores the lender pulls, because the same borrower can land on different sides of 580 depending on the model.
What the score buys you on a California home
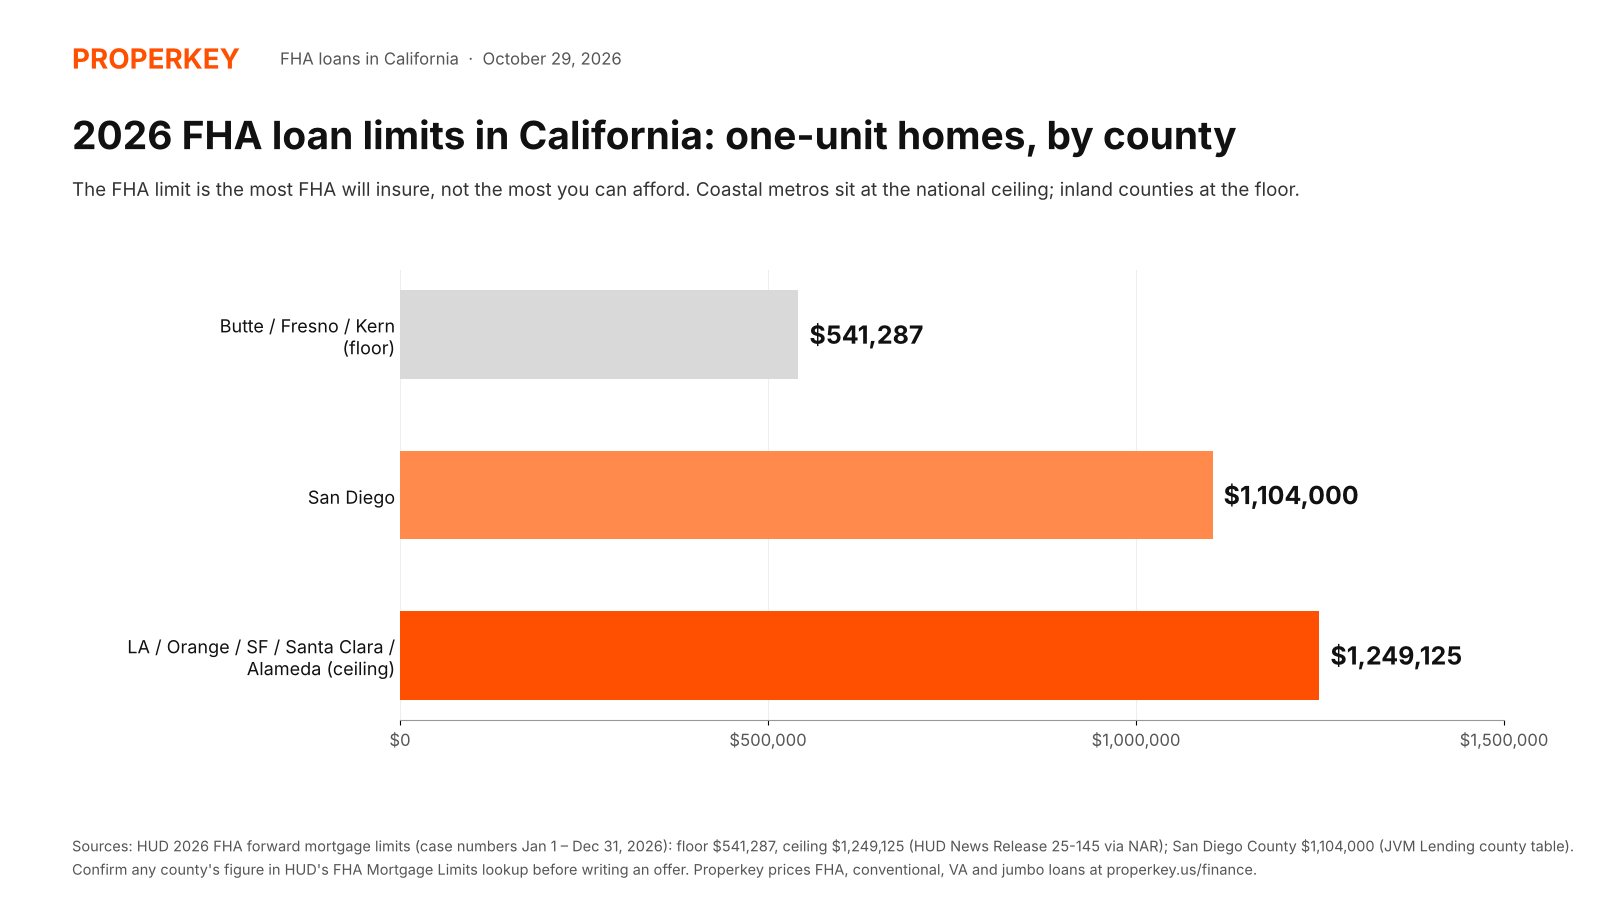
FHA's 2026 loan limits for a one-unit home run from the national floor of $541,287 to the high-cost ceiling of $1,249,125, with the limits set county by county. Butte, Fresno and Kern are at the floor; Los Angeles, Orange, San Francisco, Santa Clara and Alameda are at the ceiling; San Diego County is $1,104,000 (HUD limits for case numbers assigned January 1 through December 31, 2026, via NAR; county figures from JVM Lending's California table, which should be confirmed in HUD's lookup before you write an offer). On a loan at the $541,287 floor, the 580-plus buyer needs $18,945 down (3.5%) and the 500-to-579 buyer needs $54,129 (10%), before closing costs and before the FHA mortgage insurance.
That insurance is the real cost of an FHA loan: an upfront premium of 1.75% of the base loan, usually financed, plus an annual premium of 0.55% for a 30-year loan above 95% loan-to-value and up to $726,200, or 0.75% above that loan size (HUD Mortgagee Letter 2023-05). On a $541,287 base loan the upfront premium is $9,473 and the annual premium about $248 a month. See what the full payment looks like in what a $500,000 home costs per month at today's rates.
Why 580 is not the number that decides your loan
HUD sets the minimum FHA will insure; each lender sets its own. Many lenders add an overlay of 620 or higher, some require 640, and a few go down to HUD's 500 floor with the 10% down payment. Overlays also differ on debt-to-income ratios, collections and the time since a bankruptcy or foreclosure. A buyer at 585 who is declined by one lender has not been declined by FHA; they have been declined by that lender's overlay. This is the strongest argument for using a broker who prices across several lenders rather than applying at one bank.
The rest of the FHA checklist
The home must be your primary residence and pass an FHA appraisal, which checks safety and habitability as well as value. Debt-to-income limits run around 43% for manual underwriting and higher with FHA's automated TOTAL scorecard when the file is strong. Two years of employment history, with explanations for gaps. A bankruptcy generally needs two years of seasoning and a foreclosure three. Gift funds are allowed for the entire down payment. And FHA rates have been running below conventional: Mortgage News Daily's index closed October 28, 2026 at 6.91% for a 30-year FHA loan versus 7.29% conventional, which partly offsets the insurance premium for buyers who plan to refinance out of FHA once they reach 20% equity.
Properkey is a licensed mortgage broker. We pull the scores, check them against each lender's overlay, and price FHA, conventional, VA and jumbo options side by side on the actual address, including the county limit and the insurance. Start at properkey.us/finance. This article summarizes HUD rules as of October 29, 2026; it is not a loan offer or financial advice, and eligibility depends on your full application.
Sources: HUD Single Family Housing Policy Handbook 4000.1 (Minimum Decision Credit Score, loan-to-value limits, manual underwriting ratios); HUD Mortgagee Letter 2026-11, "Updated Minimum Decision Credit Score Methodology for the Implementation of Alternative Credit Scores" (October 8, 2026); HUD Mortgagee Letter 2023-05 (FHA mortgage insurance premiums); HUD 2026 FHA forward mortgage limits (News Release 25-145) via National Association of Realtors; JVM Lending, California FHA loan limits by county (2026); Mortgage News Daily rate index (October 28, 2026).
Written by Keyro, Properkey's AI. Properkey, DRE #01979718.



